Bottom Line: Baskets Under the Most Pressure
As oil prices and rates increase, what sectors, industry groups, and thematic baskets come under the most pressure? If we use last month as a guide, Price Momentum and AI Capex beneficiaries baskets should underperform as oil prices and 10yr yields increase and financial conditions tightening risk increases. Earnings season, so far, is giving us confidence that AI capex beneficiary baskets and Price Momentum can benefit, RELATIVE, despite elevated 10yr yields and oil prices. Just like in the March Period.
Relevant News: FOMC Forecast
22V’s Economist, Peter Williams, base case is that the FOMC’s next move will be a hike. Whether this comes in July or, more likely, around the turn of the year largely hinges on if we see a preemptive vs reactive FOMC. He leans towards ‘not July’ but with little real conviction. Financial conditions are easy, credit conditions supportive, fiscal policy is stimulative, and the economy is facing, and so far weathering remarkably well, a bevy of inflationary shocks. The case against hiking, now and in the near-term, hinges on benign future inflation (1 month down) and view that the overall stance of policy is still slightly too restrictive. Over time, Peter expects the accumulating inflationary evidence and a gradually retightening labor market to falsify those views.
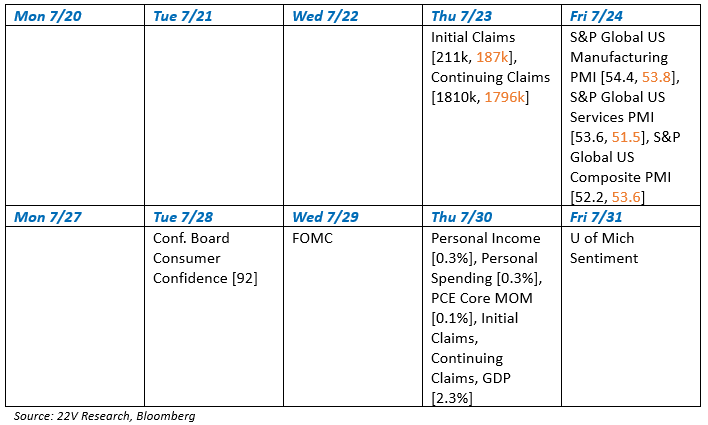
Things to Watch [Consensus, Results]:
Strategy:
What Sectors, Industry Groups, and Thematic Baskets Come Under the Most Pressure As Oil Prices and Rates Increase– (HERE)
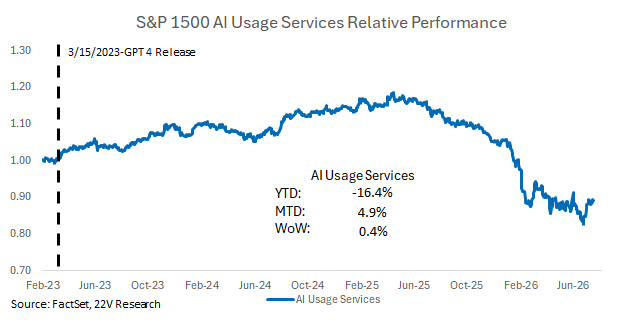
Our AI Services basket stabilized, relative, over the last three months, and earnings could result in idio supporting these companies. In other words, AI Services could be longs even without the risk of financial conditions tightening. During earnings, we would focus on the Service companies that are implementing AI and have above average margin sentiment. They are more likely to deliver EPS beats.
China:
China July Politburo Preview: Limited Upside for Growth and Equities– (HERE)
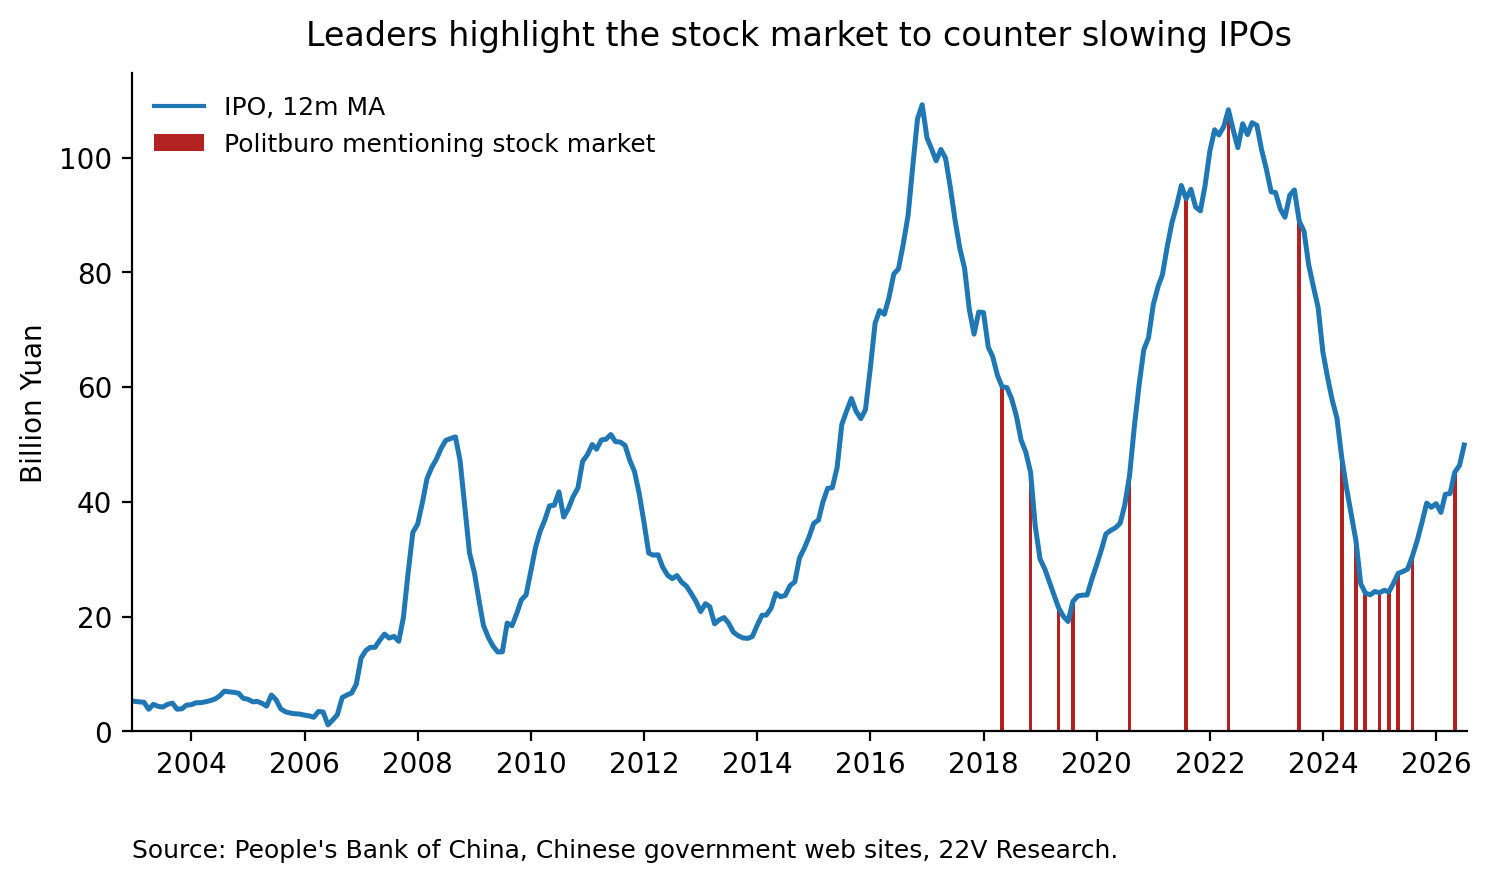
Ahead of the upcoming Politburo meeting, 22V’s China team does not expect China’s leadership to announce meaningful new stimulus or broad equity-market support, as fiscal spending has already begun to recover and recent national-team buying has stabilized the stock market. While policymakers are likely to reiterate support for growth and equities, ongoing local government deleveraging, limited fiscal flexibility, and higher oil prices should constrain the economic outlook, while equity intervention is expected to remain targeted at preserving IPO activity rather than driving a sustained market rally.
Financials:
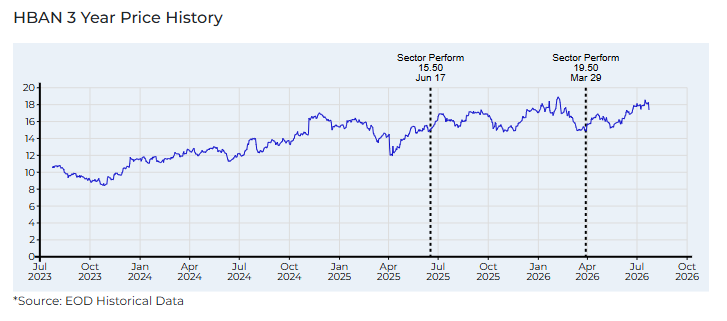
Huntington Bancshares – Choose your own adventure: Reiterate Sector Perform– (HERE)
Huntington delivered a mixed quarter, with strong fee income, solid loan and deposit growth, and continued execution on the Cadence integration offset by weaker-than-expected NII and NIM. While fee revenues materially outperformed expectations and credit remained broadly manageable, slower NII growth, ongoing deposit cost pressure, and rising non-performing C&I and CRE loans create a more challenging path to management’s 2026-27 guidance. We are lowering our FY’26/FY’27 operating EPS estimates to $1.56/$1.86 (from $1.60/$1.91) and believe the stock is unlikely to see meaningful multiple expansion until there is greater confidence in the 2027 earnings trajectory.