Back Portfolio Strategy

Bank Earnings & the Longer Term AI Buildout + Plays Into This Week’s EPS Reports

Published on July 20, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Kevin Brocks

Sophia Wang

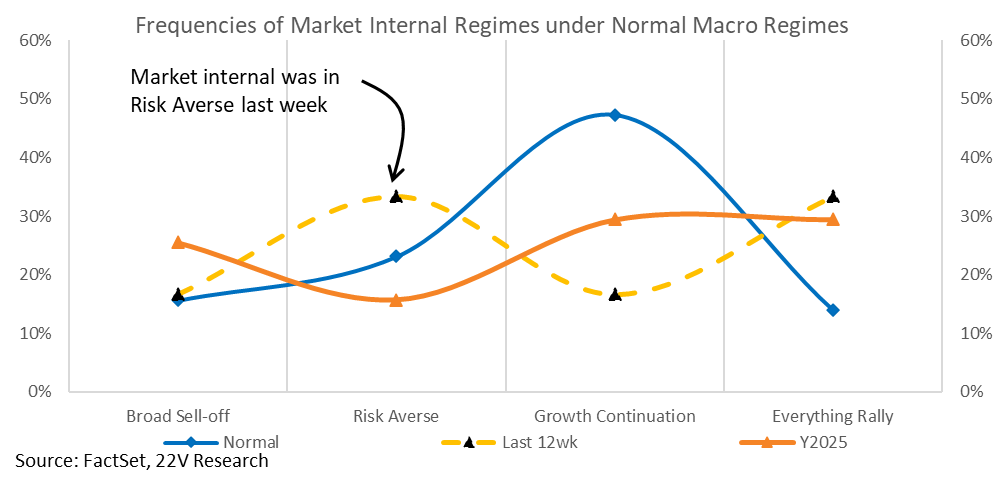
DAILY STRATEGY: The two most prevalent market internal regimes* have been Risk Averse and Everything Rallies over the last 12 weeks. With the last 3 weeks being dominated by Risk Aversion. If we are going to get a shift back to an Everything Rally regime (Momentum would be a leader) fundamentals are likely to be a major driver. Most investors we surveyed (HERE) expect the level of Hyperscaler capex in 2027 (median $1.1T) will support the AI buildout trade. As noted last week, any short-term call on the Price Momentum basket needs to be held with low conviction given the unusually high volatility of the basket.

FYI – If larger than expected 2027 AI Capex numbers are driven by inflation, that would be considered a negative for the hyperscale’s. In which case, the S&P 500 would have some downside risk. We are not saying that will happen, but that is a fear amongst investors we talk to. 22V options Strategist Jeff Jacobson has some ideas on hedging S&P 500 risk now. He notes S&P 500 puts are “CHEAP” to QQQ puts on a historical basis, making SPY puts a better risk/reward hedge in his view (HERE).

Market to Market What We Think Matters for the AI Buildout Theme Longer Term – What all companies say about AI related value creation – is the stock indicating positive margin outlooks and productivity gains related to AI – is one of the most important longer term determinants of AI capex spend. Put simply, the more value creation at the enterprise level the higher the AI demand.

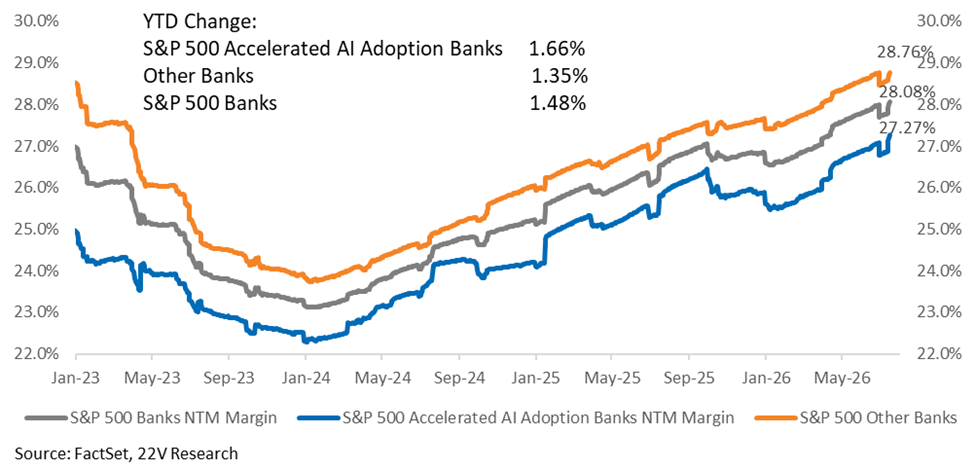
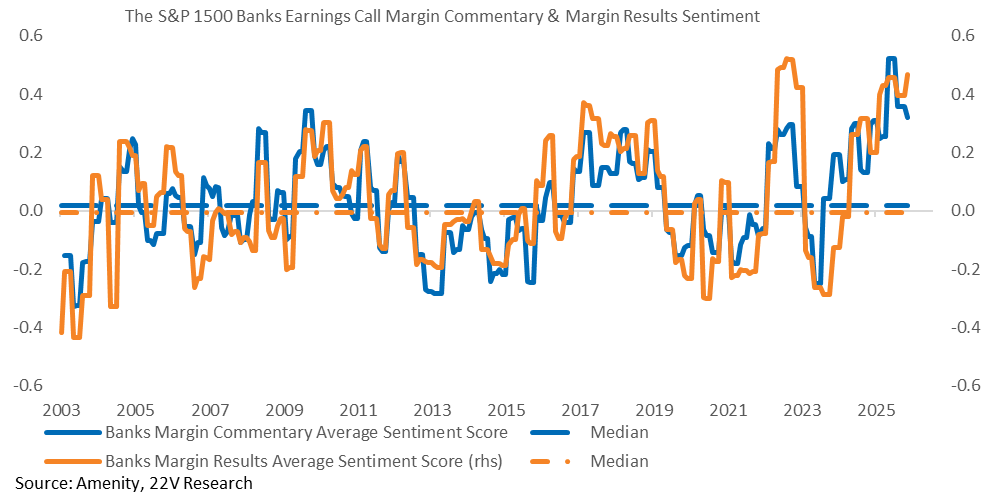
What we heard from banks last week was positive on the margin and AI value creation fronts. Margins are trending higher across Bank, but names with higher AI adoption have seen margins improve more rapidly than those of other Banks this year. The strong margin trend is another sign that AI is moving from strategic narrative to operational reality. Margin Results Sentiment (how Banks sounded about this quarter) ticked up, reaching its highest level since 2023. Forward looking Margin Commentary Sentiment ticked down from its recent high, it remains above any level seen prior to 2025.

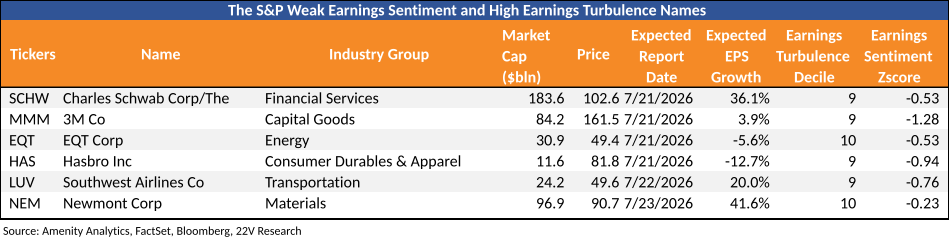
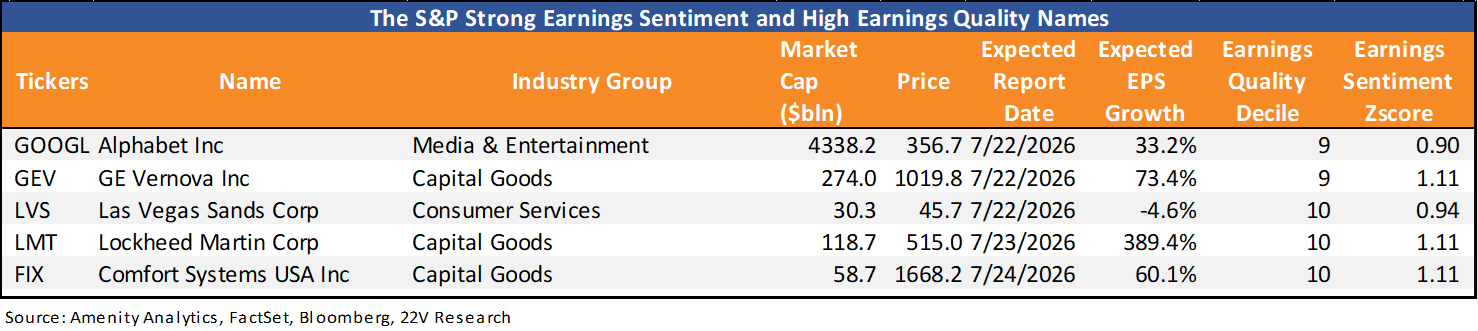
Airline Trade Idea LUV: Each earnings season the 22V quant team ranks companies due to report to identify companies that could see outsized moves (both higher and lower) based on positive or negative earnings quality and sentiment. Stocks with a lower Earnings Turbulence ranking, higher Earnings Quality ranking and Earnings Sentiment score have better fundamental readings and are more likely to beat earnings, and vie versa. Lists in the chart section below. These lend themselves to options plays. Jeff Jacobson, 22V’s Derivatives specialist, likes the set up to hedge LUV the best. FYI, reach out to JJ for structures for any of the other names.

Trade:
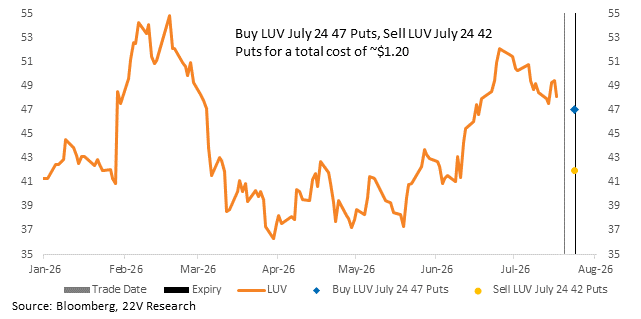
Buy LUV July 24th 47/42 put spread for ~ $1.20 (LUV 48.08 Fri close ref)

*The market internal regime is a quantitative classification used to measure how various investment factors—such as Value, Growth, Momentum, and Quality—trade relative to each other at any given time. The internal regime identifies which specific segments of the market are leading or lagging in the short term.

Charts…

The two most prevalent market internal regimes* have been Risk Averse and Everything Rallies over the last 12 weeks. With the last 3 weeks being dominated by Risk Aversion.
Margins are trending higher across Bank, but names with higher AI adoption have seen margins improve more rapidly than those of other Banks this year.
Currently, margin sentiment expressed by Bank management is supportive, reflecting strong bank confidence in current operating margins and the near-term outlook. While forward looking Margin Commentary Sentiment ticked down from its recent high, it remains above any level seen prior to 2025. Margin Results Sentiment ticked up, reaching its highest level since 2023.
A graph of a graph with blue and orange lines

AI-generated content may be incorrect.

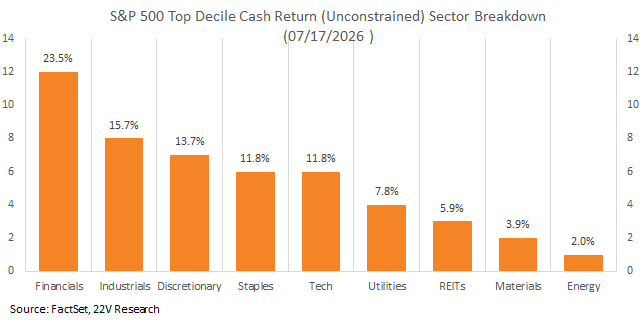
The cash return factor relative performance has improved and Financials have the largest exposure to the cash return factor.
The beat list…
A screenshot of a computer screen

AI-generated content may be incorrect.

The miss list…

From JJ…

“Looking at LUV options, the current implied move of 6.2% actually looks “cheap” when we consider the 10% average 1-day move over the last 4 reports (3 lower), which also included an 11.2% decline for this quarter 1-year ago. The fact that the current implied move trades at a discount to the recent realized moves is another reason I suggest owning the weekly put spread as a tactical short bet play.”


Trade:
Buy LUV July 24th 47/42 put spread for ~ $1.20 (LUV 48.08 Fri close ref)

Trade Details:

  • Buying the weekly put spread that captures earnings on 7/22
  • Airlines had rebounded sharply from their March declines as oil spiked, starting to see weakness as oil is back on the rise
  • DAL and UAL both reported and traded lower, LUV is also less exposed to the business traveler which could impact earnings
  • Options implying a 6.2% 1-day move, which actually screens “cheap” to recent realized moves
  • Put spread starts just over 2% lower, is capped ~ 11% lower (same decline shares had a year ago), and offers a 4x to 1 max payoff on the limited-risk trade
  • Please reach out to me or the 22V sales team for updated pricing and execution capabilities
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.