Back Derivatives Strategy

Now That the Mag7 Have Played Catch-Up, Time to Get Aggressive With Index (SPY) August Hedges

Published on July 19, 2026

∙ Download the PDF Report

By

Jeff Jacobson

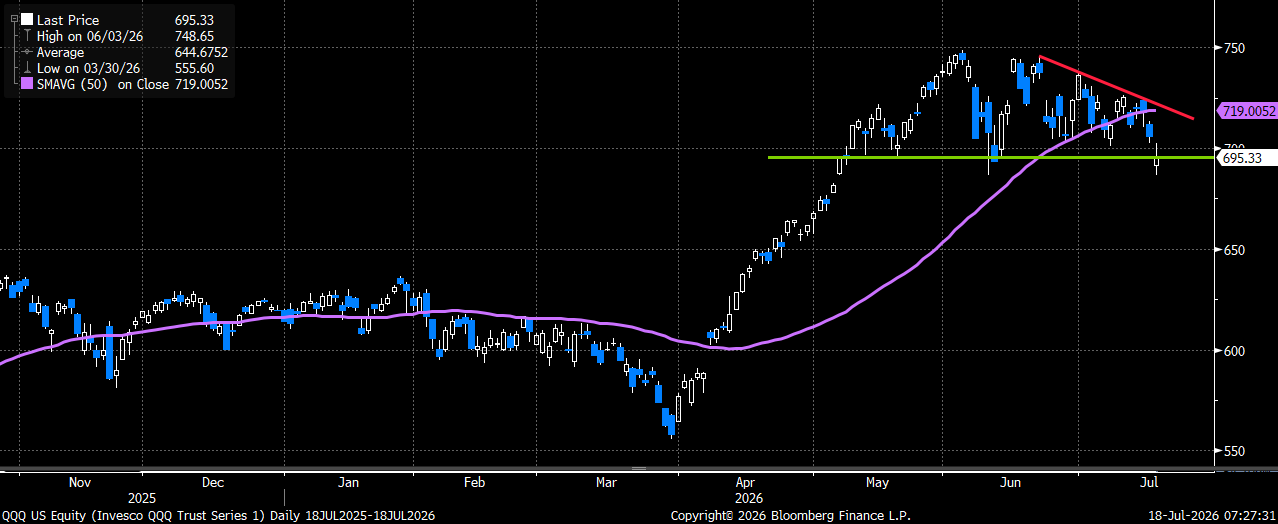
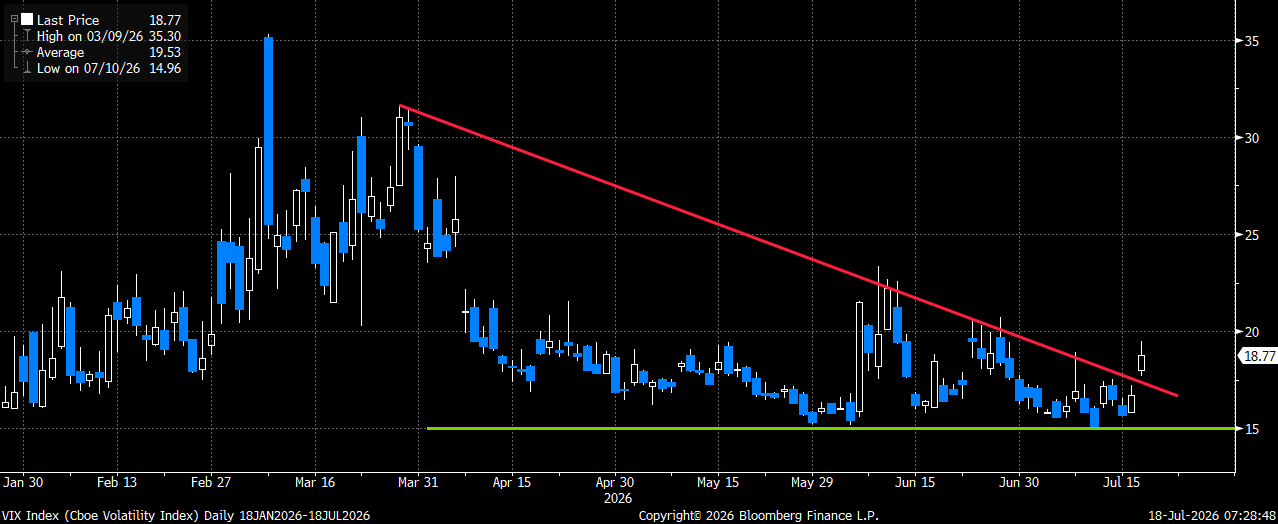
Last week brought more volatility and weakness to all the major averages. Technology (QQQ) shares led the decline, with that index hitting two-month lows. Last week I suggested owning August VIX calls or call spreads (here), and the VIX index jumped ~ 25% to end the week on the highs (VIX August futures rose ~ 5.5%). While I suggested owning VIX structures as more of a tail hedge for the market, I now believe investors need to be more aggressive with their index hedges given the action I am seeing.

QQQ with a break below recent support after failing to make a new high on the June market rebound
A graph with lines and dots

AI-generated content may be incorrect.

VIX index broke above the March downtrend after holding support once again at the 15 level
A graph with a red line

AI-generated content may be incorrect.

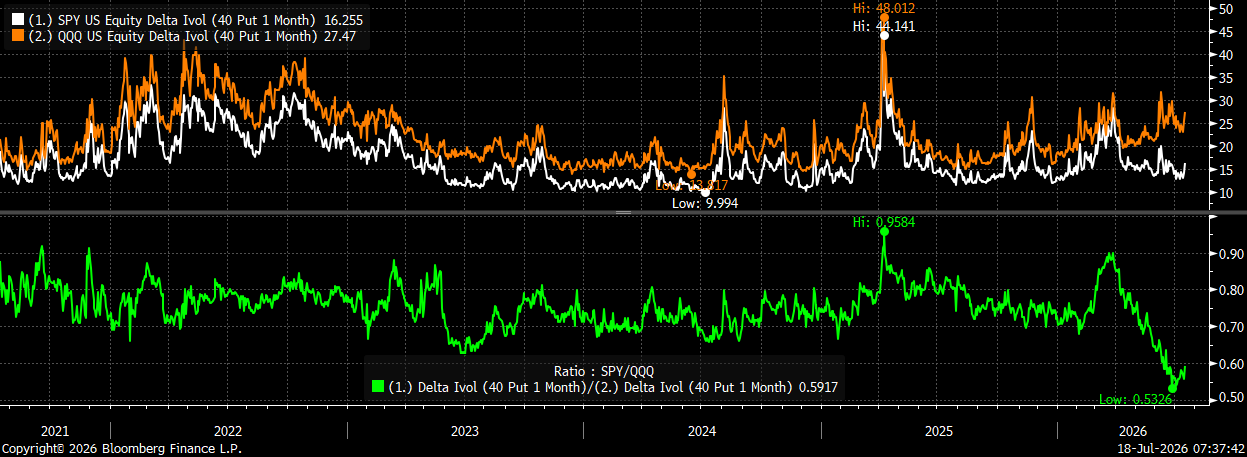
With tech leading the selloff, it makes perfect sense to consider owning QQQ hedges, especially as we are about to start earnings season for most of the largest names. With that being said, I actually believe that SPY hedges offer a better risk/reward profile at this time. There are a few reasons why I prefer SPY hedges now. First, SPY puts are CHEAP to QQQ puts on a historical basis. The 1-month (Aug) SPY 40-delta puts currently trade at a 16.25 implied vol, while the same duration/delta QQQ puts trade at a 27.50 IV. This put skew means that SPY puts only cost less than two-thirds of what QQQ puts cost (the actual number is .59), which means they are trading just above the cheapest skew in the past 5 years. Put another way, QQQ would have to underperform SPY to more than a 1.6x beta to make owning those puts a better option than SPY puts (QQQ beta to SPY YTD has been closer to 1.4x)

SPY 1-month (Aug) 40-delta puts are trading near their cheapest levels to QQQ puts in over five years (bottom chart)
A graph of a graph

AI-generated content may be incorrect.

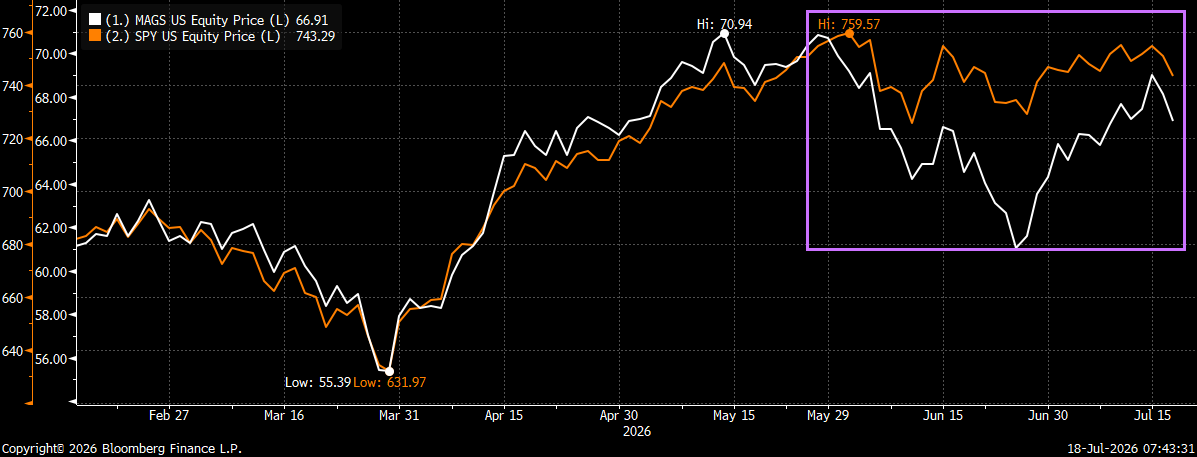
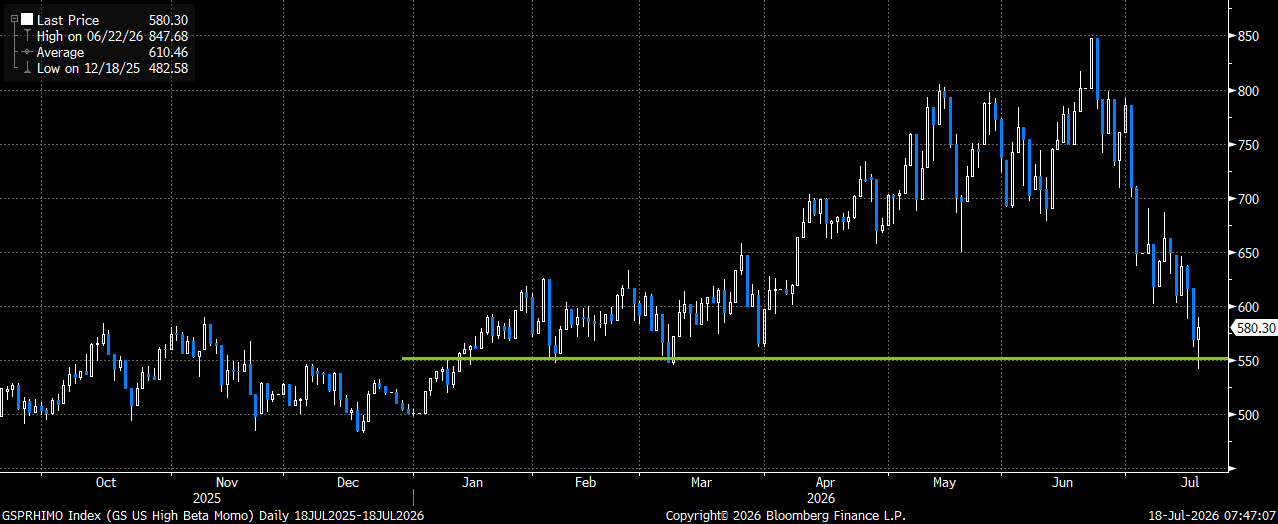
Second, the Mag7 (MAGS) were a big reason why both QQQ and SPY were unable to make new highs in June, even though the memory/AI trade was working extremely well. With the sharp correction we just saw in that AI momentum trade, clearly a lot of that money flowed back into the Mag7/hyperscalers. That dynamic helped close the very wide gap between where SPY and MAGS had been trading. Now that they have “caught-up”, any weakness by those heavily-weighted names from here is likely to put downside pressure on the S&P. The Goldman Sachs High Beta Momentum index also pulled back to the recent support, which could be signaling a rotation back into the momentum trade (at the expense of the Mag7 once again)

We saw the Mag7 (MAGS) close the gap to SPY as money came out of the AI momentum names the past few weeks
A graph on a black background

AI-generated content may be incorrect.

The Goldman Sachs high beta momentum index with a pullback to the recent lows (could be signaling another potential rotation)
A graph on a screen

AI-generated content may be incorrect.

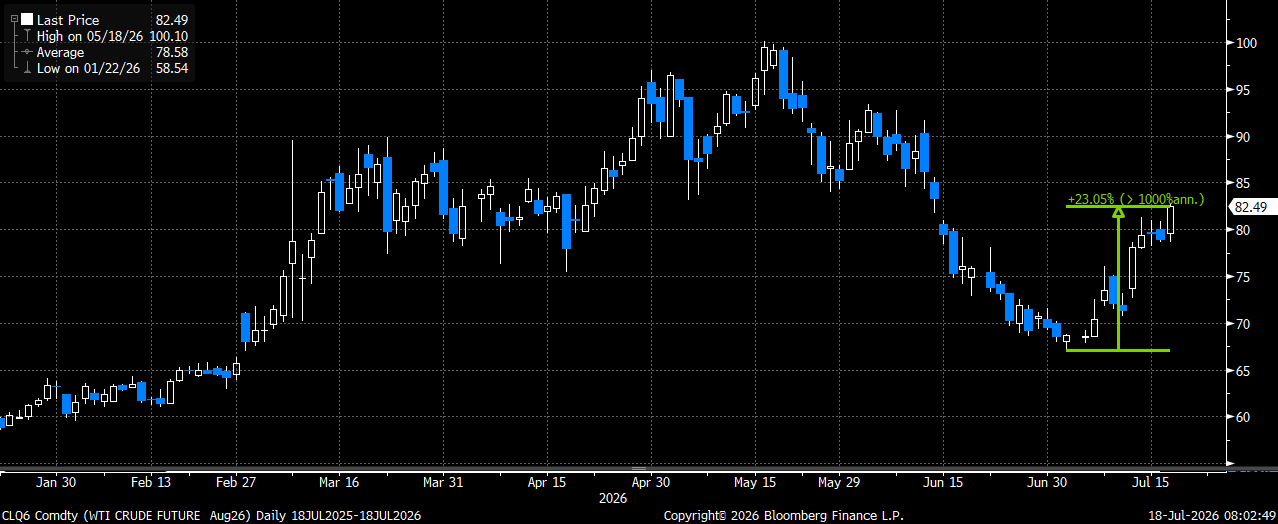
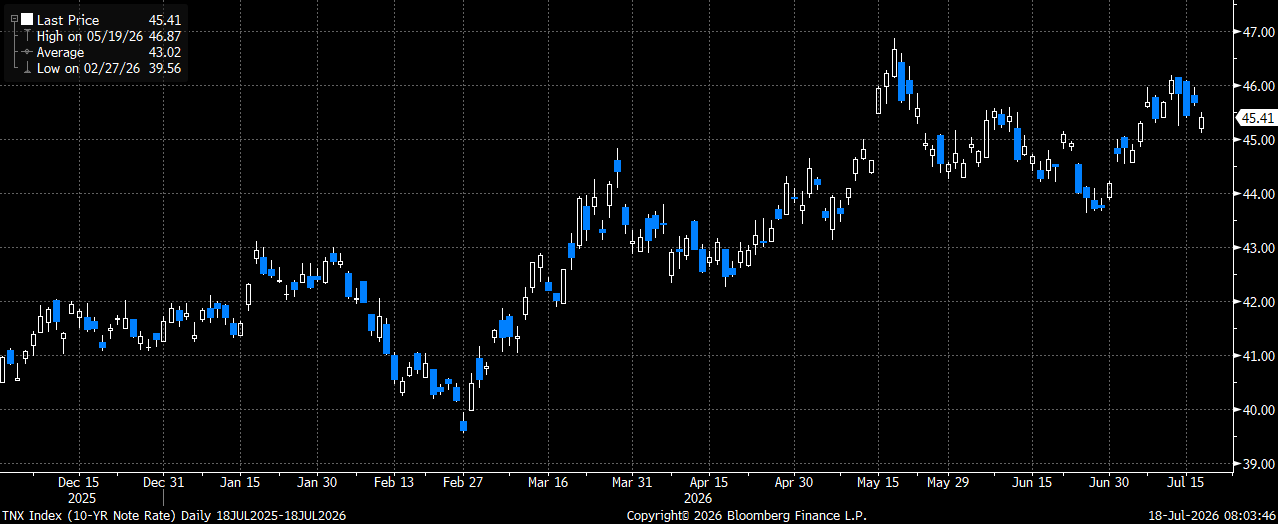
Against this backdrop, SPY is only down ~ 2% from the all-time highs that were established in early June. This is with oil starting to move back higher as geopolitical concerns are ignited once again, and with yields unable to move down meaningfully (even on somewhat benign inflation reports). The sharp rotation back into the Mag7, as well as financials, helped mask a lot of the weakness under the hood (specifically in the AI momentum trade), but as we head into earnings for the group, I’m just not sure how much further heavy lifting they can do? As it is, Apple (AAPL) has risen by 22% since the momentum basket peaked on 6/25, and it now trades at nearly 40x.

Oil has risen by ~ 23% off the recent lows as tension in the Middle East are back on the rise
A graph on a black background

AI-generated content may be incorrect.

10-year yields remain just below their May highs, even as the recent inflation data came in on the dovish side
A graph with blue and white lines

AI-generated content may be incorrect.

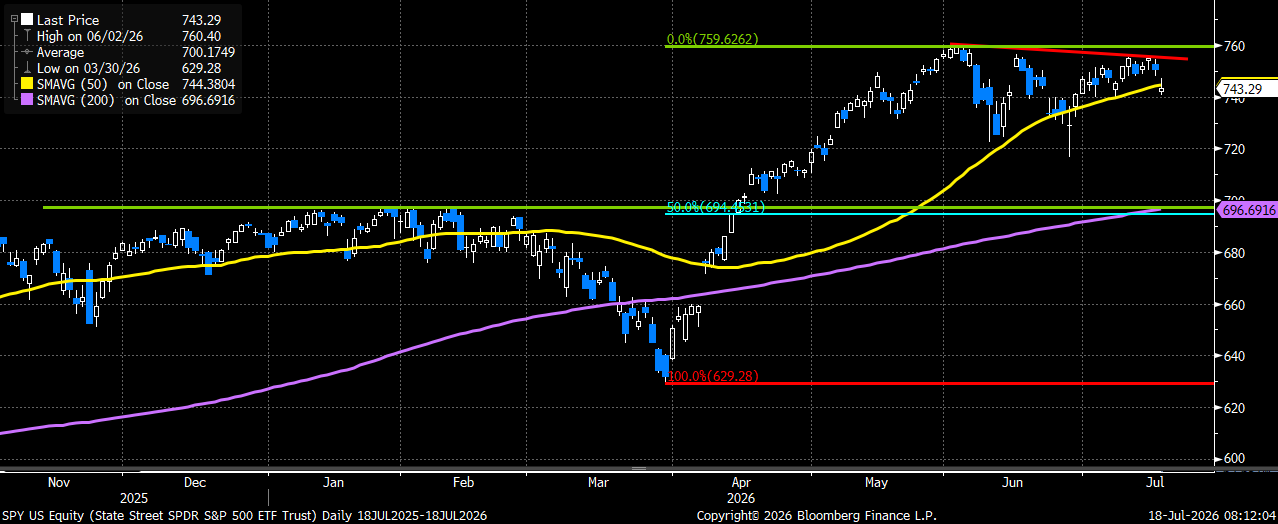
Looking at the SPY chart, it was also unable to eclipse the early June highs, even as the heavily-weighted Mag7 and financials were attracting flows as the AI momentum trade was being unwound. SPY closed below the 50-day on Friday, and appears to be in danger of further declines, especially if we see money leave the groups that did most of the work on the latest move higher off the late June lows. On a tactical basis, I would be targeting a pullback to the 695-700 area as it appears that should be the next major support level. Not only is the rising 200-day moving average support at that level, but that was also the former highs from Jan/Feb and is also represents a 50% retracement of the move off the March lows to the June highs.

All roads lead to 695-700 for SPY should we see a more meaningful decline
A graph of stock market

AI-generated content may be incorrect.

Even though SPY puts trade cheap to QQQ, and implied vol is still closer to the 6-month lows, I still prefer to own August put spreads over outright puts that target a potential decline to that 695-700 level I mentioned above. Owning a put spread will reduce the cost of the hedge, while also capturing ~ 6 points of vol skew.

Trade:
Buy SPY August 21st 730 puts
Sell SPY August 21st 690 puts
Costs ~ $5.80 (SPY 743.29 Fri close ref)

Trade Details:

  • Buying the SPY August put spread for an index-level hedge as we head into earnings season for the Mag7
  • Hedge starts ~ 2% lower and offers a nearly 6x to 1 max payout on expiration
  • Selling the 590 put covers 35% of the cost of owning the much closer to the money protective put
  • SPY vol trading near cheapest skew to QQQ vol in the last 5 years
  • Could start to see another rotation out of the Mag7/hyperscalers and back into the AI momentum names (much like we saw thru most of May and June)
  • Higher oil prices and yields could start to weigh on stocks again
  • Put spread is capped to the downside at 690. This is not only more than 7% lower, but is also just below what I expect to be strong support (200-day, former highs and 50% retracement)
  • Please reach out to me or the 22V sales team for updated pricing and execution capabilities

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.