Back Shoot Around

22V Afternoon Shoot Around: SOH, Near Term Backdrop, and AI Update

Published on June 15, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: Near Term Backdrop

The near-term backdrop, defined as the next few months, will continue to support Cyclicals and fundamental factors (Earnings Momentum, Earnings Growth, Value, GARP). Retail, Regional Banks, Airlines, and Homebuilders are early Cyclical industry groups that should “catch up” over the coming months. It’s tough to have a high conviction LONGER TERM (next 6-12 months and beyond) view on Cyclicals and fundamental factors outperforming. Actual inflation data is so high, that we are forced to focus on a shorter time frame.

Relevant News: Iran Update

The emerging U.S.-Iran ceasefire deal would be a strategic win for Iran and a setback for both the U.S. and Israel, as it reopens the Strait of Hormuz, eases economic pressure on Tehran, and focuses narrowly on nuclear negotiations while leaving Iran’s missile, drone, and proxy capabilities untouched. The agreement reflects political and economic pressure on President Trump to end the conflict, weakens future U.S. military deterrence, and leaves Israel dissatisfied. For oil markets, however, the deal is broadly bearish, as reopening the Strait should normalize energy flows and reduce immediate supply risks, though Israel’s actions in Lebanon remain the key threat to the agreement’s durability.

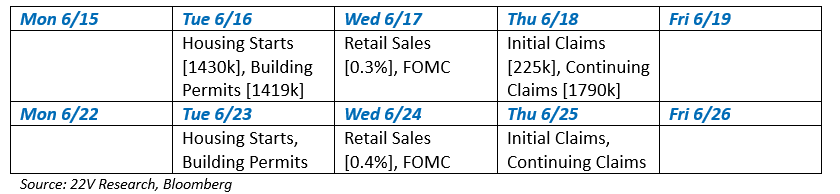
Things to Watch [Consensus, Results]:
A close-up of a table

AI-generated content may be incorrect.

Strategy:

SOH Reopening Means a Fed on Hold and Low Nearby Risk of Tighter Financial Conditions – (HERE)

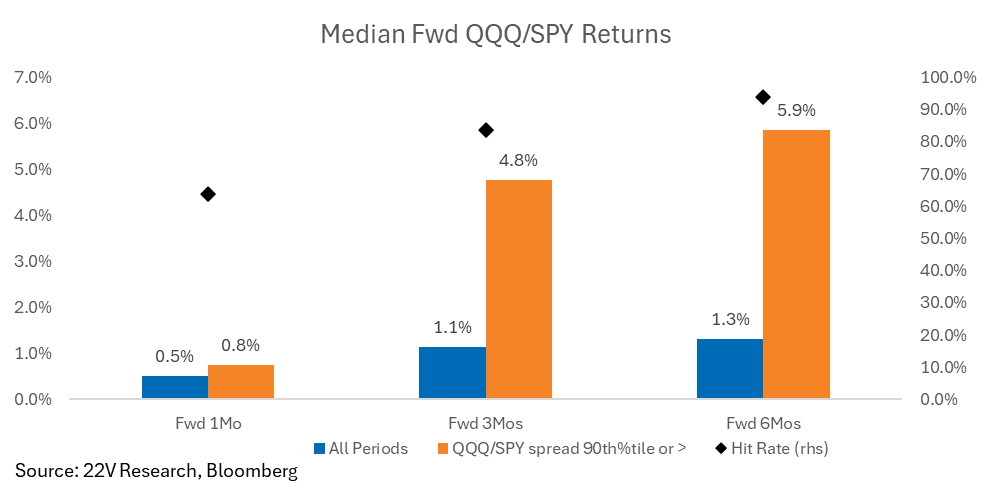
The change in the QQQ versus the SPY between 3/30 and 6/1 was in its 99.8th%tile. This was a 2.77 standard deviation return. When the spread between the two over ~2months is in its 75th %tile or 90th %tile, the forward returns on a 1,3, and, 6-mo basis are higher than typical for QQQ (+3.3% for 75th %tile or +5.9% for 90th %tile over 6 months). Our read of the implied 3 and 6-mo returns using current QQQ options pricing is above typical.
A graph of a number of people

AI-generated content may be incorrect.

AI Macro Nexus

The AI Mid-Cycle Slowdown: From Building Intelligence to Applying It – (HERE)

The AI investment cycle appears to be shifting from its explosive early phase—driven by model breakthroughs, data center spending, and compute scarcity—into a mid-cycle stage where the key opportunity moves from building intelligence to applying it. While infrastructure demand remains strong, future returns are likely to become more selective as leadership rotates toward software, enterprise productivity, drug discovery, healthcare, and financial systems that enable autonomous AI agents to transact and operate in the real world. The core thesis is that AI’s long-term growth story remains intact, but the easiest gains in hardware have largely been captured, making the application layer the next major source of value creation.

Data Infrastructure / Commodities:

Mythos Restriction and the Second Derivative Question — A Quick Update on Themes – (HERE)

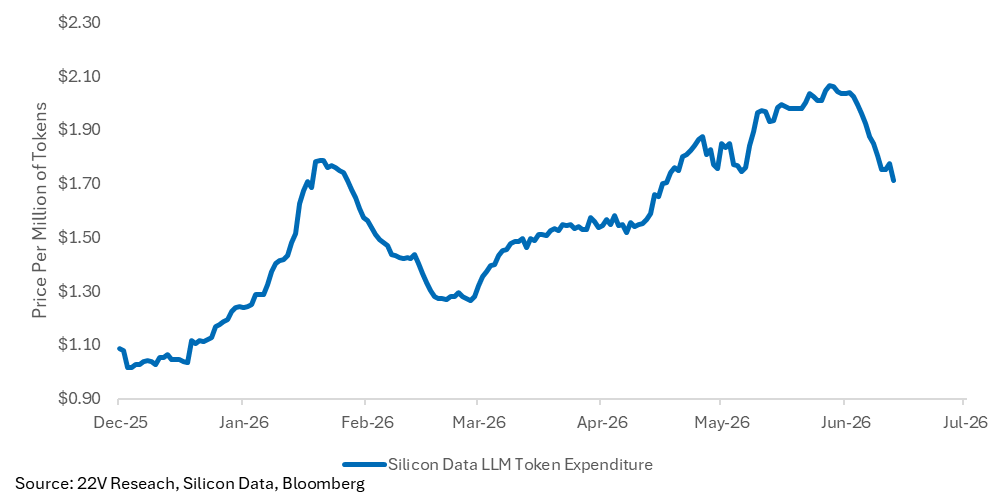
AI is facing a new challenge as regulation joins power and job displacement concerns. The restriction of Anthropic’s Mythos-class models raises questions about AGI development, global AI adoption, and enterprise confidence, while declining AI token prices, softer spending signals, and significant equity issuance create second-derivative growth concerns. Although these factors could drive a near-term pause in the AI trade, we continue to favor infrastructure themes such as cooling, thermal management, and space, while closely watching AI token and compute price discovery as the next phase of the cycle unfolds.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.