

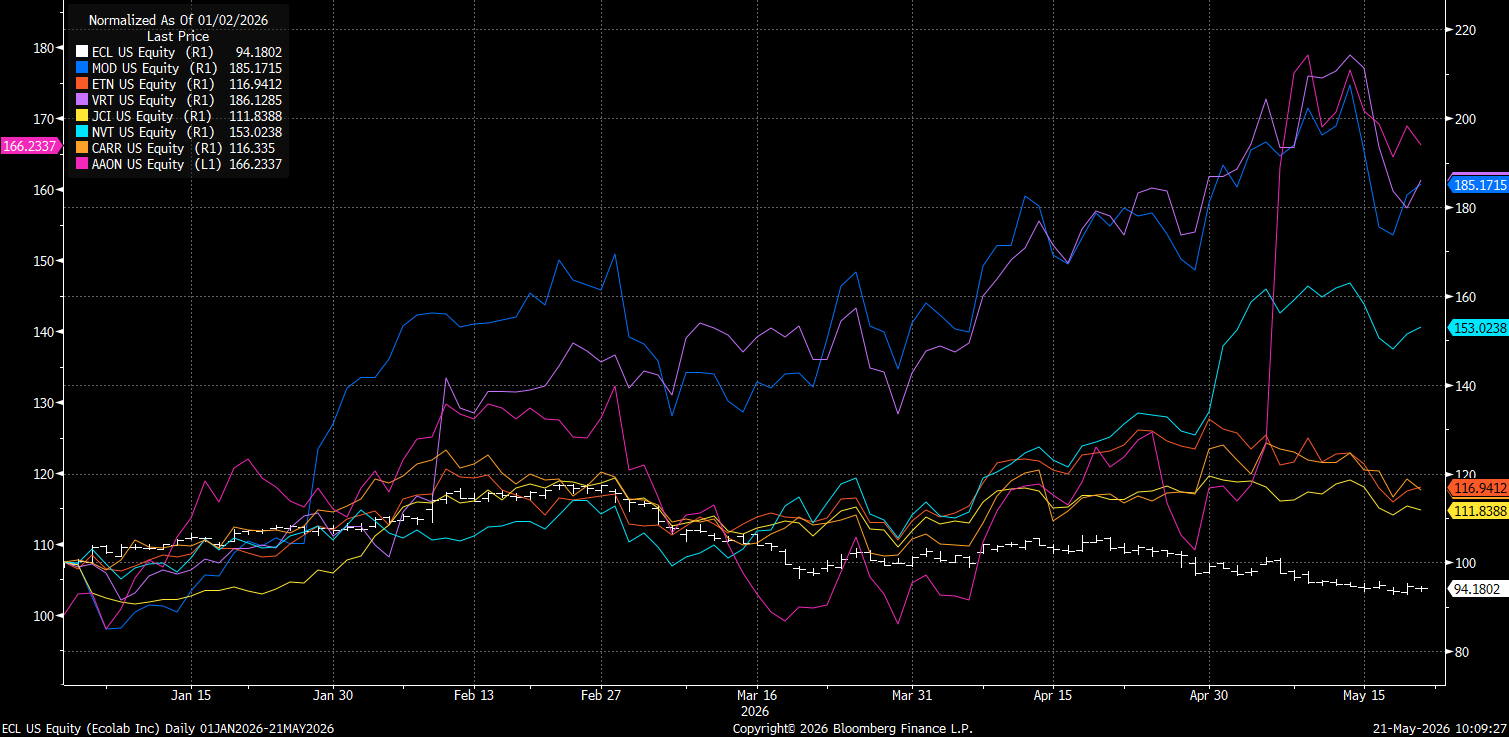
ECL was among our primary liquid cooling beneficiaries (The Next AI Backlog Story – Liquid Cooling, 5/6/26). The stock has underperformed the liquid cooling peer group YTD, weighed down by Iran-related oil price inflation. We believe closing of the CoolIT acquisition in Q3 and potential oil price relief are the two positive catalysts that redirect investor focus to ECL’s growing exposure to liquid cooling and AI capex.
CoolIT acquisition: On track for Q3 close:
On May 15th the Canadian Competition Bureau issued an Advanced Ruling Certificate (ARC) — an important regulatory go-ahead step. Subsequently, on May 19th ECL announced a $5B bond offering, signaling the deal is in final stages to close.
Highlights from a conversation with IR:
Combined offering: ECL’s $1.5B high-growth tech exposure scales materially post-close. The combined platform pairs ultrapure water and 3D Trasar monitoring with CoolIT’s cooling stack (CDU, manifolds, cold plates), plus proprietary coolant fluids and 6-second operational diagnostics. Management views direct-to-chip cooling as a 3–5× revenue lift versus legacy air-cooled data center architecture.
Go-to-market readiness: Management indicated they are prepared to be in the market with a combined offering immediately upon close. CoolIT is actively engaged with chip developers on next-generation designs — a competitive validation.
Semiconductor fabrication: Ovivo combined with ECL’s core water business creates a credible greenfield and retrofit go-to-market for fabs. Pilot projects are demonstrating water recycling improvement from 5% to 80%, with purity gains that lift chip yields. Greenfield fab wins would represent $100M+ contracts with multi-year annuity revenue.
Macro / Iran war: The cost picture is more manageable than the 2022 Ukraine shock — raw material basket inflation is running +9% versus 50%+ previously, with significantly less supply chain disruption. ECL has also restructured its surcharge mechanism to compress the time to margin neutrality from 18 months to 1–2 quarters.
Life sciences: Customer wins are driving near-term momentum. AI’s impact on ECL here is not yet direct, but an acceleration in drug discovery could benefit ECL through its higher exposure to commercialized products.
The stock has been a notable laggard among liquid cooling/thermal management names; shares are down YTD despite growing exposure to AI capex.
Source: Bloomberg
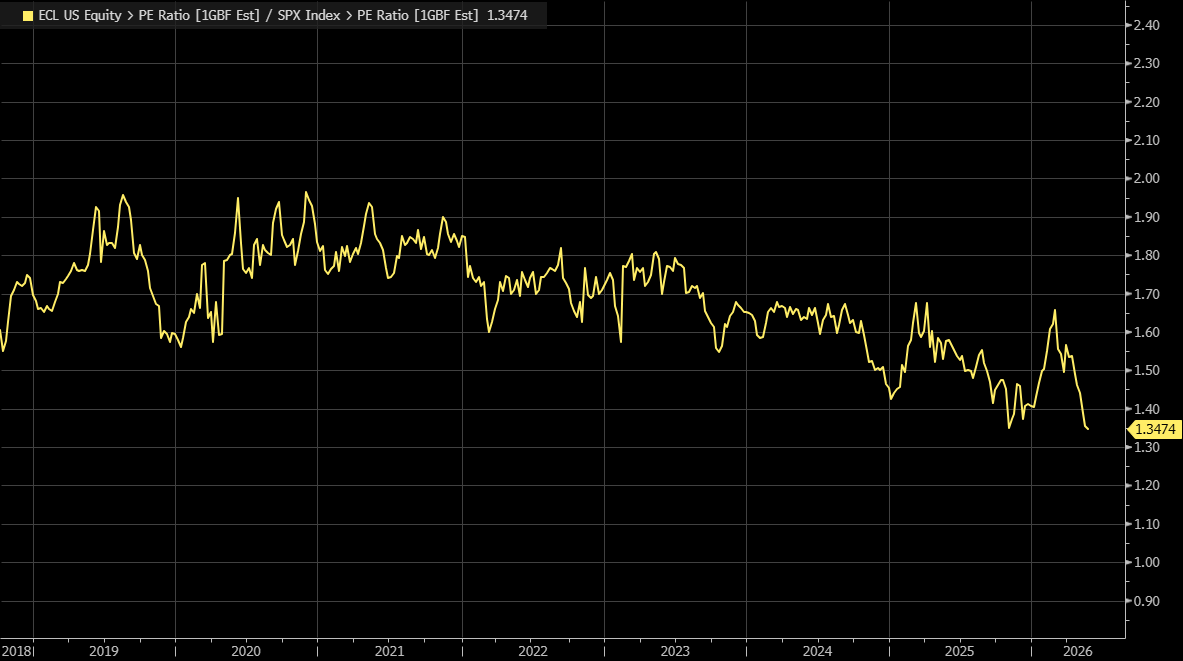
The relative P/E premium of ECL to the S&P has compressed to a 10-year low of 34%, reflecting the Iran War and resulting oil price increase overhang. The company has demonstrated confidence in managing cost inflation however macro headline relief from the opening of the Straits would be a positive.
Source: Bloomberg
In summary, while ECL is not currently recognized for its growing AI capex exposure, this is expected to change once CoolIT closes. The acquisition gives ECL sizable exposure to two market growth segments tied to AI; AI factories via liquid cooling and semiconductor fabrication via water management.
Please reach out if you’d like to discuss further.

