

The equity markets continued their historic rally last week, once again being led higher by the tech/AI/semiconductor trade. The nasdaq (QQQ) was up 5.5% for the week and is now up 28% since the lows hit on March 30th. The semiconductor names were the real stars as the SMH gained another 11%+ for the week and is now up 57.5% from that same March 30th low. While the momentum to the upside has been undeniable, there are signs that should make even the bullish of investors a bit concerned. Those semi names (SOXX Index) registered its highest RSI “overbought” reading since March 2000 (we all know what happened after that). In addition, $2.6 trillion of notional value in S&P 500 (SPX) call options traded on Friday, which was the highest amount ever traded (with 60% of all options trading being calls). Finally, net positioning in VIX futures by institutional asset managers has once again flipped to “negative”. Recall, it was this “complacency” in VIX positioning back in January that made me believe we could see both a decline in the indices as well as a push higher in volatility (here).
SMH up an incredible 57.5% in less than six weeks. The RSI (Relative Strength Index) hit “overbought” levels last seen in March 2000

Net VIX future positioning has once again flipped to negative. We saw large buying/covering thru March as markets sold off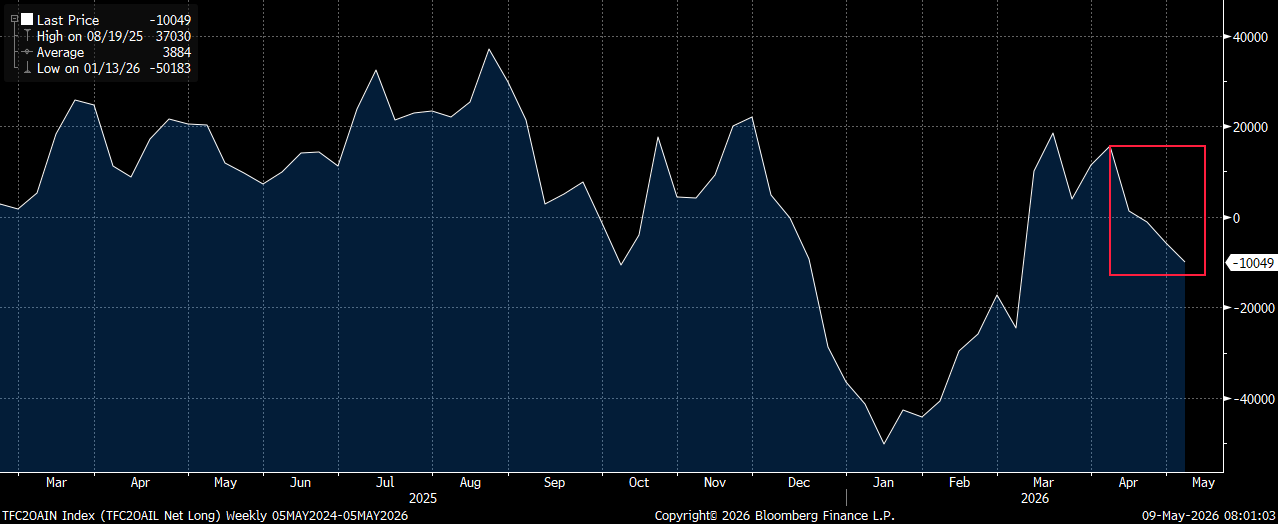
While it is impossible to stand in front of a momentum train like this, you can take measures to hedge against a possible reversal. Any market that can rally this much, this soon, is certainly capable of reversing lower out of nowhere (much like the upside “pivot” we saw at the end of March). While index hedges could absolutely be considered given the rally, and accompanying decline in volatility, I still believe VIX tail call spreads remain the most attractive way to hedge a long risk-asset portfolio at this time.
Back in mid-April I had suggested buying May VIX call spreads to hedge against a possible pullback in the markets (with an expected accompanying spike in volatility). While neither of those materialized, the May VIX call spread is STILL worth more than 50% of the initial cost, while any equivalent SPY/QQQ put hedge has likely lost more than 95% of its value. This is both a function of May VIX futures only declining by ~ 5% over that time, as well as the continued rally in the indexes moving the delta considerably lower on any puts that would have been purchased at that time.
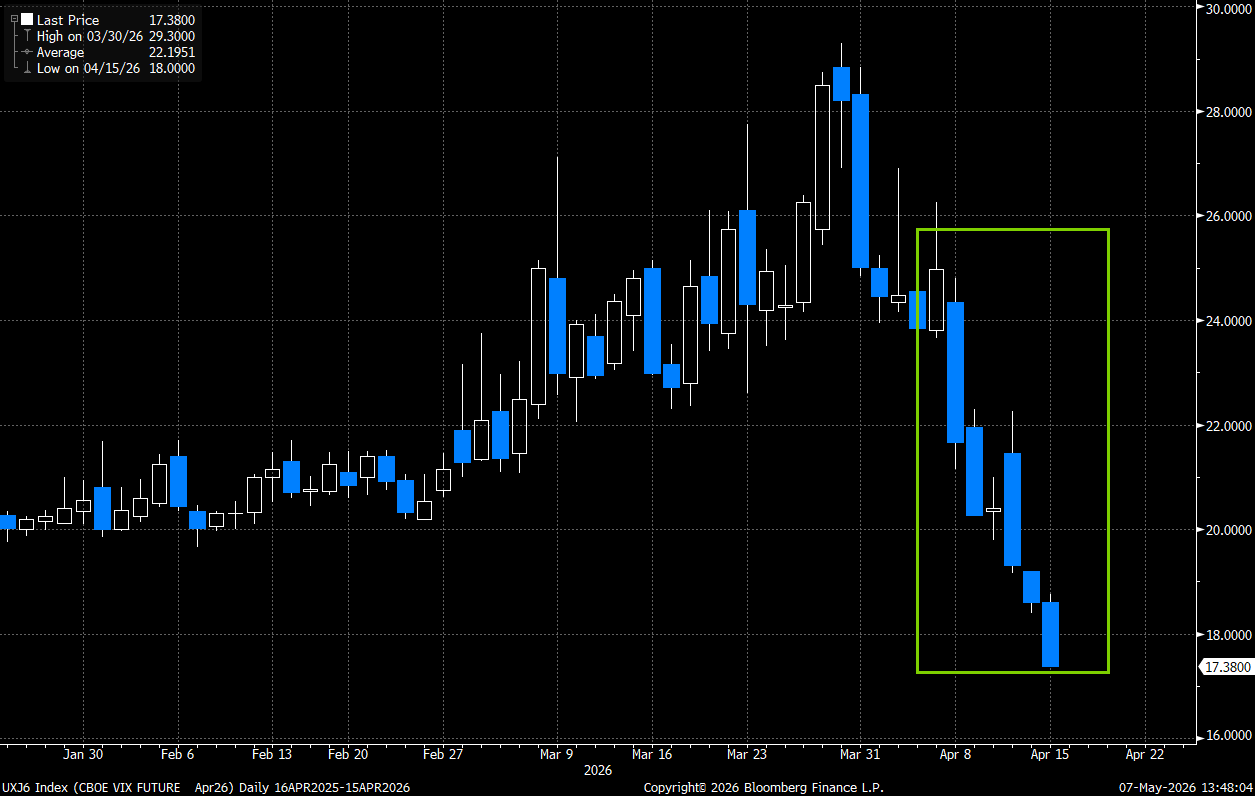
For anyone who did buy May VIX call spreads as a hedge, now is the time they must be rolled to June. Not only will the bulk of the decay (theta) be realized over the next week or so, but we have also seen a large bias for the front-month futures to “collapse” into expiration. We clearly saw that play out in April, when we saw the April futures decline from over 24 to below 18 in a matter of days. Therefore, I would strongly suggest to anyone who is still in a May VIX call or call spread to roll to a comparable June structure as soon as possible since the May futures expire on May 19th.
The April VIX futures did a nosedive into the April 15th expiration
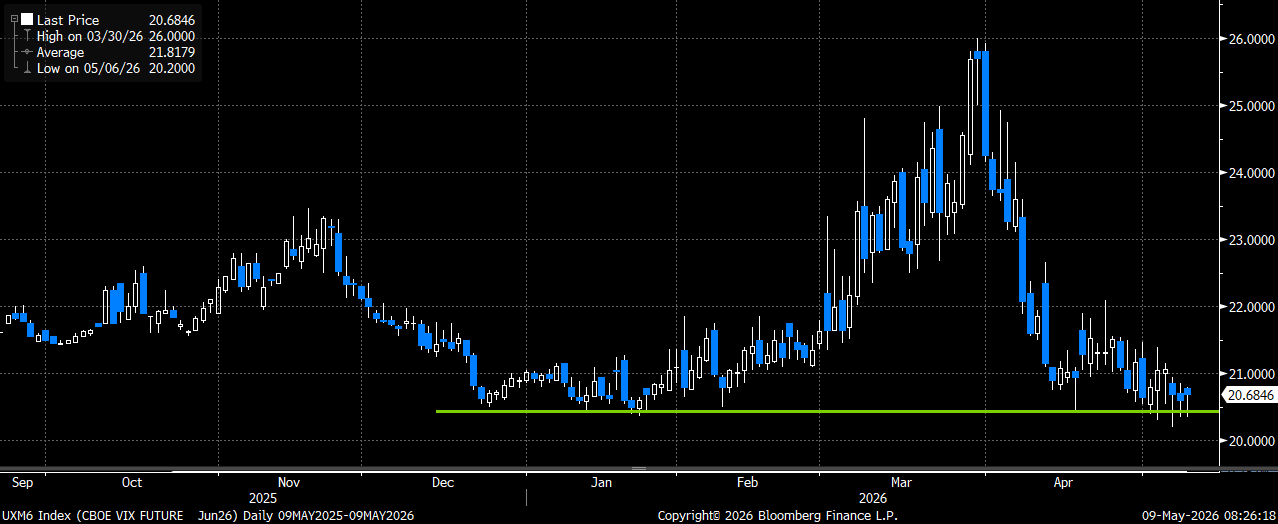
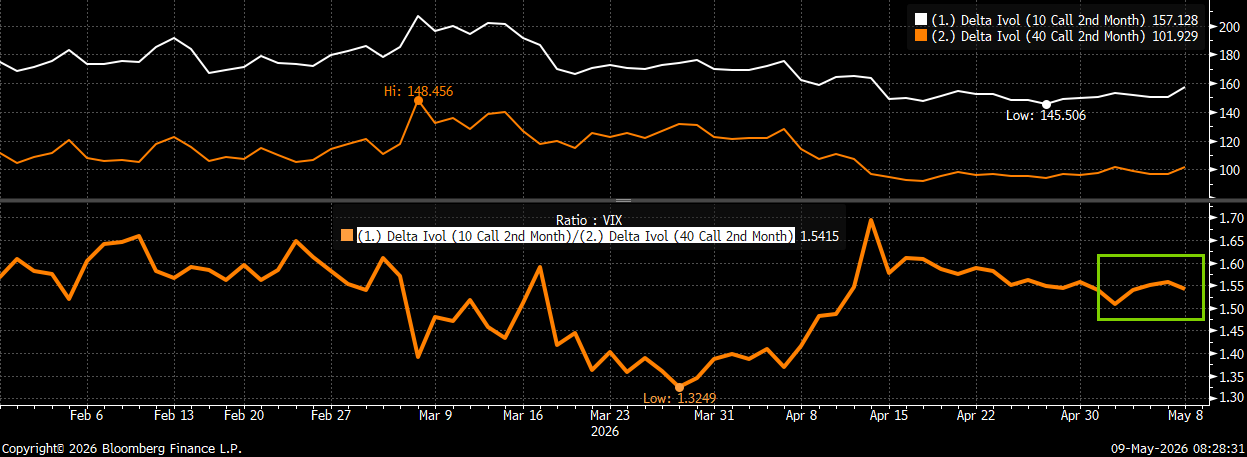
As far as a June VIX hedge, I favor adding low-cost/high-payout call spreads for mamy of the same reasons why I liked the May hedge. It seems that we are getting near a “floor” to vol again (as evidenced by the fact that May VIX futures are barely lower even as the markets continue to race higher). In fact, we saw spot vol HIGHER on Friday, even as QQQ gained over 2% and SPY was up nearly 1%. Have we reached the point where dealers are more concerned about making upside calls too cheap again? This wouldn’t be out of the question, especially given the notional amount of S&P calls that traded on Friday as well as the decided call vs put ratio. In addition, VIX call skew has continued to move higher off the March lows, which certainly favors owning a “wide” upside call spread.
June VIX futures have moved back down to support and continue to “hold” that level even as markets make new highs
VIX June 10d/40d call skew is up from the March lows and remains attractive
If either rolling an existing May VIX position, or looking to establish a new June VIX hedge, here is a trade I would consider owning now:
Buy VIX June 17th 25 calls
Sell VIX June 17th 45 calls
Costs ~ $1.05 (June VIX futures ref of 20.60)
Trade Details:
- Buying the 20-point wide June upside VIX call spread as a “cheap” macro tail hedge
- VIX hedges continue to perform much better than index hedges given “floor” to vol
- Signs of complacency include; very “overbought” levels on RSI, huge amount of upside call buying/chasing and VIX future positioning once again turning negative
- Spread offers an 18x to 1 max payoff and has more than five weeks of duration before the June 17th expiration
- Selling the 45 call covers nearly 30% of the cost of buying the 25 call (speaks to the attractive call skew I referenced)
- Attractive “overlay” trade to an existing long/bullish portfolio after a “historic” rally off the March lows
Please reach out to me or the 22V sales team for updated pricing and execution capabilities

