

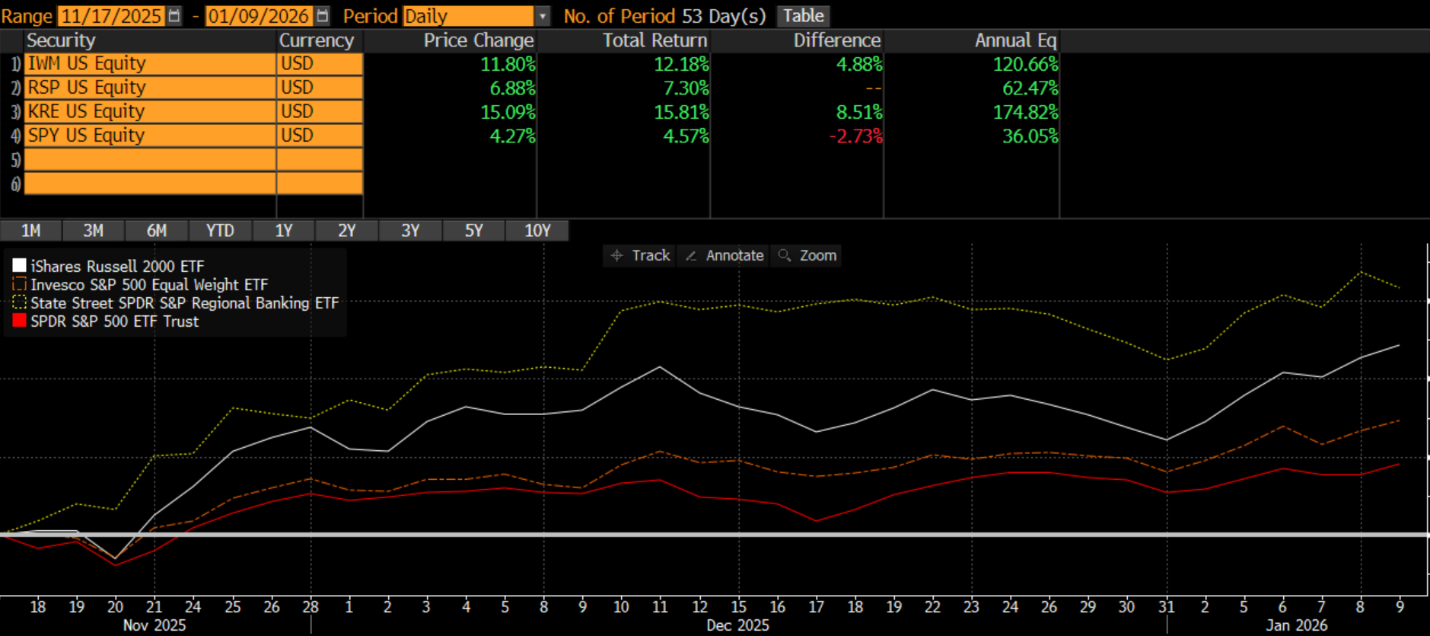
The equity markets had a very strong week to start the year with all the major indices firmly in the green. The broadening-out trade that we have been suggesting for some time at 22V continues to take hold, with small caps (IWM + 4.6%), regional banks (KRE + 3.43^%) and the equal-weighted index (RSP + 2.46%) far outpacing the 1.6% gain in the tech-heavy SPX. While I remain very constructive of the markets, especially on a continued broadening-out trade, I am seeing something regarding VIX that is a bit of a concern.
The broadening out trade that started in mid-November continued to work last week
Source: Bloomberg
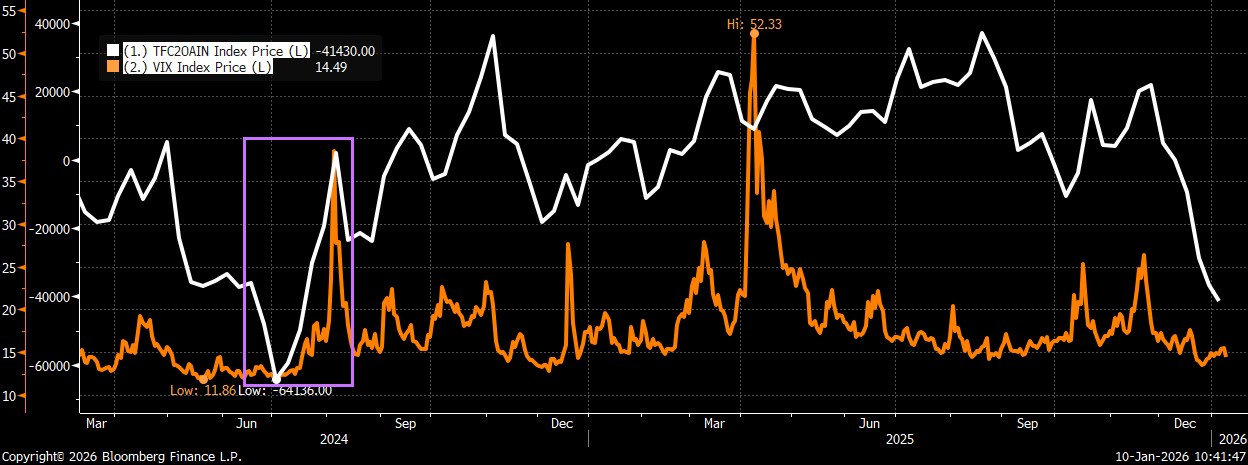
Not only is the VIX index back near the lows, but I am seeing a large increase in the net short positioning in the VIX futures from the Institutional Asset Managers. Net exposure has flipped from a high of ~ +40k contracts in August to a current -40k net contracts as of last week. Looking back over the last five years, the only time net exposure from this group was more negative (bullish bets) was in July of 2024 (when it got to -60k contracts). The VIX bottomed right around that time in July 2024, and spiked to nearly 40 the month after on a short-lived Japan carry trade scare. One would think that the large open-interest in the VIX futures at that time certainly led to some of the squeeze higher in VIX on that selloff. With VIX at the recent lows and net positioning getting “one-sided”, I do believe the pieces are once again in place to see another sharp spike in vol should something unexpected occur.
The net-short positioning in VIX futures from the Institutional Asset Managers should be a concern

The last time positioning was this one-sided (July ’24), we saw VIX spike to nearly 40 while investors scrambled to cover short VIX positions
Given the continued bullish action in the markets, as well as positive economic data and an accommodative Fed, I don’t believe index hedges are a must own at this time, but I do think that VIX “tail” hedges make a lot of sense. In other words, I am less concerned about a pullback in the indices at the current time, but I would definitely look at owning “cheap” tail hedges on vol (VIX) given this current backdrop. What I also continue to like about owning VIX calls (or wide call spreads) is that with both VIX and VVIX at/near their lows, the delta impact on the hedge becomes less as the market continues to rise. This means that owning Feb calls (call spreads) should carry better over the next month or so (especially if markets continue to make new highs).
Here are two VIX option trades I would suggest as “tail” hedges on volatility:
Trade #1 – Buy VIX Feb call spreads
Buy VIX Feb 18th 22/50 call spread for ~ $0.80 (VIX Feb futures ref of 17.87)
- Trade offers a 34x to 1 max payout on the limited-risk hedge
- Structure capture very attractive call skew (Buying 100 vol/selling 176 vol)
- Selling the 50 calls covers a full 25% of the cost of buying the “cheap” 22 calls
- Net short positioning by the Institutional crowd could lead to a sharp spike/squeeze in vol on any “surprise’ news or developments
- Wide spread between call strikes also will allow plenty of opportunity to monetize should we see a vol spike higher over the next six weeks
- VIX and VVIX both at/near their recent lows. Should see the calls hold their value (deltas) better even if markets continue higher
Trade #2 – Buy VIX Feb calls outright
Buy VIX Feb 18th 25 calls for ~ $0.82 (VIX Feb futures ref of 17.87)
- Buying the 22-delta Feb VIX calls outright as a “tail” hedge for the markets and vol
- Long calls outright will provide plenty of convexity should we see a meaningful move higher in vol (especially given net short positioning)
- VIX and VVIX both at/near their recent lows. Should see the calls hold their value (deltas) better even if markets continue higher
- Can look to roll calls out to March if we don’t get a sharp move higher in vol by end of Jan (to get ahead of the majority of the theta decay)
- Please contact me or the 22V sales team for updated pricing and execution on either trade

