Back China Strategy

China Sentiment: Overall Resilience to Iran Conflict, But Challenges for Equities

Published on April 6, 2026

∙ Download the PDF Report

By

Michael Hirson

Houze Song

SUMMARY

  • 22V’s China Economic Sentiment Series (CHESS) tool shows that domestic analysts expect China’s economy to remain resilient in the face of the Iran crisis; that said, expectations for exports and broader growth have lost momentum since January.
  • While the energy price shock is leading to increased expectations of reflation in China, it is a double-edged sword: sentiment towards the equity market has declined, as analysts see near-term risks of reduced monetary policy easing globally as well as in China.
  • Household demand is a mixed picture: there has been a modest pickup in analyst sentiment towards the property sector, but consumption expectations have dipped.
  • Our Take: Downside risks for China’s economy are limited, but fading fiscal stimulus means that the macro backdrop will remain subdued even if the conflict ends soon.

This report updates the sentiment signals from our proprietary China Economic Sentiment Series (CHESS) tool, which we relaunched in February (link HERE). CHESS uses LLMs to assess the sentiment of Chinese economists and analysts commenting through opinion pieces and brokerage reports.

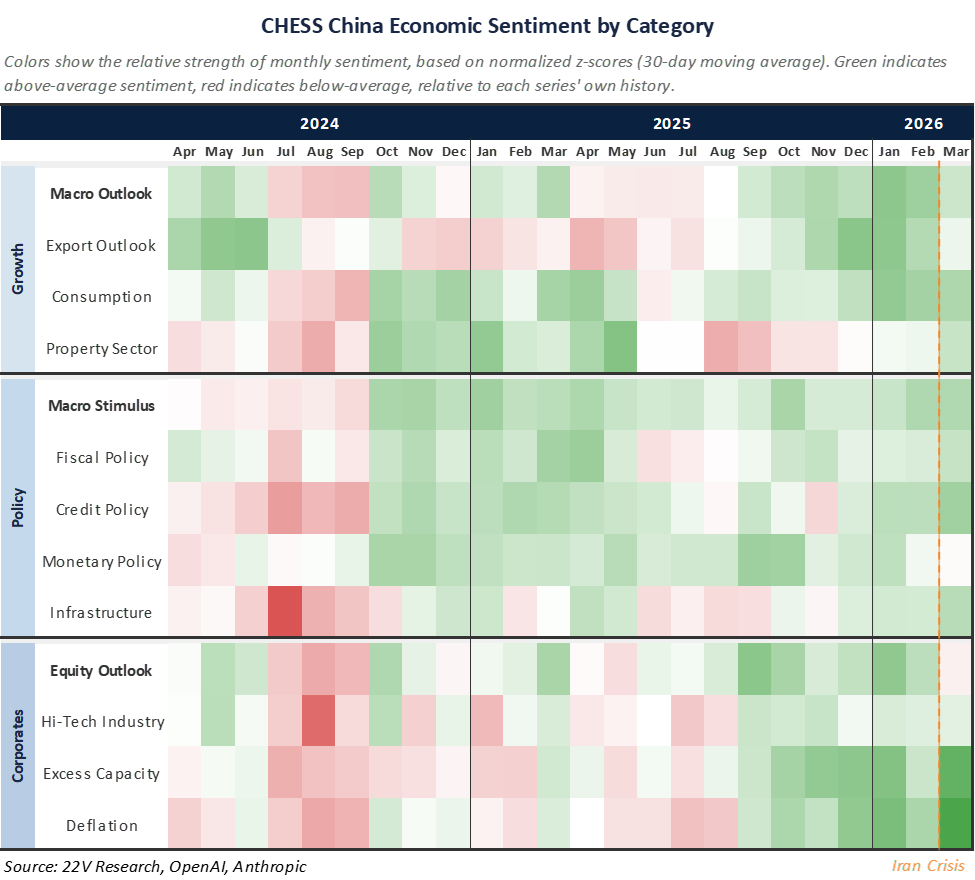
This update focuses on how the Iran conflict is impacting sentiment among influential economists commenting in public opinion pieces. The overall picture is one of economic resilience: As the below heatmap shows, sentiment has been quite steady since the Iran crisis erupted on February 28. This should not be a surprise: we have also argued that China is comparatively well-placed to weather the energy price shock (link HERE) given high inventories of crude, a diversified energy mix (due in particular to coal and renewables), and a macro environment of deflation and industrial excess capacity.

However, China’s economy and markets are not immune to the global ripple effects of the crisis, which is dragging on sentiment towards Chinese equities, monetary policy expectations, and exports. Key charts and takeaways further below.
Slowing momentum for exports and broader growth

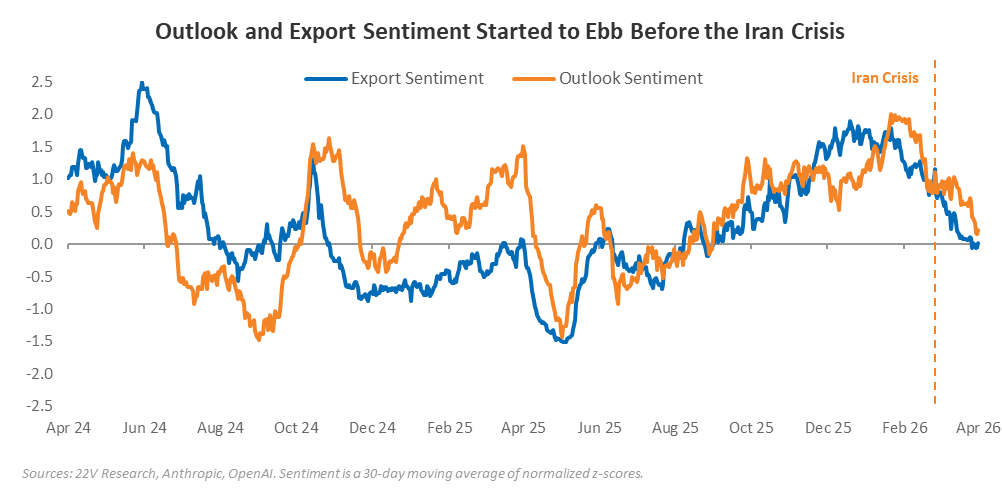
China’s export performance has been very strong in recent months, including 21.8% y/y growth in January-February. However, sentiment towards the export outlook has been fading since late January, indicating that even before the onset of the Iran crisis, economists had expected momentum to slow. Export sentiment has slipped further since the conflict erupted; emerging economies, a relative bright spot for China’s exports in the last year, will likely be hit particularly hard.

Given that exports have been a key source of support for China’s growth amid weak domestic demand, it is not a surprise that sentiment towards the macro outlook (blue line) has also dipped. Sentiment towards the near-term growth outlook now stands at neutral.
A graph of blue and orange lines

AI-generated content may be incorrect.

Reflation comes with risks for equities

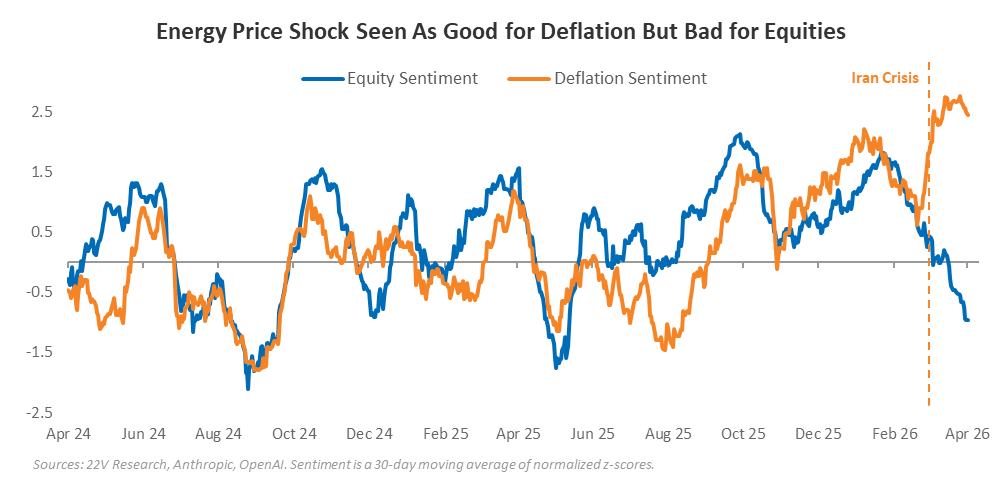
One potential upside of the energy price shock is the potential for it to lessen China’s deflationary pressures. Analyst expectations for escaping deflation (orange line) have improved since the launch of the “anti-involution” campaign in mid-2025 and taken another sharp turn up since the start of the conflict.

Analyst sentiment towards the equity market outlook (blue line) had largely tracked deflation until recently, on the assumption that the end of deflation would boost corporate earnings growth. The energy shock has scrambled that logic, with analyst reports citing the potential for tightened monetary policies and risk aversion (globally as well as China) as near-term headwinds.
Mixed expectations for the household sector

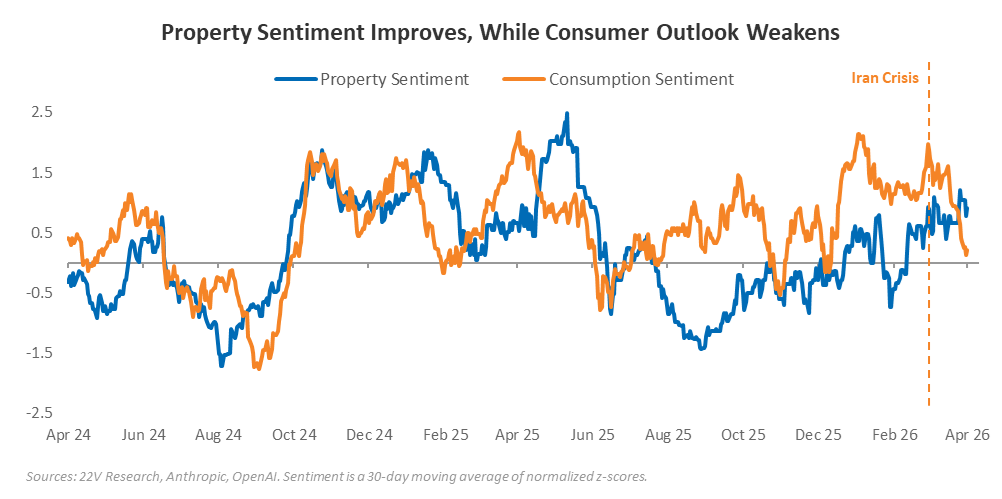
What are the prospects for China’s domestic demand to offset potential weakness from exports? The positive news is that sentiment towards the property sector (blue line) has ticked up in recent months and is at its most positive level since the summer. However, there are two caveats. First, our in-house view is that property prices and activity show few signs of bottoming out any time soon; this improvement in sentiment could be short-lived, as has been the case for other episodes over the last several years.

Second, analyst expectations for consumption (orange line) have fallen since early March. This likely reflects the lack of major consumption-focused stimulus announced during the National People’s Congress (March 5), as well as concerns that the Iran conflict and its impact on energy prices could weigh on household economic confidence.
Bottom-line

Our in-house view of China’s outlook is not radically different from those of CHESS. Downside risks to China’s growth are modest unless the Iran conflict should dramatically worsen or last into the summer. Even apart from the Iran conflict, however, we continue to expect growth to slow sequentially in Q2 due to fading fiscal stimulus (see our latest take HERE). A short-lived crisis should lift some of the inflation-related concerns dragging on Chinese equities, but we expect the overall macro backdrop to remain subdued.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.