

Early, if Cautious, Macro Optimism from Earnings Season
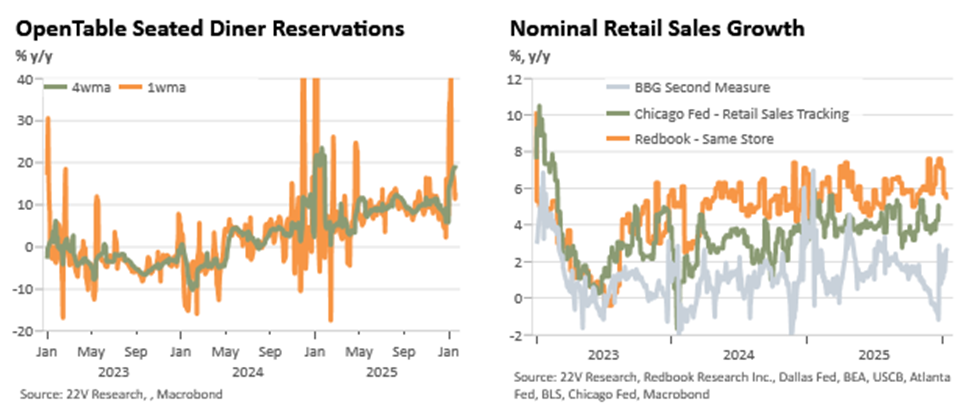
- Consumer spending trends continue to look strong from the big banks (+7% y/y at JPM, down from +9% in Q3; +6% at BAC, up from 5%; +6.2% at WFC, from 6.3%; and +5% at C, up from 4%). This is being led higher income consumers and is experience centric.
- Consumer credit trends continue to be steady or improving, with solid expectations for 2026.
- Earnings calls generally contained a bit less macro and bit more bottoms-up discussion than in recent quarters, itself a useful signal about perceptions of endogenous recessionary risks fading.
- Geopolitical concerns seem the tail risk most top of mind for business leaders.
- Financials and consumer services names generally sounded more optimistic than those more exposed to manufacturing and tariffs. Delta and United airlines highlighted the k-shaped economy narrative fairly clearly. Costco same store sales (adjusted for FX and gas) in the US accelerated slightly in December to 6.3% from their 5.9% in the prior fiscal quarter (ended 11/23/25). JB Hunt noted a more optimistic end of the year for their customers, while 3M and Fastenal seemed to be planning on a further sluggish 2026.
- Private final domestic demand growth is tracking around 3% in Q4, after similar paces in Q2-Q3. None of this is suggestive of looming recessionary pressures or an economy which, in aggregate, shows an obvious need for further policy stimulus. We are about to get some from the OBBB (adding roughly +50bps saar, with some upside risk, to each of the next two quarters) and the Fed is still expected to ease a bit more over the course of the year.
Consumer Spending
There was actually surprisingly little discussion across the recent earnings calls of topline consumer spending trends and health. This absence is itself a bit of a tell as the calls were generally much more bottoms-up business discussion centric than full of cyclical worries (boring for me perhaps but a good sign about analyst and market concerns moving more micro from macro).
- “Across income groups, debit and credit sales volume continued to perform well, up 7% year-on-year.” – JPM
- “It was a pretty good, decent environment as we moved through year 2025. Consumer spending grew 5% to – at $4.5 trillion, grew 5% over the 2024 levels. Account balances in the consumer business for that broad base of the US consumer were stable through the year.” – BAC
- “It has to be some exogenous variable because the base economy, I just don’t see big cracks that are going to be realized in 2026… But the basic business of running the bank against the economy with customer demand and the health of the consumer, we have a lot of tailwinds this year, and it should be a great year for banks.” – PNC
- “2025 grew, I think it’s 8% it grew, but it was mostly on fare. And right now, we’re seeing both fare and traffic. And so, seeing that traffic come back is, I think, a really good, good start to 2026.” – DAL
- “Based on what we’ve seen so far this year, bookings and yields are outpacing the strong start from last year and we’re hopeful that the momentum will continue, which could admittedly cause our guidance to feel a bit conservative.” – UAL
- “Our customers, we talked to them about their 2026 planning really leading into this year. And I think you’re right on the money with their optimism about really the potential continued strength of the consumer. I think if you look back at any data from November and December, our macro data reporting as well as retail sales, they had a solid year end finish.” – JBHT
- “I would just characterize it as being relatively soft, like bumping around flattish as we ended the fourth quarter.” – MMM
Housing Remains a Soft Spot
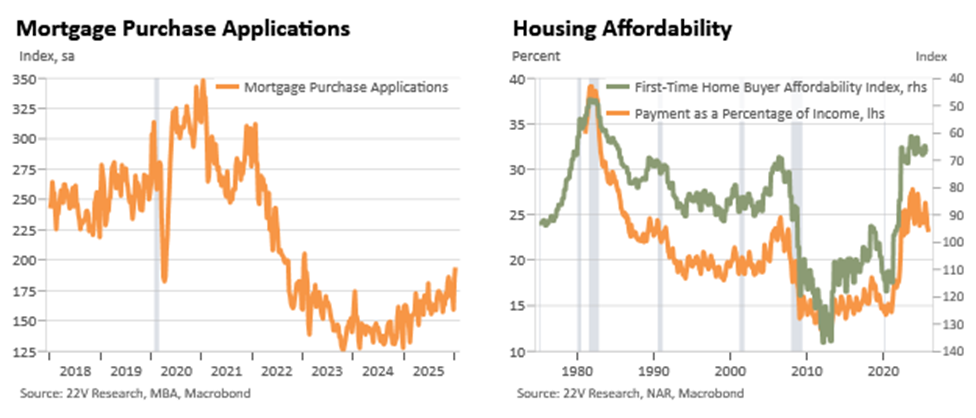
While overall consumer spending continues to hum along, led by higher-end consumption of services, the housing market continues to gradually muddle through. While the macro data suggests things have not gotten appreciably worse and may be seeing some very early green shoots, transaction volumes remain sluggish due to affordability issues and demand pull-forward.
- “We increased our sales incentives during the first quarter, and we expect incentives to remain elevated in fiscal 2026, with a level dependent on demand, changes in mortgage interest rates, and overall market conditions. ” – DRHI
- “When we see those kind of rates, moves in rates, and hovering right around 6%, it does spur some activity in our sales offices.” – DRHI
- “The consumer [lending] piece had been quieter last year, maybe picked up a little more this year, we can see the growth now in a variety of categories. Interesting to see home equity beginning to grow in variety and across time.” – BAC
- “I did actually hear that it was a pretty busy day in the home lending business on the back of what happened in the mortgage market [following news of GSE MBS purchases]. So, maybe we’ll actually start to see some pick up there. But obviously, there are still some larger dynamics in the housing market that will be a challenge there.” – JPM
- “Overall, final mile end market demand remains soft across furniture, exercise equipment and appliances.” – JBHT
Credit Trends
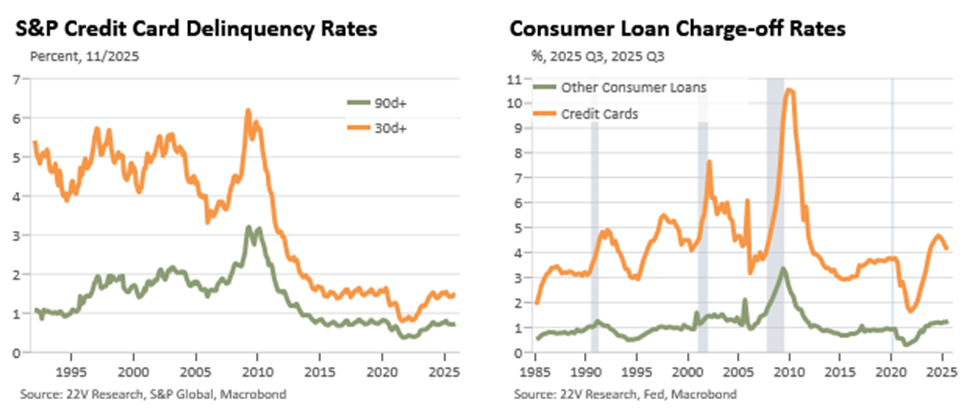
The relative absence of discussions of consumer credit trends was itself a bit of a tell on what is best broadly described as a normalization in credit after the min-credit cycle of 2022-24.
- “Consumers and small businesses remain resilient. We continue to monitor leading indicators for any signs of stress. And despite weak consumer sentiment, trends in our data are largely consistent with historical norms, and we are not currently seeing deterioration.” – JPM
- “We expect the 2026 Card net charge-off rate to be approximately 3.4% [was 3.3% across 2025] on favorable delinquency trends driven by the continued resilience of the consumer.” – JPM
- “Consumer net charge-offs improved again on a year-over-year basis, and we continue to see stability in asset quality metrics.” – BAC
- “We closely monitor our portfolios for signs of weakness, and consumers continue to be resilient as income growth has generally kept pace with increases in inflation and debt levels. Our non-performing asset ratio declined modestly from a year ago,” – WFC
- “Across our US cards portfolios, delinquency and NCL rates continue to perform in line with our expectations.” – C
- “The basic business of running the bank against the economy with customer demand and the health of the consumer, we have a lot of tailwinds this year, and it should be a great year for banks.” – PNC
- “The overall consumer portfolio remains healthy, with non-accrual and over-90 delinquency rates stable to improving across all loan categories.” – FITB
Business Sentiment is Haltingly Rebounding
2025 was supposed to be a year of deregulatory and fiscal-led reacceleration, instead it was year 3 of corporate caution paired with a modest easing in labor markets due to tariffs and surging policy uncertainty. Moving past these overhangs is one of our key themes for the year (see my 2026 preview) which will allow greater confidence in forward-looking decisions, such as hiring and investment, as firms adjust to higher baseline levels of volatility, some of the most acute impacts fade, and the administration (hopefully) slows some of its more aggressive moves. How much optimism firms’ feel about 2026 largely ties into the proximity to high-end consumer, capital markets, or AI spending.
- “[An early optimistic take on 2025] got derailed a little bit. So I think the new year offers optimism for a different outlook than we were a year ago. I think relative to the administration and their priorities, I think — we’re all one year smarter and more conditioned to expect maybe the unexpected in some of the policy approach.” – DAL
- “Business travel is showing signs of improvement as corporate confidence grows.” – DAL
- “Business volumes have gotten off and are just really compelling… This year, for the same early January week, business revenue is up high-single-digits and nearly 20% year over two.” – UAL
- “Capital markets are kicking in with well-capitalized corporates and higher-end consumers driving the economy forward.” – MS
- “Over the next few years, barring some sort of an exogenous event that slows it down, we’re going to have a pretty constructive environment for those activities given the combination of fiscal, monetary, capital investment, deregulatory stimulus. You’ve got this combination of stimulus activity that I think is pretty constructive for these businesses.” – GS
- “{C&I lending] does give you some indication of the level of client engagement and optimism maybe in C-suites… is a combination of generally optimistic outlook for, frankly, the global corporate environment.” – JPM
- “When you go to our corporate commercial customers, again, as the tax laws settled in, the tariffs appeared to be manageable and deregulation kicked in, they had a pretty good year and good profits, including good credit quality and good money movement activity as we moved through the year as they participate in the world economy.” – BAC
- “While the labor market in the US has softened, capital investment remains strong, especially in tech. And it’s the combination of that CapEx, the health of the consumer, the tax bill benefit from anticipated rate cuts that should be enough to sustain growth.” – C
- “We have seen a nice increase in pipeline activity quarter-over-quarter, year-over-year, and we believe that’s a catalyst for growth. We’re beginning to see customers use some of their excess liquidity, which we think is also a precursor, obviously, to borrowing and increased line utilization.” – RF
- “We’re planning for the macro to be similar to 2025, but it’s still early to put too much weight on market forecasts. We expect most of our industrial businesses to continue to perform well in ’26 with watch items, including the pace and timing of a US consumer recovery, auto build rates, especially in geographies where we have higher content and consumer electronics.” – MMM
- “I don’t think we’re seeing anything one direction or another. You’re hearing some optimism from us probably because we internally beat ourselves up so much in ’23 and ’24 as we were struggling that it feels good to be achieving success and frankly, it feels good to be paying bonuses to our employees again.” – FAST

