Back Economic Research

Consumption Speeds Along, Faster than the Vibes

Published on December 16, 2025

∙ Download the PDF Report

By

Peter Williams

Consumption Speeds Along, Faster than the Vibes

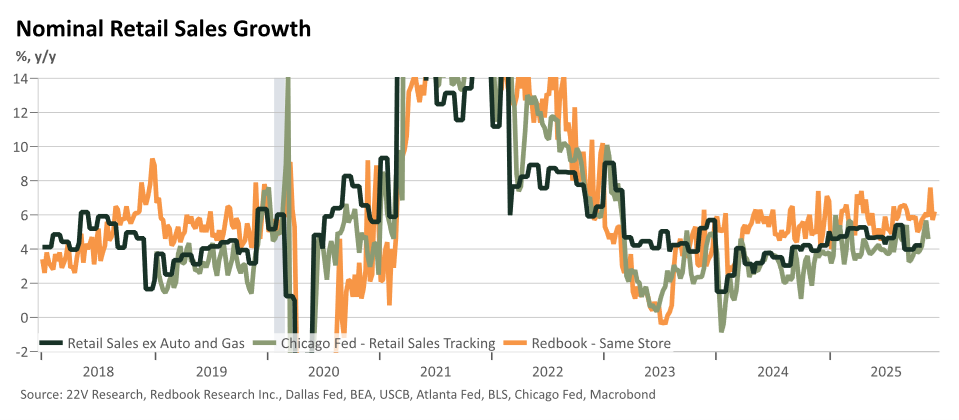
  • Nominal consumer spending continues to motor along, despite the tremendous volatility buffeting consumer sentiment and monthly spending, with topline trends that remain remarkably steady.
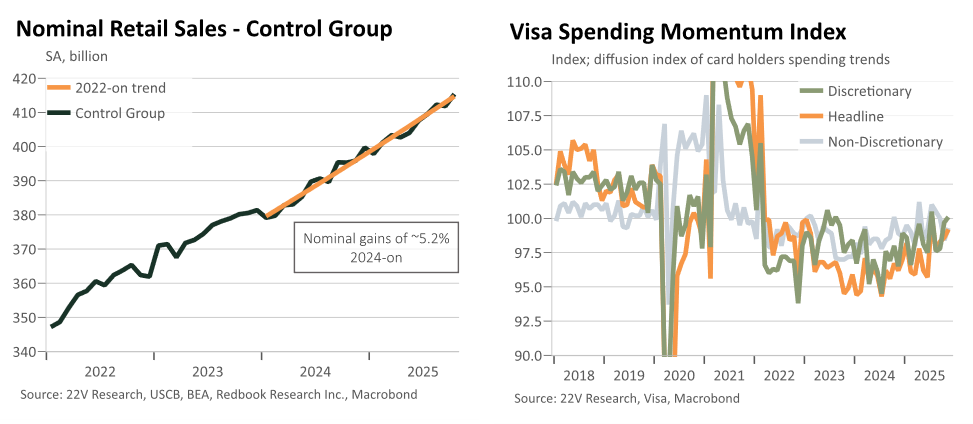
  • October retail sales data was quite strong on an underlying basis, following a softer September that saw payback from July-Aug heat. Nominal control group retail sales are running at roughly 5.2% pace since the start of 2024 and current spending continues to bounce right around that trend level.
  • Inflation is weighing on real volumes some, but this will be largely transitory. Eventually falling core goods inflation will allow for better composition of spend and increasing volumes with nominal fairly steady. My analytical framework has shifted to focusing on a nominal – inflation = real as an approach, rather than an bottoms up real + inflation = nominal one. This is because nominal trends have been quite steady and inflation very volatile this cycle, leading to too much cyclical noise when reasoning from short-term real spending trends.
  • While holiday timing shifts, the shutdown, and tariff newsflow have led to some volatility. Rebook same store sales continue to bounce around their ~6% pace with the occasional dip. This matches the broad trends from the banking and card spending data, discussed below.
Recent Corporate Comments are Consistent with this Story

  • The sequential acceleration in spend flagged by the banks from Q2-Q3 lines up with the hit then stabilization of private sector hiring in the NFP data and our read of the underlying signal from ADP as well.
  • During Costco’s earning call they summed the environment up quite well: “there’s a lot of consistency actually… When you look at month by month, there’s definitely been some lumpiness in the individual monthly sales results that we’ve posted. A lot of that has been to do with whether it was uncertainty around tariffs one month to another or port strikes that we had to cycle… If you look at every individual month, there was only two months in that last seven months that were outside of the range of 6% to 7%.”
  • Bank conference season largely supported this view as well (see ‘A Macroeconomist Goes to Earnings Season’). K-shaped discussions remain a theme though although the popular rhetoric on this seems to overstate underlying reality.
  • V (“holiday season, which, again, is stable and strong”) and MA (“there’s sort of a divergence, I think, between the soft and the hard data… But what we see in the hard data continues to be very supportive of consistent spend”) both highlighted continued aggregate spending stability, echoing broader theme.
  • BAC saw spending decelerate a small amount in recent months, but said “I wouldn’t overly read into a 0.5% movement… So consumers are in good shape.” They see some evidence for the k-shaped economy but “not as much as people think.” MA see’s “healthy spending metrics across both mass and affluent segments in our portfolio.” Visa’s measure of consumer spending breadth has bounced this year.
  • The strength of spending reported by AXP (around Thanksgiving it was +9% overall and +13% for platinum card customers) and JPM (“spend in the 4th quarter improved a little year on year and relative to the first three quarters of the year… [was +9% in Q3] Yes, there is a divergence in spend growth between higher-income customers and lower-income customers. But that relative level of spend growth is a sort of relatively normal trend”) highlighted the top-end strength rather than bottom-end weakness.
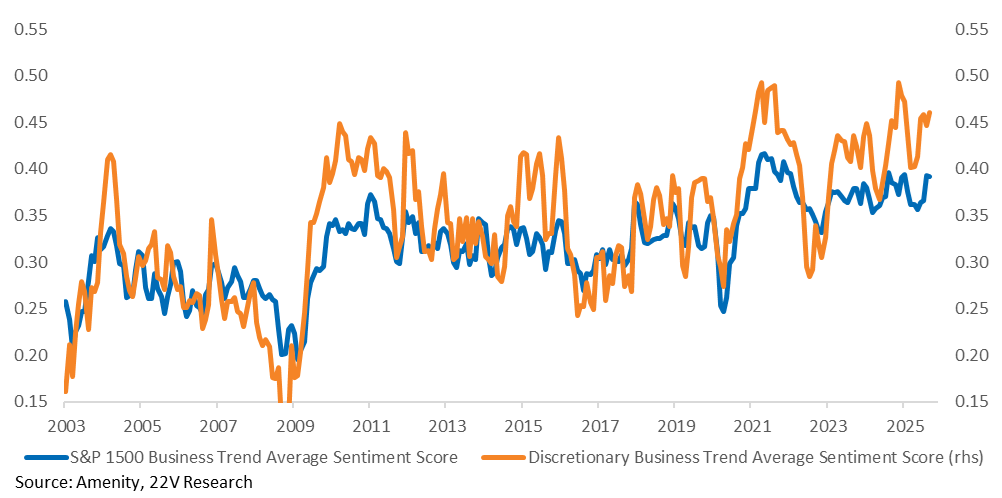
  • On the more mass-market side, DLTR flagged its first positive y/y comp for discretionary spending since 2022Q1. They also noted growth twice as fast for lower income cohorts than high. Beats and raise were common themes throughout earnings seasonal for retailers with some posting their first positive SSS comps in years. Our measure of sentiment for the discretionary consumer sector has almost never been better.
  • BAC noted that “small businesses are fine.” JPM echoed the sentiment noting that small businesses are “keeping themselves in pretty good shape so far,” despite tariffs.
  • Tariffs are fading as a drag on activity. BAC’s Moynihan noted that business leaders and economic forecasts have done a roundtrip thanks to tariffs, “I think the certainty, the path forward from six months ago to now is higher because trade and tariff has largely worked through the system in terms of people’s understanding of what will happen.” We think the uncertainty and cashflow drags from the myriad tariff shocks this year remain and underappreciated part of how 2025 has gone and this fading risk is a key tailwind for next year.
Discretionary vs Overall Business Trends Sentiment

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.