

A Macroeconomist Goes to Earnings Season
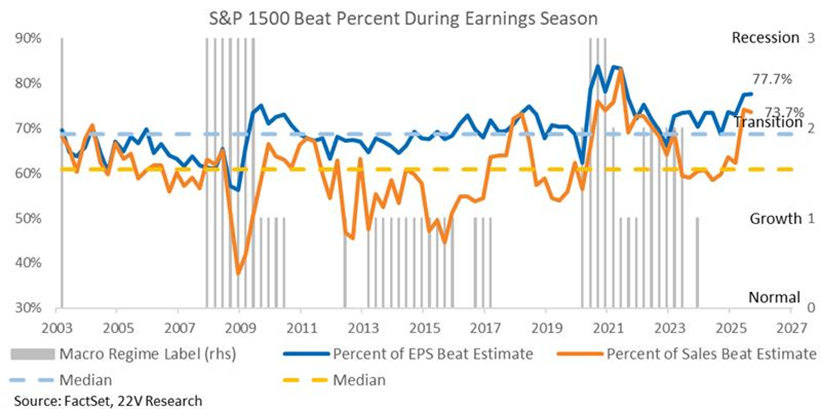
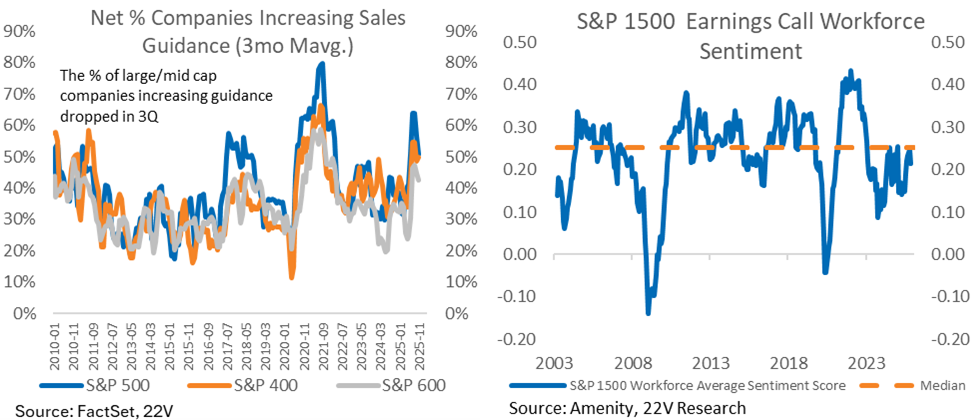
- Earnings season has had a few notable busts and few moments of real concern, but the overall trend has been one of solid beat rates, solid margin and workforce sentiment, and better than normal sales guidance.
- While some names young and lower-income consumer centric names have pointed to a weakening from September-on, that does not seem to be the case in the topline data from the banks or card providers.
- Travel-related names have had a strong showing overall and continue to point to substantial strength from higher-end consumers and in overall consumption.
- There have been some tentative signs of improvement in the industrial and consumer good spaces where sentiment seems to be following the PMIs in finding a bottom.
- These crosscurrents stem from a combination of: firm’s and households only gradually regaining a bit of certainty as tariff outcomes are more known, even as tariff’s direct hits are still building; deportations and immigrant movement restrictions are weighing on demand for consumer staples; and low labor churn weighing on job searcher sentiment and income levels, particularly for younger workers.
Tying the Consumer + Topline Stories Together
It is important to keep the topline trends we know in mind. Jobless claims paint a benign picture of layoffs (so far). Nominal spending is running strong, perhaps a bit too strong to be sustainable, in aggregate. The banks sound benign on credit trends and may be tentatively starting to starting to ease credit conditions again (more here). Financial conditions are easy overall and fiscal stimulus looks primed to be a modest boost to growth in ‘26H1. Potential IEEPA tariff refunds would be another modest tailwind. But there are substantial dislocations under the hood, some due to new policies this year and other as much a result of the post-pandemic whipsaws still being worked out.
The overall tariff impacts from actual price shifts, disruptions, and uncertainty are peaking roughly now. Some drag from both the uncertainty around new policies and the inefficiencies of the policies themselves will remain over the forecast horizon, a long slow fade off a wild peak this year. If the IEEPA tariffs are upheld, we likely get another push higher in core goods inflation in H1. Given that goods spending has seemed to be solid to slightly higher recently (maybe tariff front-running or just resuming a more natural place after years in the doldrums) and overall spending surprising steady and fast, this implies that services spend likely gets hit a bit. In particular, the strength of higher end services spend suggests that smaller ticket items are likely bearing the brunt although weakness in F&B and similar has not been universal and is not particularly apparent in the topline data.
Labor supply growth via increased immigration restrictions, along with inevitable domestic demographic aging, has slowed dramatically. The direct supply impact cushions slack measures given such low labor demand growth, while the shadow restriction in immigrant activity and mobility hits their consumption patterns, likely more than the direct impacts. Given that staples are a larger share of spending the farther one goes down the income stack, this seems consistent with a number of soft recent reports from staples cos.
Labor churn is depressed, so times remain tough for job searchers and plenty of young workers are likely underemployed. This is the same cohort getting hit by student loans + credit issues from the income and FICO score flattery of 2020-22. For those employed or switched jobs wage growth remains solid (though Oct ADP steady at 4.5% for job stayers and 6.5-7% for job switchers this year; Atl Fed median wage growth has been bouncing around 4-4.5% this year). Unsurprisingly, labor market weakness is hit most in these cohorts and the lack of job churn probably hits all workers to some extent as they can feel their outside options reduced.
Softening in the Younger Consumer and Layoff News Set an Unhappy Early Tone
While bank earnings season started things off on an optimistic note (here), the subsequent round of earnings season was fairly pessimistic with plenty of layoff announcements pilling up (they are highly seasonal in Q4)[1]. The main theme was not overall weakness but a sharply k-shaped economy which hits some firms and consumer hard while leaving others in a solid position.
- “Very stable, consistent [overall]… the lower end wage earner has definitely been it’s been struggling, you know, for a while. That’s not changing. It’s not getting worse, though.” – WFC
- AMZN and UPS’s large scale layoff announcements fairly early in earnings season dampened the improving tone heard prior to them during bank earnings. In listening to both of these announcements, the tone was less of concern with end-user demand and more the challenges of extremely rapid post-pandemic growth and then the collapse in job churn which followed leaving them somewhat overstaffed in a more lower, lower churn world.
- The urban yuppie seemed to have a rough quarter with CMG (“as consumer sentiment declined sharply, we saw a broad-based pullback in frequency across all income cohorts. Since then, the gap has widened, with low to middle income guests further reducing frequency”) and SWG (“in August, we saw a step down… and then we saw another step down in September… October is holding flat to September… the 25 to 35 consumer is the most under pressure”) both getting hit sharply.
- “In the U.S., we continue to see a bifurcated consumer base with QSR traffic from lower-income consumers declining nearly double digits in the third quarter, a trend that’s persisted for nearly two years. In contrast, QSR traffic growth among higher-income consumers remains strong, increasing nearly double digits in the quarter.” – MCD
But Banks are Seeing Strength, Not Broad Deterioration
With a large bank conference and BAC investor day last week we got helpful updates on some of the best data we get with the government closed (more from Bill Hebel here). There were no appreciable changes in any of the bank’s descriptions of the consumer environment since earnings as they continued to note that spending trends through all of October remained strong and delinquencies are stable to improving, often seasoning better than expected. This stands in contrast to some of the results mentioned above.
- “We’ve seen strengthening, both in confidence and that reflected in a little bit of strengthening in spend into the third quarter. And that does continue.” – JPM
- “Spending for those consumers was up 6% versus last October. Employment remains steady. We can see that in the paychecks coming into our consumer accounts.” – BAC
- “Our subprime cohorts are performing better than our expectations… what we’re talking about today in terms of a subprime consumer, struggling with inflation in a shaky employment picture, this is not new.” – ALLY
- “Consumers remain generally healthy and resilient, and we do not yet see any material deterioration in their position, whether you’re looking at sort of cash buffers as a key metric you’re looking at or whether you’re looking at delinquency trends, et cetera, and certainly spend.” – JPM
- “You look at credit card payment rates, they’re still higher than what we would have modeled at this point. Delinquencies are better than what we would have modeled.” – WFC
Big Ticket Services Remain a Bright Spot
Travel companies were a distinct bright spot in the quarter with a number of the platforms, airlines, and hotel companies all flagging distinctly positive trends. TSA data has continued to show steady modest growth even through the shutdown and Opentable’s seating numbers are steadily growing. The difference here between a number of the fast casual spots and other lower-end consumer focused names (although we haven’t heard from many of the mass market retailers yet) suggests that the K-shaped narrative is not just a lower-end weakness one but also a sign of outright strength for much of the higher-income and older consumer.
- “We’re still early into the fourth quarter, but we continue to see those trends in the fourth quarter as well. And when you unpack that, it’s really also in discretionary categories, so whether it’s retail or travel and dining.” – JPM
- “The market was healthy in the quarter with an acceleration in the U.S., and continued strength in the rest of the world… Based on our results to date and ongoing trends, we’re raising our full-year guidance” – EXPE
- “I’m not sure what other proof is required. We’re seeing it in all of our numbers.” – H
- “There is still some turbulence in the macro and in the tariffs out there. But you look at these fundamentals, you’ve got to feel pretty optimistic about the… U.S.” – IHG
- “As we start the fourth quarter, we’re encouraged by the continued momentum… we’re seeing strength in longer lead-time booking.” – ABNB
- “The positive momentum is continuing. Since July, travel demand has strengthened, led by a rebound in business travel, which was up high single digits in the quarter.” – DAL
- “If today’s environment projects into ’26, I think ’26 is going to be a really strong year.” – DAL
- “We’ve seen improvement in the main cabin since its low point in July. That momentum has continued into October, and we’re encouraged by the bookings we have taken for November and December.” – AAL
Industrials and the PMIs Might Be Flagging a Bottom in the Goods Economy?
Late last year the manufacturing PMIs started to rebound. After 2y in the doldrums this was a welcome sign, but tariffs cut that nascent recover short although recent month’s data point to a gradual recovery starting to emerge.
- “We did see higher orders due to capacity expansion in the US this year than last year, and we expect to see higher orders from that activity in fiscal year 2026. The demand, particularly for the product side of the business, which is still more than half of our business, is good.” ROK
- “We’re seeing the gradual Industrial recovery playing out with Industrial organic growth now positive… we’re definitely seeing the impact of slightly stronger volume.” PH
- FAST highlighted that tariff related uncertainty has been a real drag, “customers are doing what they need to do, but they aren’t necessarily doing more than they need to do because they aren’t building for the future because they’re not sure what their cost structure is going to be and if they want to do that thing”, and this has meant that “almost all of our customers are telling us the same thing that this year is what it is… and they’re really looking at that Q1, Q2 timeframe.”
- COST monthly sales data shows a broadly steady consumer in recent months. The pace of in-person sales growth is not blistering but has been steady around 6% y/y for much of the year, a similar pace as Redbook and other retail sales measures.
- The large shipping companies have painted a less dire picture of the overall consume. In quarterly earnings a few weeks ago UPS noted that their key customers “are planning for a good peak that will result in a considerable surge”; in comments today, Fedex raised guidance and noted that customer “demand is consistent with what they’ve been telling us historically.” Not spectacular but not rolling over and good enough for some substantial pops in their stocks.
Seems notable that in Challenger’s quite poor October layoffs number, the numbers for macroeconomic or underlying demand reasons seemed in-line or below their YTD monthly paces while the spike in layoffs was largely under the restructuring label. ↑

