Bank Credit Conditions + FCIs are Tailwinds to Growth
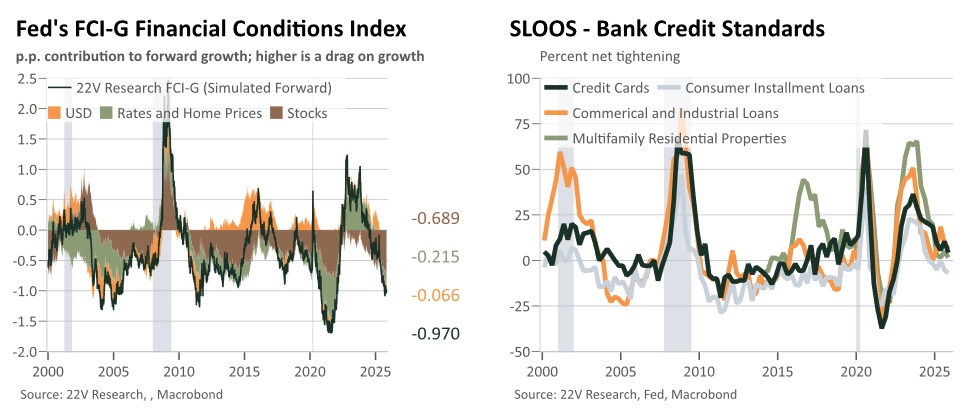
- The Fed’s quarterly SLOOS (senior loan officer opinion survey) was just released and points to a broadly growth supportive lending environment.
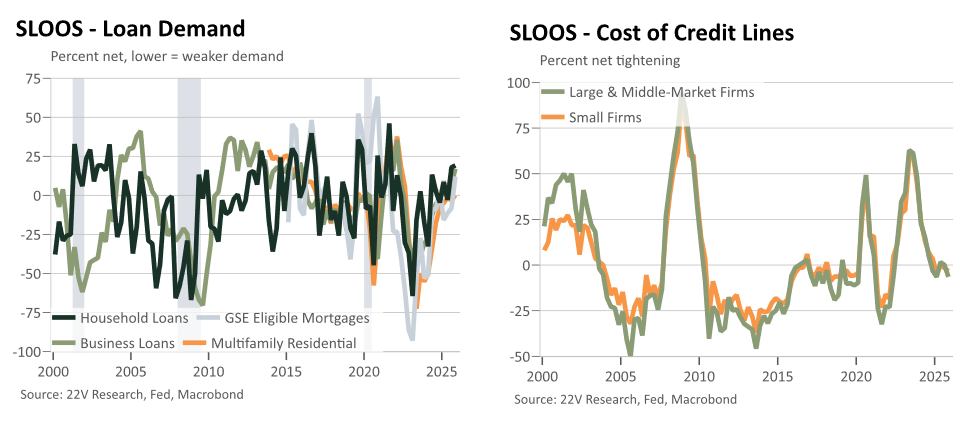
- After the spring and summer’s mini-tightening, with tariff-related uncertainty fading and topline growth solid-to-strong, credit standards are mildly easing, loan demand is picking up, and pricing is easing a bit. This is all consistent with what we heard during bank earnings season a few weeks ago.
- 2022-24 saw the largest ever non-recessionary tightening in lending standards. This pre-recessionary prep gave the banking system and private sector balance sheets’ buffers and leaned against overheating.
- Supportive credit conditions, along with very easy overall financial conditions, are now an additional tailwind to growth over the medium-term.
After the spring and early summer’s tariff-induced recession scare, loan demand is back up, lending standards are gradually easing again (its most helpful to think of the SLOOS more in rate of change than level terms), and loan spreads are modestly tightening again. It is worth remembering that we only got modest certainty on the post-Liberation Day tariff deals in mid-July, which feels like an eternity ago but given summer planning and holiday cycles was simply not that long ago.
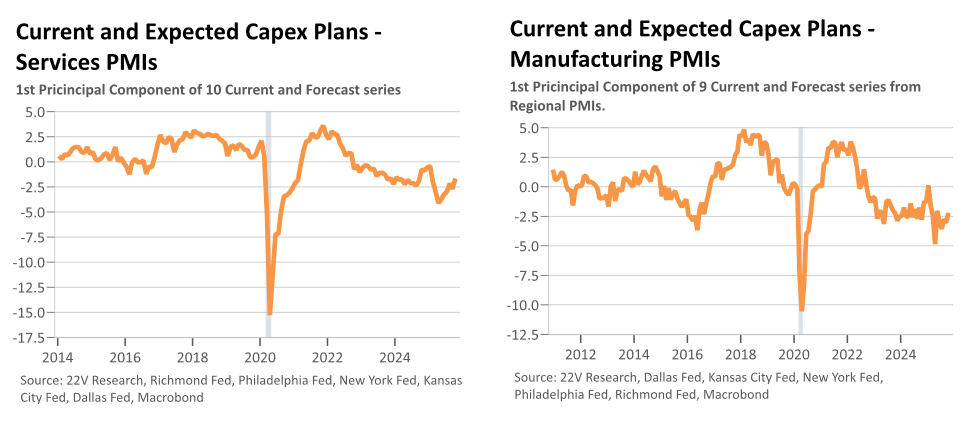
These banking sector dynamics seem consistent as well with mentions of recessions, or similar language, in corporate transcripts and earnings call sentiment. This pattern lines up with the troughing and, so far, mild rebound in capex trends in the regional PMIs and the potential bottoming of hiring intentions in the late summer and early fall. That last one is far a tentative observation given the lack of official data but seems to lineup with firms’ tariff-related levels of caution peaking and then fading. As we now navigate tariffs’ actual impacts, along with the hits to labor supply growth and looming boost from fiscal stimulus in the 1st half of next year (roughly +50bps to the level of GDP in ‘26H1) things are looking better, if myriad cross-currents remain.
Credit standards, as distinct from risk pricing, are an often underappreciated but very impactful cyclical driver. Almost all macro models, even those which include other financial conditions indices, are improved with the addition of the SLOOS, particularly when trying to forecast investment dynamics. This is a good sign for the parts of the economy most in the doldrums the past 3 years. Similarly, loan demand and credit extension are things which happen in good times with broadly optimistic views on the world, not, in aggregate, as forced cash-flow driven actions during recessions. On the heels of such a larger tightening in credit behavior, this rebound is a positive signal for activity into 2026.
With broader FCIs easy and the 2022-24 credit standards tightening behind us, the growth impulse, or lack of constraint, from credit markets is an important cyclical tailwind over the medium-term.