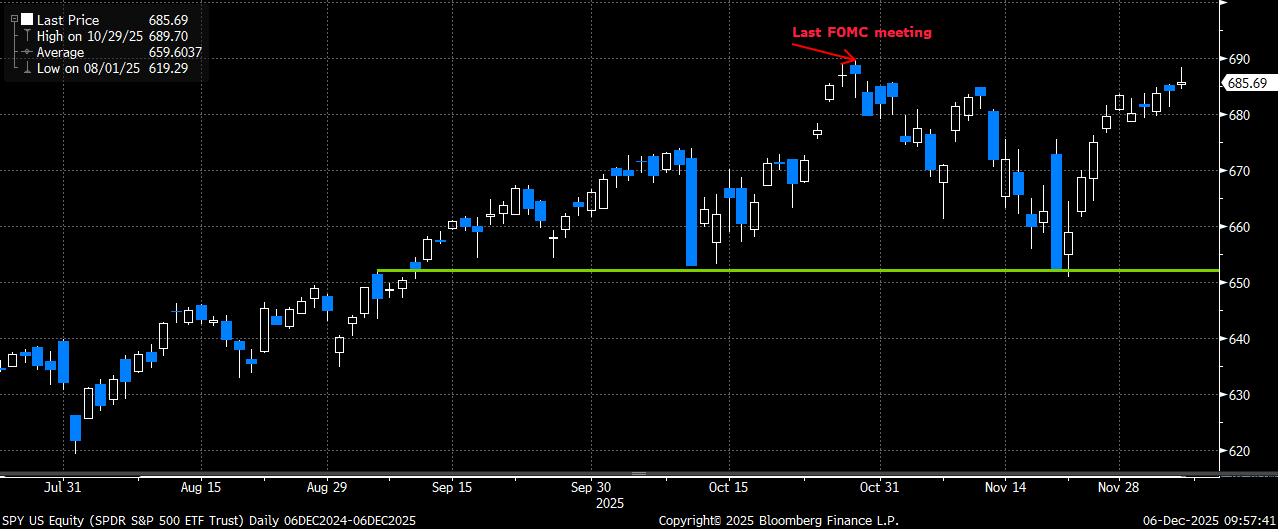
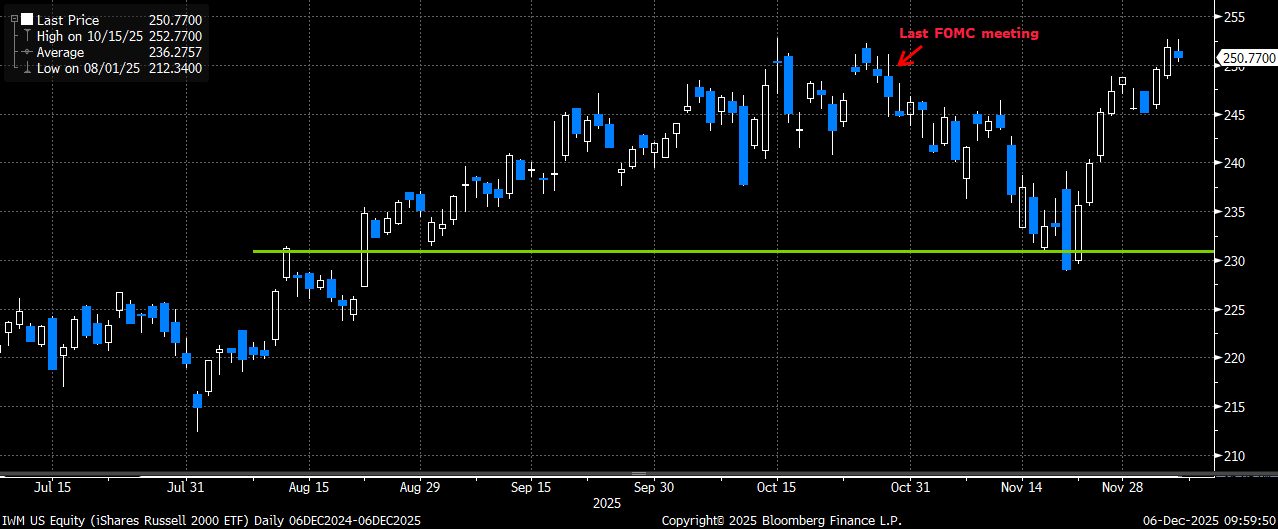
As we head into another FOMC meeting and rate decision this week, I can’t help but think that the volatility and technical setup now looks VERY similar to the setup we had back at the end of October before the last Fed decision. Just like in October, the market has rebounded from a decline and has moved back to the highs, while at the same time volatility (VIX) has moved back to the lows. In October, the S&P (SPY) literally peaked on the FOMC day (10/29) and we have still not had a close above the highs reached that day (although we are just below). The small caps (IWM) peaked a few days before that same October meeting, and they too have been unable to close above those former highs.
The S&P (SPY) literally peaked on the last FOMC meeting date and has now rallied back to just below those highs
Small caps (IWM) peaked a few days before the meeting and has also rallied sharply into the meeting back to the highs
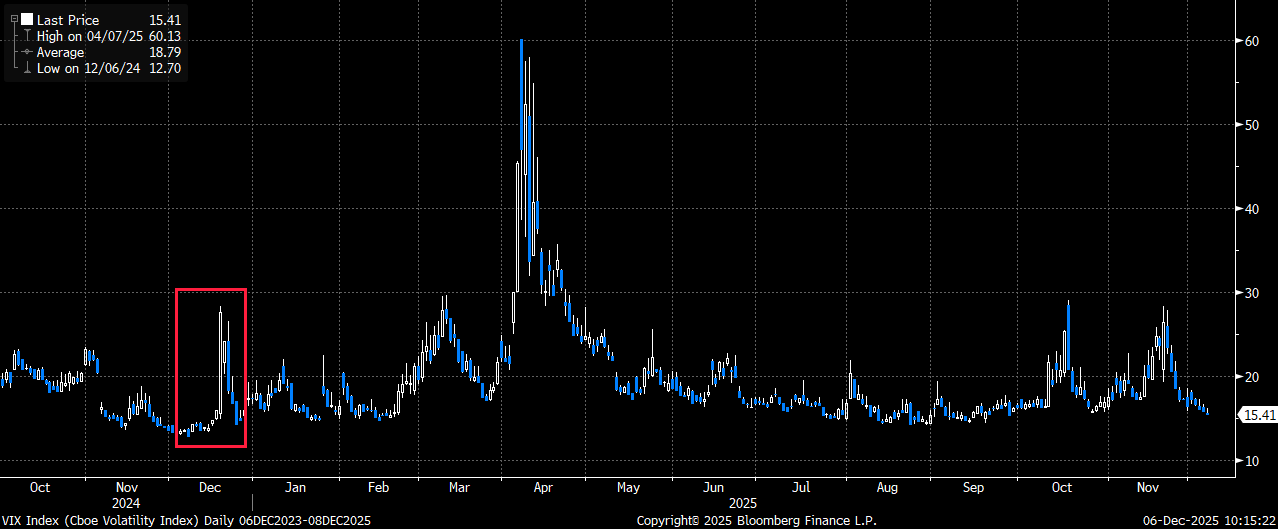
Looking at volatility, VIX closed on Friday just above the 15 level, which has also marked the lows in vol since late September. We had a very similar move in the VIX in October as we saw a sharp decline from the China trade selloff spike on 10/17 back to ~ 15-16. Just like with the equity markets, VIX essentially bottomed right before the Fed meeting and then spiked again in November as stocks came under pressure.
The VIX has now roundtripped twice in the past few months and is back at the levels that has marked a “floor” since late September

So, we have had a sharp rally into the former highs with volatility at the lows into an event that has basically been priced in (rate cut odds for this meeting stand at ~ 96%). We already saw the market “sell the news” on the last rate cut, so is it not possible that we see a similar-type reaction on the cut/Powell press conference? In addition, investors must be thinking about ways to own vol now that we have moved all the way back to the VIX lows once again, especially since have just had two moves where the VIX has DOUBLED in short order. Let’s not forget either the very sharp spike in the VIX we saw last December when it went from ~ 13 to 28 as we had another short-lived market decline (when vol was priced very low like it is now). Owning vol/hedges here would also fit with the call that Dennis and the Portfolio Strategy team have been suggesting about “violently flat” markets. We just had a very sharp rally back from the November lows, so to see it move back lower (from known resistance) shouldn’t come as a surprise.
VIX spiked very sharply last December when vol was “cheap” like it is now
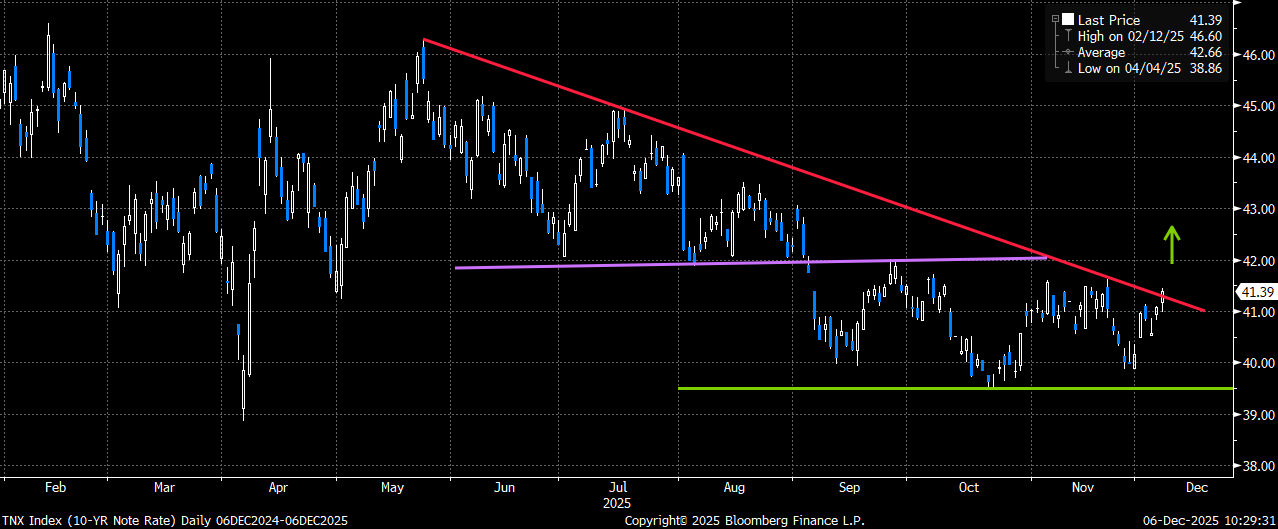
The last thing I want to highlight is yields. We have already seen the 10-year yield move from ~ 4% to 4.14% over the past week (also something Dennis and the Portfolio Strategy team have been suggesting could happen since late last week). In fact, yields on the 10-year have now climbed above the downtrend they had been in since May (see below). A further move higher in yields (perhaps on a “hawkish cut”) would also likely put some pressure on risk assets (especially the more rate sensitive areas like small caps, homebuilders, etc). Just like we saw stocks peak on (or just before) the last Fed meeting, bonds peaked shortly before the meeting, and we saw yields move higher thru most of November (even as risk assets declined). The fact that yields have already started moving up ahead of the upcoming meeting could be a warning sign for both bonds and risk assets.
10-year yields have been moving higher into the Fed meeting and have already climbed above the May downtrend
Putting this all together, I believe now is a time you want to own vol and/or hedges. Not only do we have the Fed meeting this week, but we also have a ton more data that will be released next week as well (Nov Jolts on 12/15, Nov payrolls on 12/16, Nov CPI on 12/18 and the BOJ rate decision on 12/19). So even if the FOMC decision is a non-event (or markets continue higher off of it), there are enough potential catalysts after to still warrant owning vol/hedges here in my opinion.
I mentioned owning hedges on IWM, TLT and XLP last Sunday (here) as well as a Homebuilder (ITB) hedge on Thursday (here). I still like those trades a lot, especially given the poor action we have seen from bonds over the past week. Please reach out to me if you would like to discuss updated structures on any of those products ahead of the meeting.
What I would also like to highlight now is a new VIX trade as I do believe being long vol (VIX calls or wide call spreads) makes a lot of sense as a tactical macro/portfolio hedge.
Trade:
Buy VIX Jan 21st 22/50 call spread for ~ $1.20 (Jan VIX futures 19.20 ref)
Trade Details:
- Buying the Jan VIX call spread with vol (VIX) having moved back to the recent lows and ahead of the FOMC decision (and a slew of data next week)
- We saw a very similar-type of volatility (and price) setup into the last Fed meeting in October – then saw vol spike as markets dropped shortly after
- We also saw a large spike in the VIX last December when markets were also pricing in little to no chances of a meaningful move higher (like now)
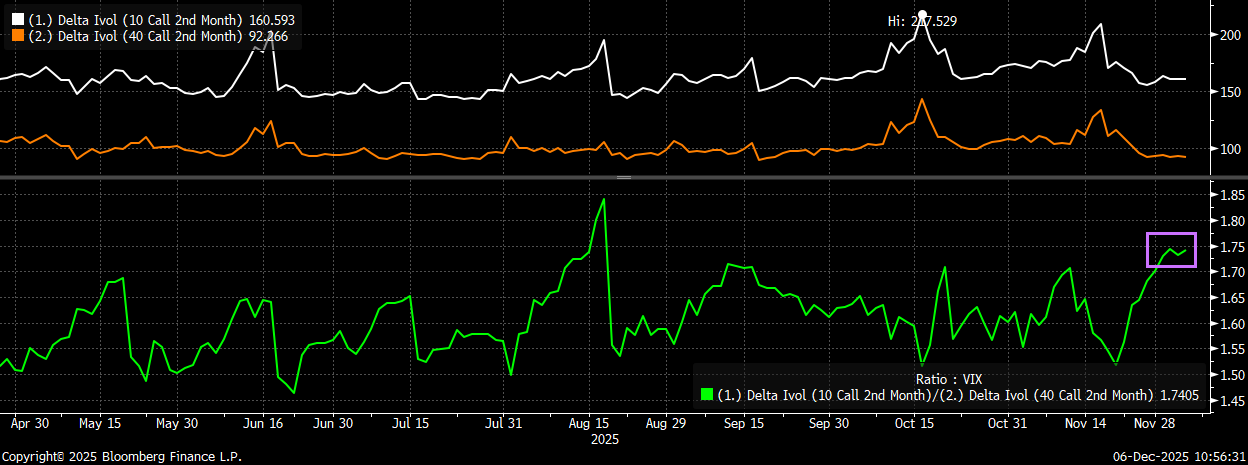
- VIX 10d/40d call skew is also just below the 6-month highs, which is why I prefer to Jan call spread to outright calls
- Spread is wide enough to allow for monetizing should we see a meaningful move higher in vol (can roll up long calls, close spread, etc)
- Trade fits with the Portfolio Strategy team call of violently flat markets and possibly higher yields over the next month or so
- Please contact me or the 22V sales team for updated pricing and execution capabilities
VIX 10-delta/40-delta call skew just below the 6-month highs (bottom chart). Why I like owning call spreads here in VIX