

Every two weeks we update signals from 22V’s proprietary China Economic Sentiment Series (CHESS) tool. CHESS uses ChatGPT to assess the sentiment of economists commenting in China’s domestic financial media. The result is a series of sentiment indices that provide a real-time view of shifts in expert opinion toward different aspects of the financial and economic outlook.
SUMMARY
In this CHESS update, we look at what analyst sentiment has to say about a timely debate: the divergence between China’s hot equity markets and the more lackluster readings on the economy.
In our recent write-up of our research trip to China (link HERE), we observed that economic sentiment on the ground, as expressed by our contacts, is more subdued than what market sentiment might suggest. Our own in-house view on the economic outlook is also cautious, as we see headwinds ahead for growth (a property double-dip, the end of export front-loading, entrenched deflation), but little near-term urgency by Beijing to stimulate demand (see our Politburo meeting analysis HERE).
The latest signals from CHESS are not a flashing red light for equities, but do represent a yellow light:
- The recent improvement in CHESS sentiment toward the equity market has outpaced that of broader economic sentiment.
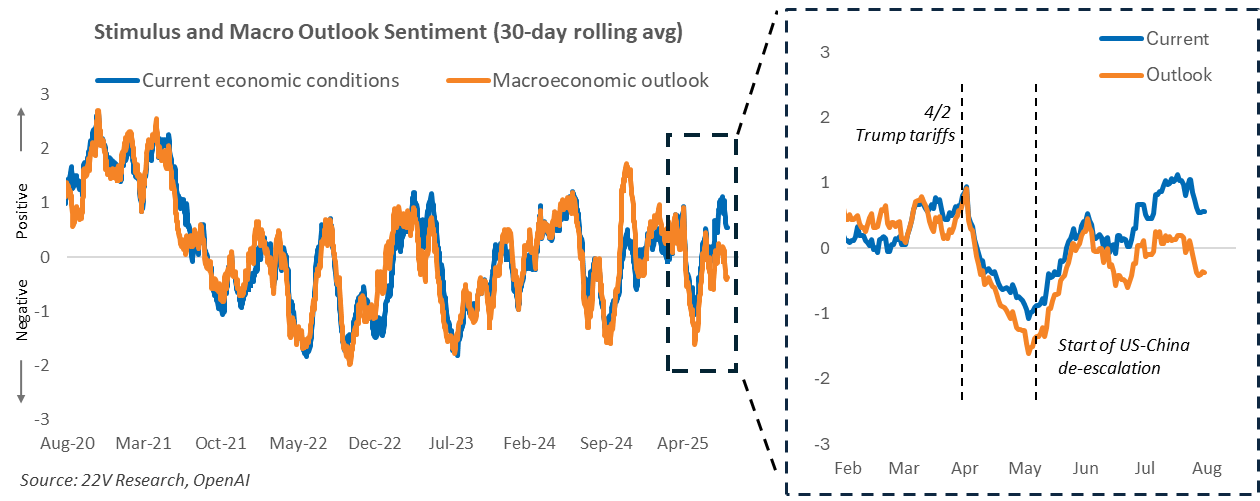
- The divergence between sentiment toward current economic conditions (positive) and sentiment toward the macro outlook (negative) is now the widest gap on record (since 2019). In short, analysts expect a recent stabilization of activity to come under pressure.
Together, these factors suggest that in the near term, further upside for Chinese equities will need to depend on drivers other than the macro outlook, such as attractive valuations, global rebalancing of capital flows away from the US to other markets, and enthusiasm for Chinese tech companies. These are reasonable arguments, and we would not argue for shorting Chinese equities. But there is a risk that the rally loses momentum given the subdued macro backdrop.
Further details below.
Equity Sentiment Outpaces Other Areas
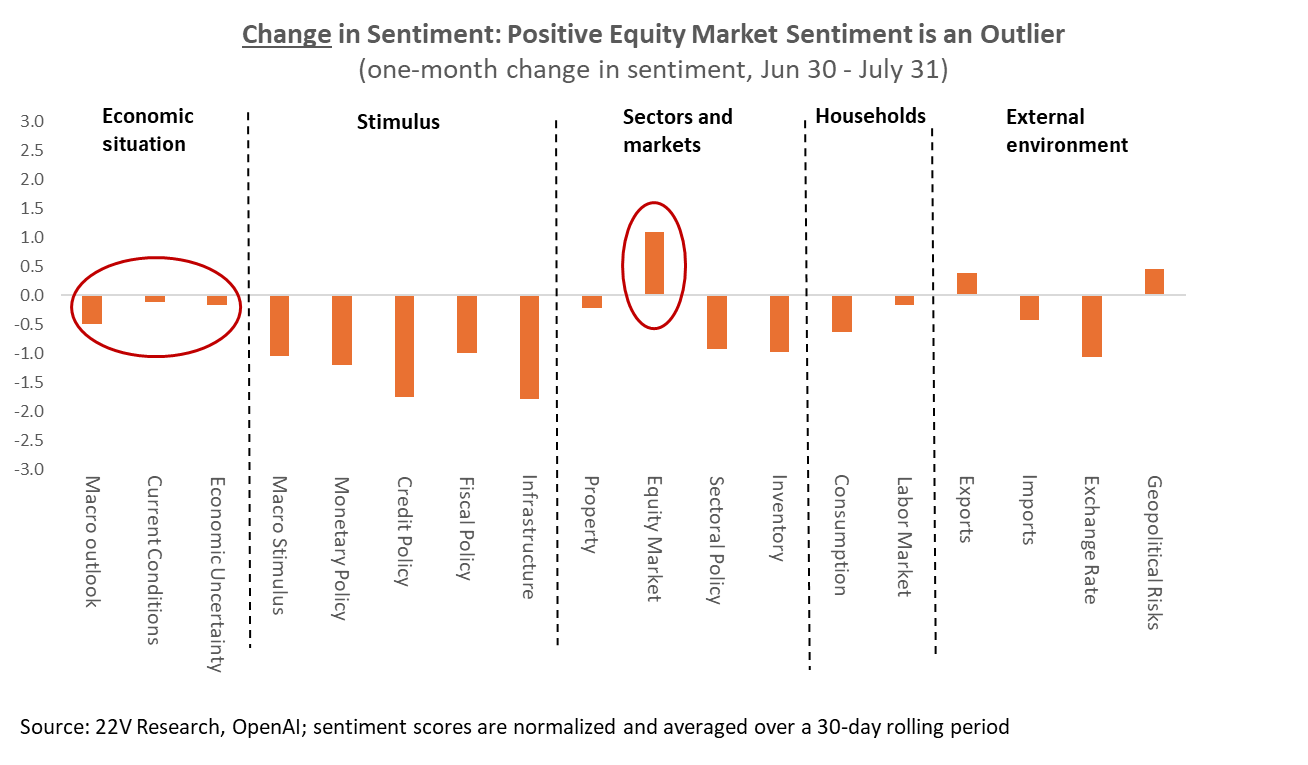
The first chart below shows the change in CHESS sentiment across categories in the last month (June 30-July 31). Sentiment toward equities is an outlier as the only CHESS category with a solid improvement; export sentiment and geopolitical/trade risk sentiment both improved modestly. Sentiment toward the economy declined slightly, while expectations for stimulus fell after China posted relatively strong headline GDP growth of 5.2% in Q2.
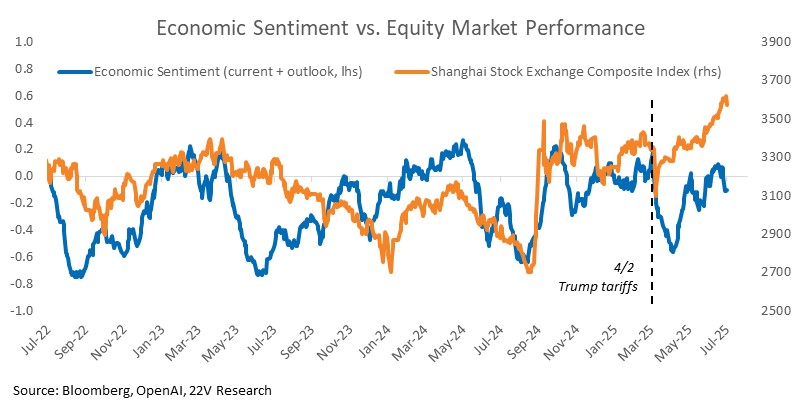
The next chart compares recent price performance for the Shanghai Composite Stock Index (orange line) with a measure of “economic sentiment” (blue line) – a simple average of sentiment toward current economic conditions and sentiment toward the macroeconomic outlook. Equities looked past President Trump’s initial announcements of reciprocal tariffs in early April, anticipating that economic sentiment would subsequently improve. The question now is whether equities are correct in shrugging off a recent decline in economic sentiment. Equities and sentiment can move in opposite directions, of course, as they did in 2023 (improving sentiment, falling equity prices). The recent decline in economic sentiment is not determinative for stocks but worth noting.
Wide Gap Between Current Conditions and the Economic Outlook
An additional point of caution is the unusually wide gap between sentiment toward current economic conditions (blue line below) and the much more subdued sentiment toward the macroeconomic outlook. This is the largest gap between the two indices since the start of the CHESS data in Feb. 2019. CHESS signals imply that analysts see the current climate as sound, whereas the outlook is negative.
This is consistent with the macro setup for the next few months. Growth faces stronger headwinds from the end of export front-loading, the fading impact of consumption support, and continued contraction in property activity. Yet the recent Politburo meeting downplayed the prospect of near-term stimulus.
Export Outlook Stable, But Declining Expectations for Stimulus and Consumption
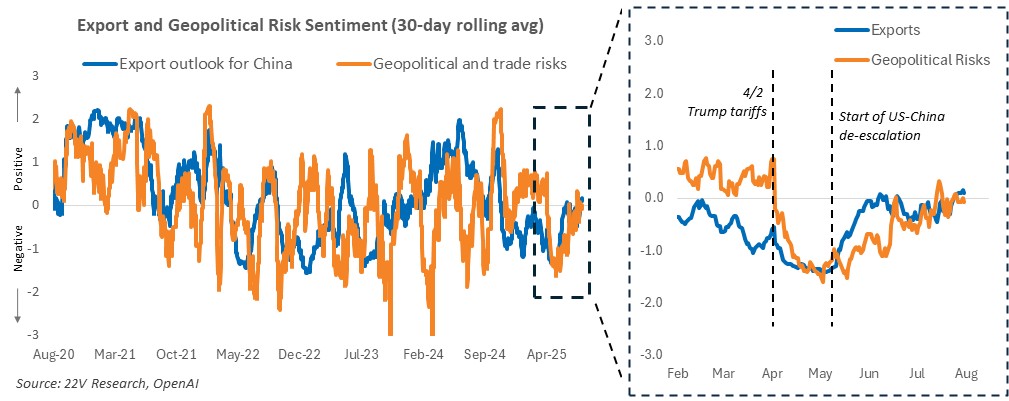
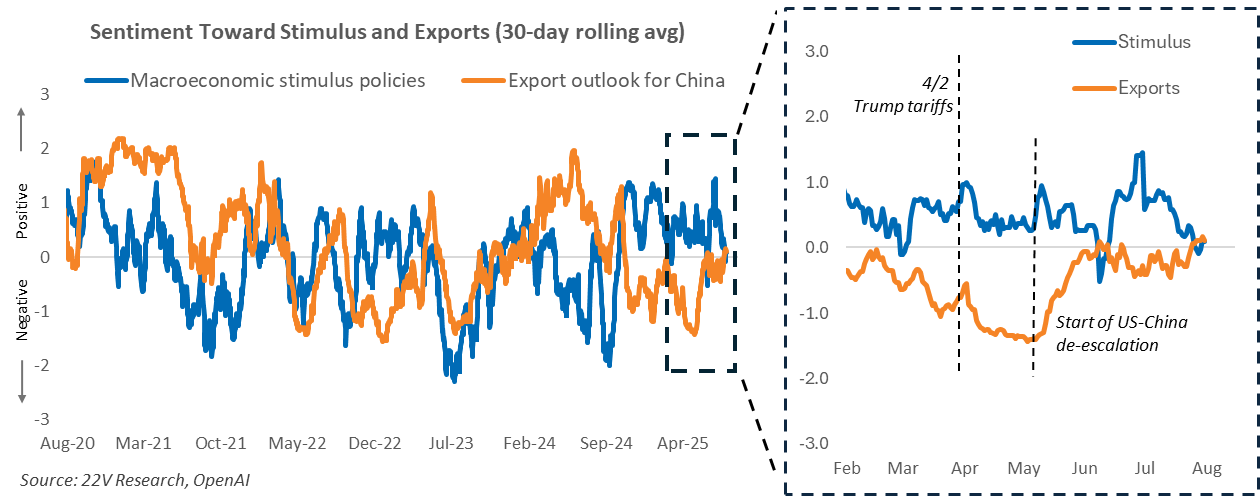
As the chart below shows, sentiment toward the external sector – exports and geopolitical/trade risks – has stabilized in recent months to a level around neutral. This reflects several rounds of de-escalation in US-China tensions, and the likelihood of a Trump-Xi meeting in October that keeps tensions manageable.
However, with the recent stabilization of export sentiment, expectations for stimulus have declined sharply in the last month. The July 30 Politburo meeting did little to shake up these expectations, with the leadership showing little near-term urgency to boost support for growth (see our write-up again HERE).
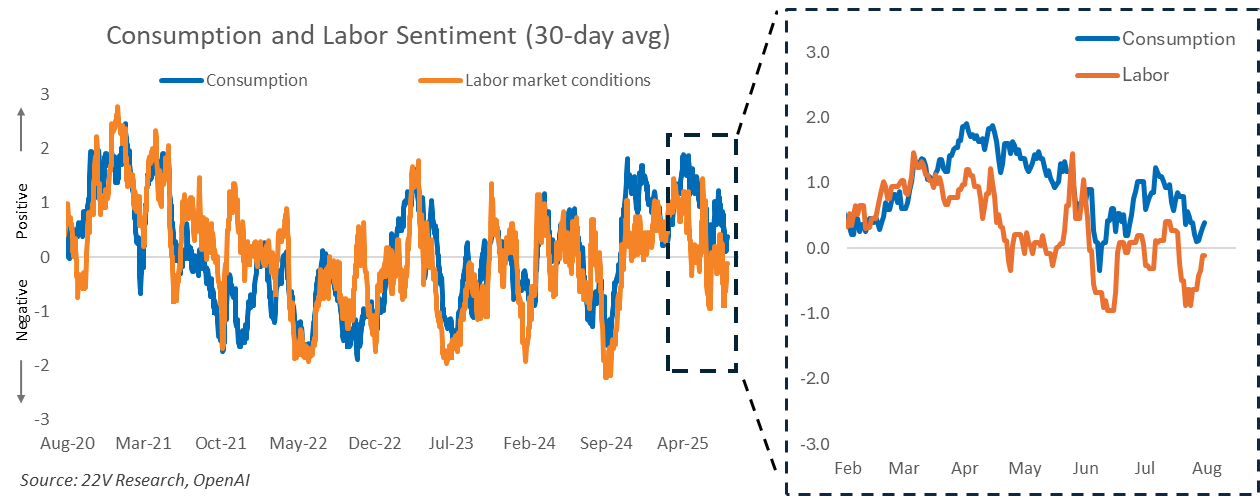
Finally, the last few months have seen a notable decline in sentiment toward consumption (blue line below) and the labor market (orange line). The decline in sentiment toward consumption is partly due to the diminishing effects of China’s trade-in program for autos and household appliances. The program boosted retail sales from late 2024 through the spring. In recent months, however, funding has declined while pent-up demand for targeted areas has also run its course. Beijing will likely shift support from consumption to services, but overall funding in H2 will be modest.
Another headwind for consumption is the weak labor market, where analyst sentiment has now dipped into negative territory. Job creation has been anemic due to the loss of construction sector work in the property sector, and the muted recovery in the service sector since the pandemic. There are few near-term catalysts to accelerate job growth in the absence of strong macro stimulus.
CHESS is a collaborative project, leveraging the expertise of Sophia Wang, 22V’s Director of Quantitative Research, and China-based economic consultant Dr. Fei Han. The authors express thanks for contributions and insights.

