

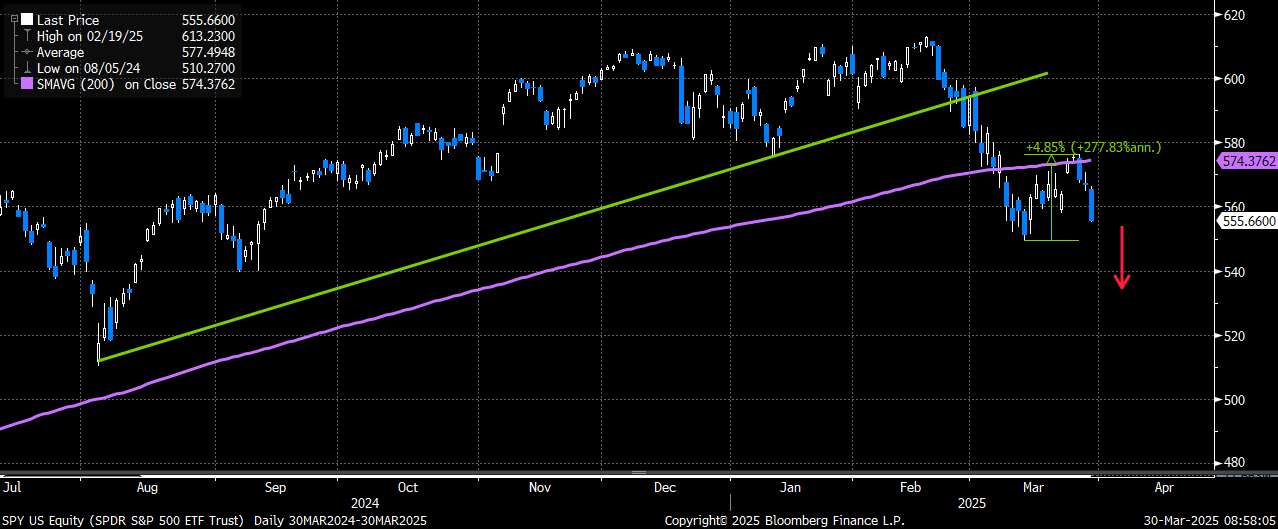
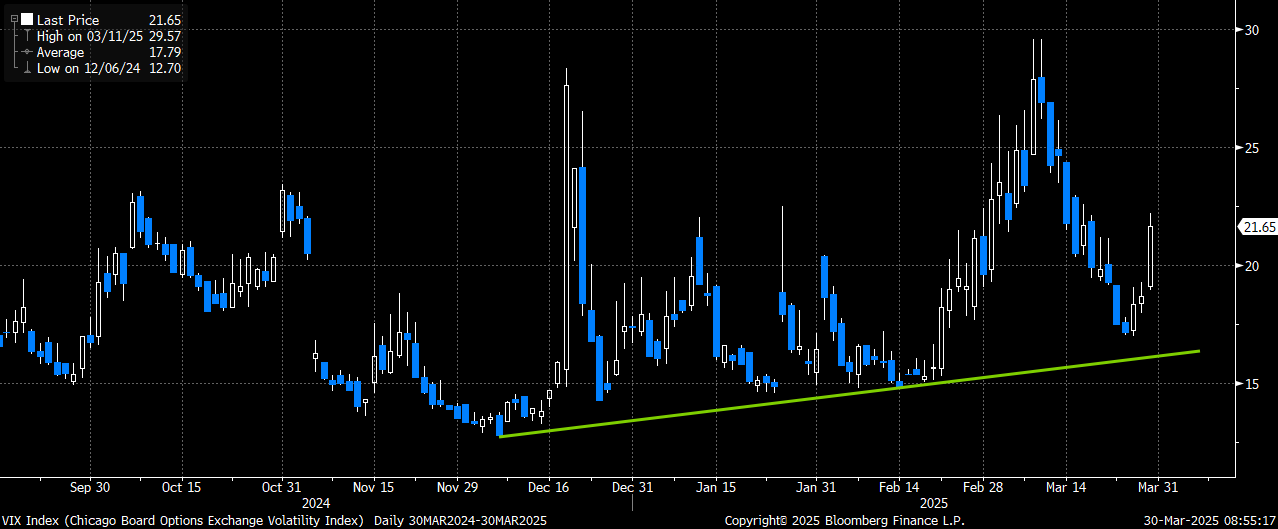
After bouncing by ~ 5% off the oversold lows, the markets resumed their selling to end last week. The SPX (SPY) is now only ~ 1% above the 3/13 lows, while the tech-heavy QQQ is less than 1% above the recent lows. VIX made a low ~ 17 as markets rallied to start the week but closed at 21.65 as the selling intensified thru Friday. It has been this type of negative action as to why I have continued to stress owning April put spread collars on both the SPY and QQQ for macro portfolio hedges.
A few things to consider about the SPY and QQQ hedge structures I suggested last week. First, even at the height of the rally off the recent lows on Tuesday, the short calls remained 2-3% above where the markets peaked. Second, each structure is now worth ~ 2-3x their initial cost so there are plenty of ways to monetize the position while still having the protection on. Finally, the long put spread for both is now effectively at the money as we head into a week where we have the tariff deadline on 4/2 and then the March payroll report followed by a speech from Chair Powell on 4/4 and should perform rather well should we see follow-thru weakness.
The market (SPY) rallied ~ 5% off the oversold lows and is back to only 1% above the lows. Potential for a break to new lows seems high
VIX dropped from a high ~ 29 to ~ 17 on the rally and is now moving back higher as market weakens
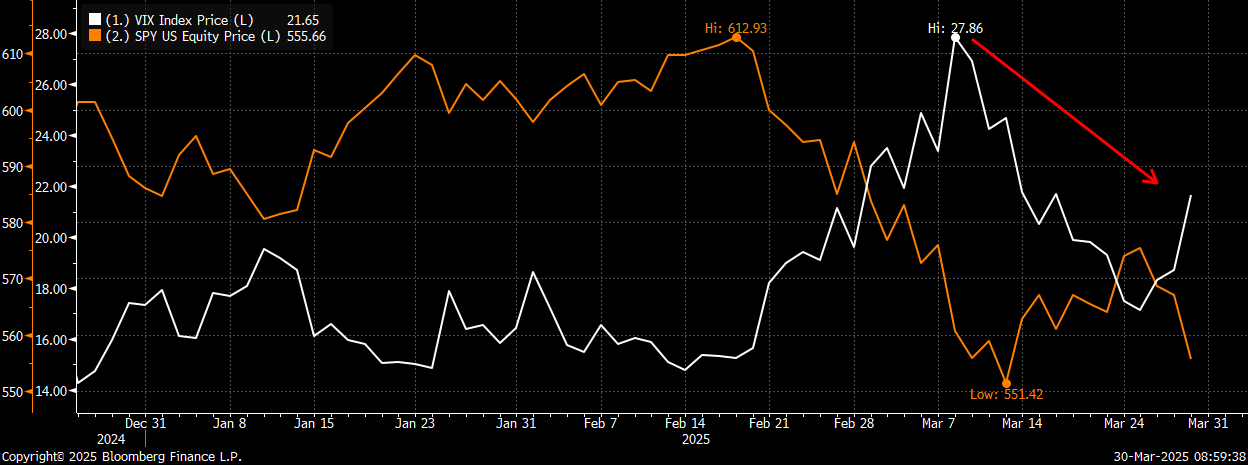
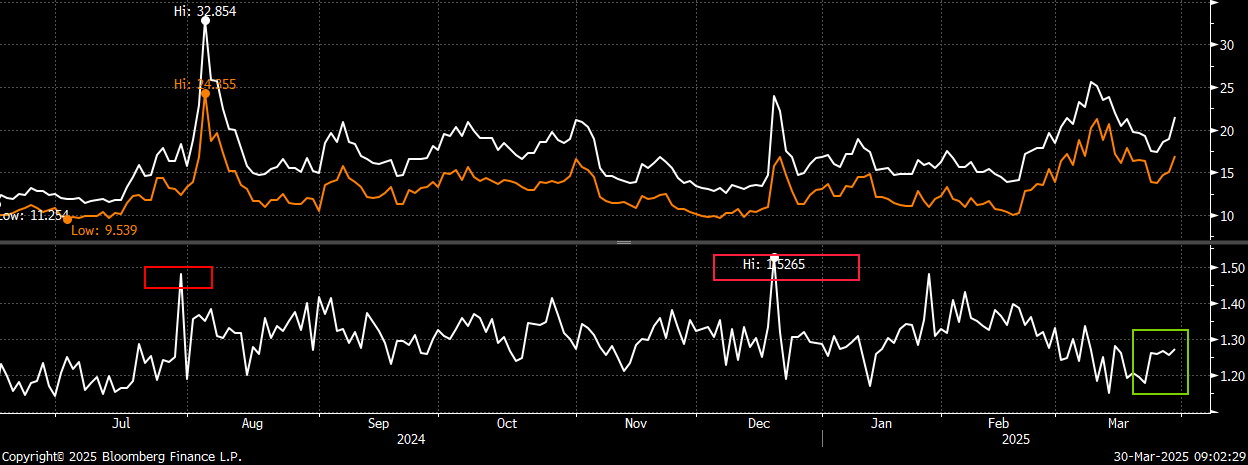
Here are a few observations regarding volatility that make me concerned that the lows for the markets may not be in just yet. First, with the markets now just above their recent lows, VIX is well below the highs hit earlier in the month. I believe we would need to at least see a re-test of the highs in VIX before markets can bottom. Second, I am still seeing downside put vol trading near the cheaper side relative to upside calls. This put/call skew typically trades much higher when we see market weakness like we have been experiencing as of late. The fact that there hasn’t been the “panic” put buying either speaks to continued complacency or investors still being more concerned about missing the potential upside vs protecting further downside. This skew is also a reason why I continue to favor owning protective put spread collars on the index level, and would now use any rallies to consider adding May structures for that trade. Please feel free to reach out to me to discuss specific May structures.
VIX remains well below the highs hit earlier this month, even as the indexes are barely above the lows
Still not seeing much “fear” as the 25-delta May puts continue to trade “cheap” to the 40-delta May calls (typically we see spikes in this skew)
Now is the time to hedge financials for upcoming earnings season
On Friday, the 22V Portfolio Strategy team mentioned in their note a XLF trade I suggested to hedge financials in the short-term (here). XLF dropped ~ 2% on Friday (after being up initially) which was in-line with the the overall market. Even with the decline on Friday, I still believe banks/financials are still at risk for further weakness. Keep in mind, XLF rallied by nearly 8% off the March lows and is still ~ 4.5% above those lows (while SPY is only ~ 1% above the lows). While I still believe April put spreads make a lot of sense, I wanted to introduce a new May put spread collar trade idea that I also like here. Bank earnings kick-off on April 11th, but given how the overall market acts, I prefer to establish hedges now.
Much like SPY and QQQ, XLF May vol remains elevated so put spread collars are a compelling way to offset this vol when establishing new hedges for earnings season. In general, we continue to see weakness on earnings as companies either miss or are cautious on guidance. This past week we saw LULU (14%), JEF (-10%) and KBH (-5%) all move lower when they reported. JEF should be especially concerning for the financials as the stock was already down by ~ 27% heading into the report and yet it still got punished as they spoke about lower overall deal activity.
Trade:
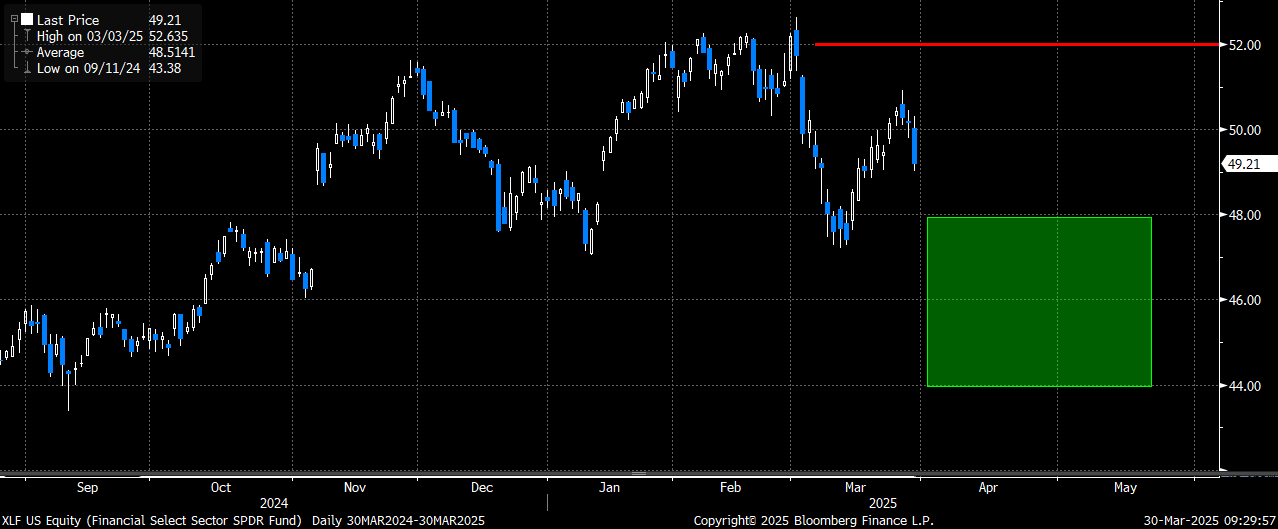
Sell XLF May 52 calls
Buy XLF May 48/44 put spread
Costs .30 (XLF 49.21 ref)
Like using the highs ~ $52 as upside call to sell vs buying the downside put spread
Trade Details:
- Selling the 5.7% upside calls (at the recent highs) to buy the protective put spread that starts less than 2.5% below spot
- Selling the upside call and downside put covers 67% of the cost of owning the closer to the money put (XLF was down nearly 2% just on Friday)
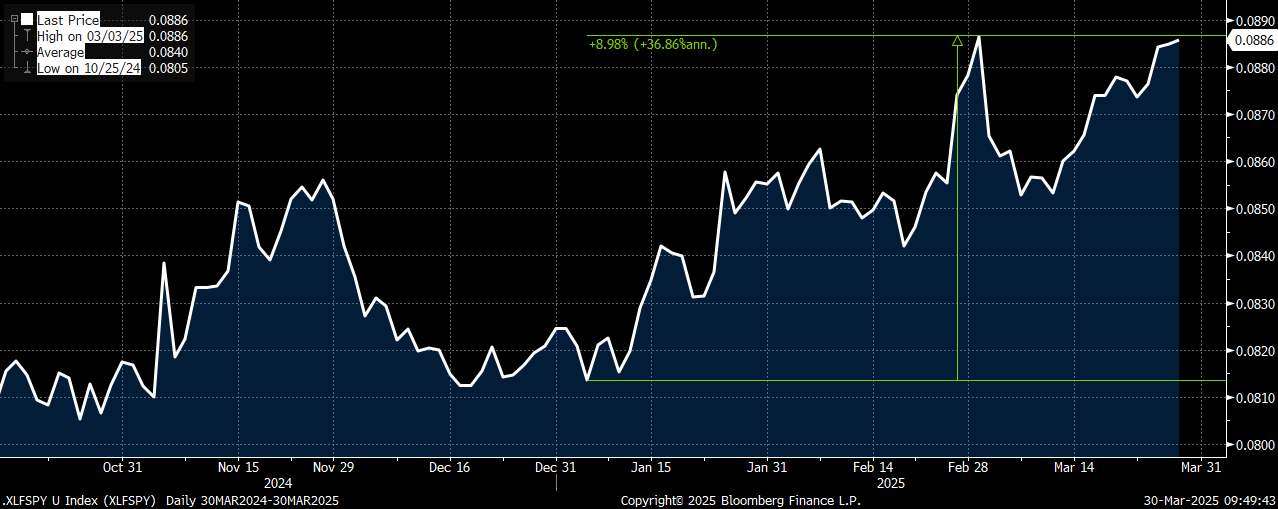
- XLF/SPY relative spread is up 9% from the early Jan lows and now back to the highs (could see banks give back some of the relative outperformance)
- May expiry captures earnings from basically all the top-weighted names in XLF
- XLF put vol continues to trade “cheap” to many of the top constituents
- Please reach out to me or the 22V sales desk for updated pricing and execution capabilities
XLF/SPY relative spread up 9% from the Jan lows and now back to the YTD highs
XLF 40-delta May put vol continues to trade at a steep discount to some of the larger names (GS, JPM and BAC)

