Bottom Line: If the Fed’s best guess for interest rates is premised on dovish assumptions playing out going forward (financial conditions are tight, inflation declines to 2.6% while growth slows to slightly above trend – more details HERE), those assumptions NEED to play out. Factor vol is likely to stay high until we get a clearer signal on inflation trends.
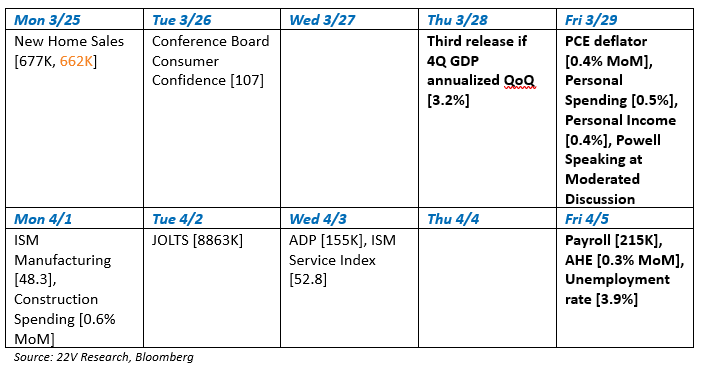
Things to Watch [Consensus, Results]:
Economics: Outlook for Financial Conditions
Most investors we talked to seem to agree with our take that financial conditions are NOT exerting a drag on the economy. Powell said financial conditions are still a drag. Our sense is investors doubt that the current level of financial conditions can be maintained and there is a risk they need to tighten. If the labor market data is on the hotter side on April 5th, people will further question Powell’s assessment of financial conditions. If April 10th CPI data is hot, an aggressive reassessment is a real risk. Sectors and factors that have benefited from easier FCI will suffer (Earnings Risk Tech, Biotech, Financials, Value).
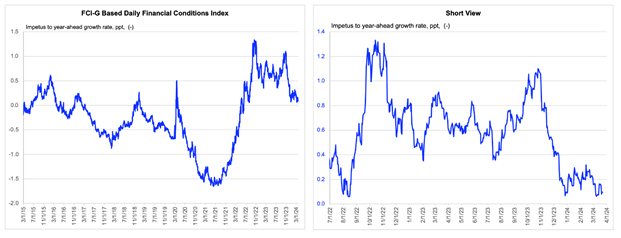
Source: Bloomberg, Federal Reserve (for the formulation), FH conversion to daily frequency. Data are to the Friday close.
Quant/Portfolio Strategy: Market Internals More Risk-on/Value Post FOMC
Market internals shifting after the dovish Fed meeting last week. At the factor level, Risk-on and Value factors took leadership (HERE) after the risk-off gains earlier in March. At the sector level, Early Cyclicals (Tech, Discretionary, Comm Svcs) outperformed both Deep Cyclicals (Energy, Industrials, Materials) and Defensives (Healthcare, Utilities, Staples). Internals retraced some on Friday, and factor vol is likely to remain elevated near-term as investors debate if financial conditions are tight enough to keep inflation on a Fed friendly path. That being noted, the macro backdrop remains supportive of risk-on and GARP.

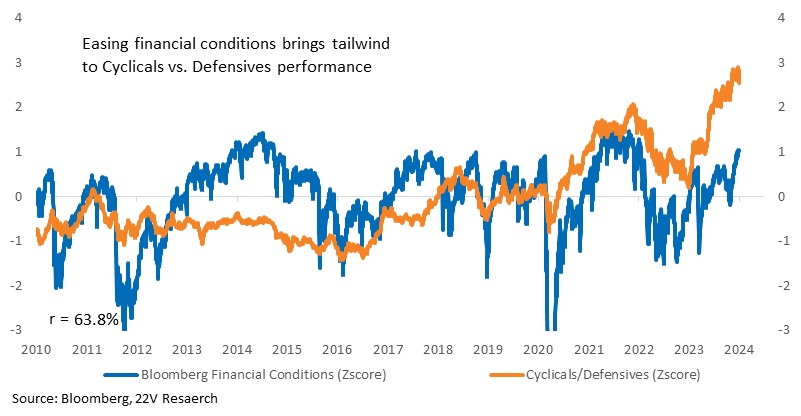
Financial conditions have been one of the macro factors most impacting Cyclicals vs. Defensives rotations, especially post-COVID. Easing financial conditions generally support Cyclicals, and have contributed to the outperformance of Cyclicals this year. Powell made it clear the FOMC thinks 1) financial conditions remain restrictive and 2) that inflation will trend lower. Those are forecasts and subject to change, but the policy bias is to leave FCI alone, which is a risk-on/cyclical support.
Commodities: Bullish Stance for Gold Remains
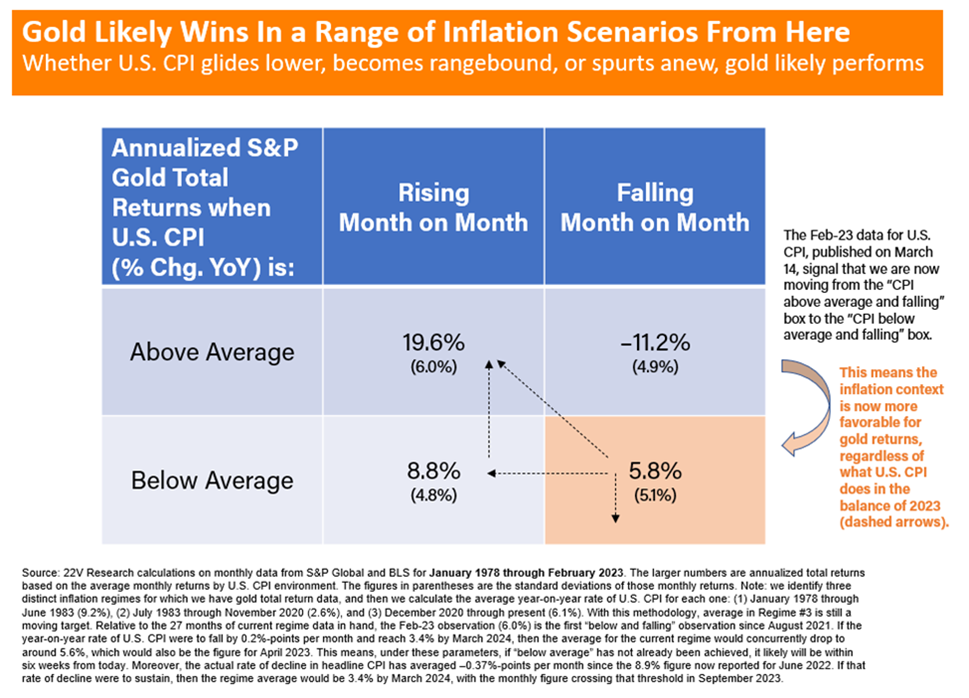
For the past year, 22V’s commodity specialist’s stance on gold has been bullish, anticipating favorable returns and hedging benefits in portfolios, with an initial expectation of 6% to 9% annualized returns. Following gold’s breach of its previous all-time high in December 2023, he revised our outlook to anticipate a spot price regime of +10% to +15% per annum. 22V’s commodities specialist’s bullish stance extends to gold miners, with expected upsides of +20% to +45% per annum, presenting a rare opportunity for bold investors despite continued skepticism. Our conviction in the long-term viability of gold as an investment theme remains strong, with a recommendation to consider gold futures, gold ETFs, and gold miners’ shares.