SUMMARY: The rapid pace of the S&P rally to start the year is hard to sustain and some consolidation should be expected. Investors seem to be internalizing this point as NVDA was down 4% on no news ahead of its earnings today. NVDA’s implied vol around earnings is unusually high (~10.5%). Investor sentiment is above the 75th percentile relative to the breadth of data, suggesting lower than normal forward returns for the S&P on a 1/3/6 month basis. Given the outperformance of the Low Vol factor and Mega caps, S&P consolidation SHOULD be led by those groups, assuming inflation tail risks remain low. We expect inflation tail risks will remain low given the recent softening of economic demand indicators. Risk-on factors will work in our view, on a relative basis, even as the S&P consolidates.
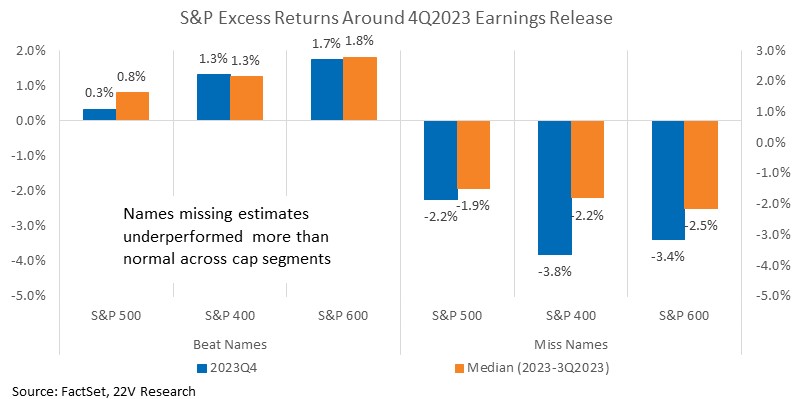
Earnings Trends Likely a Larger Driver When the Market Consolidates: The quant team highlighted yesterday (HERE), 4Q earnings season was much stronger than expected; the S&P has had a 80% beat rate with a +5.2% intra-quarter earnings revision. Macro headwinds reduced the immediate value of strong earnings beats though. Higher implied equity and bond volatility meant companies that beat were rewarded less than normal this past season, and names that missed earnings were punished MUCH more. Fundamentals will matter more with lower macro uncertainty, which will play out if the next round of data isn’t as hot as January. Market consolidation should favor fundamentals as well.

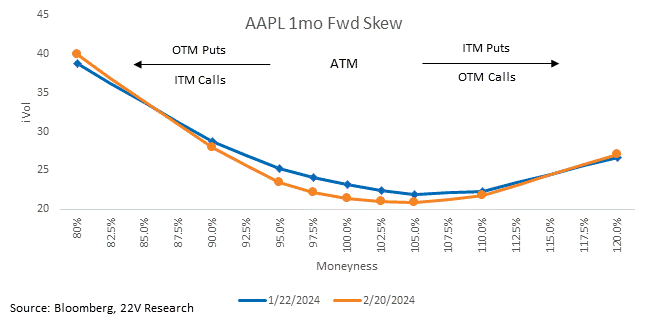
AAPL PUTS: John Roque thinks Apple’s weakness will continue. $180 is the key support level. Past that, $165 is next. Apple is in a weak absolute position and is even weaker relative. FYI John’s been flagging long IWM relative to Apple. Apple $165 puts would be a good trade/risk management. FYI, the volatility structure out 1 month is similar now to mid and late Jan, when Apple was outperforming the S&P. This suggests options aren’t pricing in unusual pessimism right now, creating an opportunity for buying puts/selling calls. More details in the full report below…
Full report below…
MARKET VIEWS: As the quant team highlighted yesterday (HERE), 4Q earnings season was much stronger than expected; the S&P has had a 80% beat rate with a +5.2% intra-quarter earnings revision. Macro headwinds reduced the immediate value of strong earnings beats though. Higher implied equity and bond volatility meant companies that beat were rewarded less than normal this past season, and names that missed earnings were punished MUCH more. Fundamentals matter more with lower macro uncertainty, which will play out if the next round of growth data isn’t as hot as January.
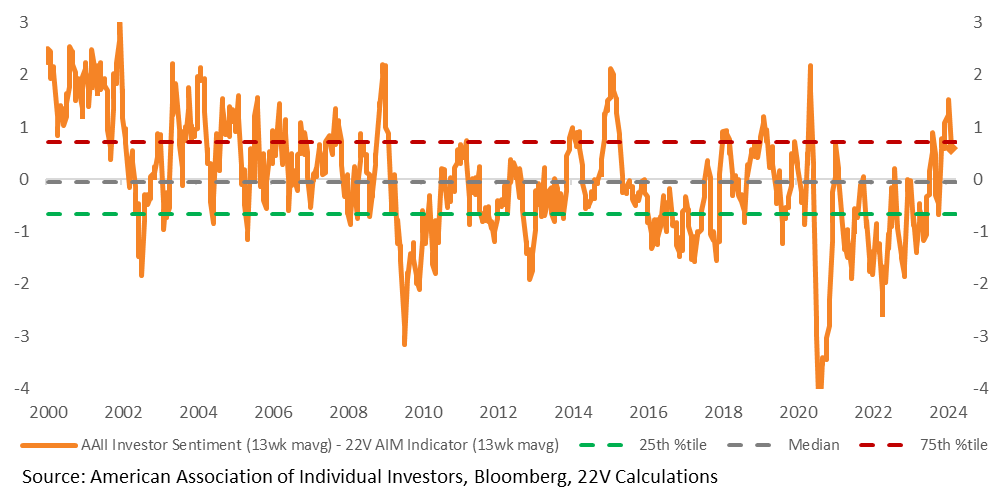
SENTIMENT VS DATA: Investor sentiment has perked up, outpacing the improving breadth of economic data. The spread between AAII net sentiment and our US AIM indicator, which is an aggregation of economic data improving/deteriorating from its prior reading, has reached its 75th percentile.
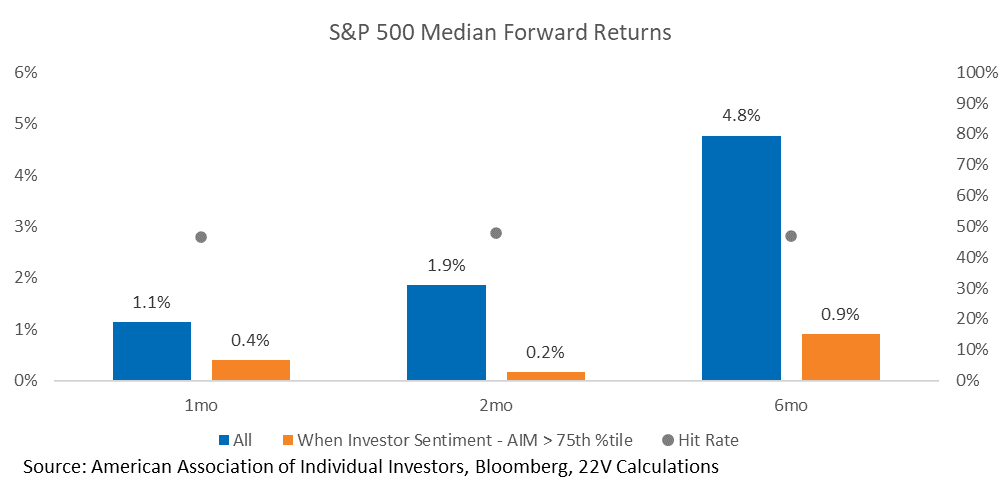
Forward returns for the S&P are worse than normal when the spread is at or above its 75th percentile. Worse data is better for risk-on internals because the Fed needs slower data, but our view on the overall index is muted. We don’t think the S&P as a whole moves higher with slower economic growth, as that is a tailwind for the average stock vs mega caps.
AAPL PUTS: John Roque thinks Apple’s weakness will continue. $180 is the key support level. Past that, $165 is next. Apple is in a weak absolute position and is even weaker relative. FYI John’s been flagging long IWM relative to Apple. More details in his latest note HERE and in the chart below.
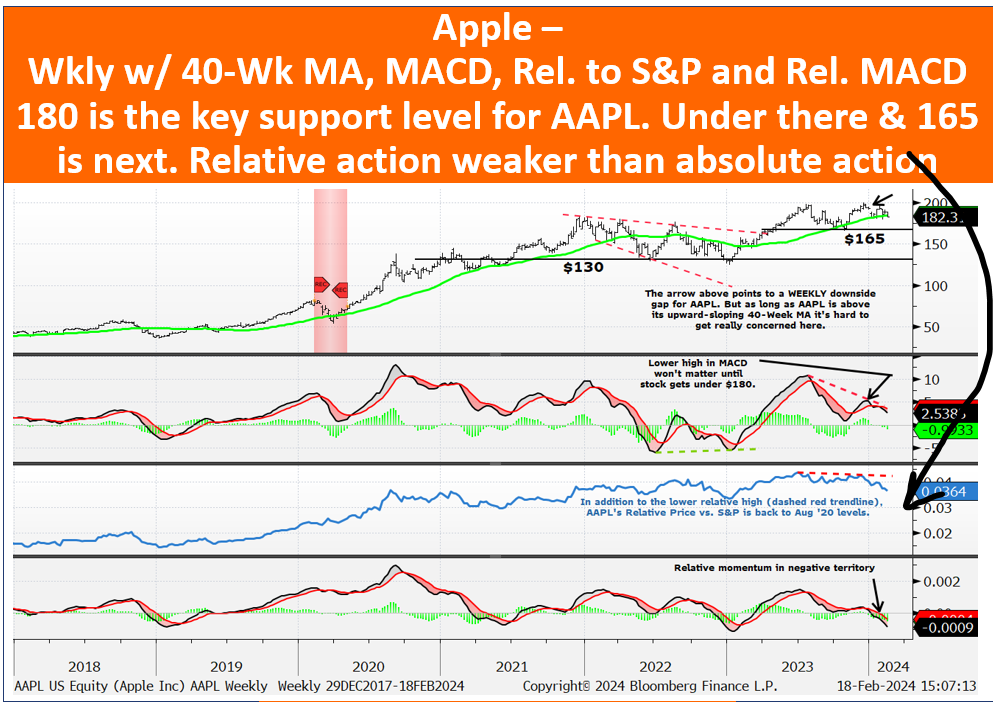
Apple $165 puts would be a good trade/risk management. FYI, the volatility structure out 1 month is similar now to mid and late Jan, when Apple was outperforming the S&P. The time to expiry is the same from both dates plotted below. This suggests that options aren’t pricing in unusual pessimism right now, which would be an opportunity for buying puts or selling calls.