Today’s report is in two related parts. In the first, we look at post-FOMC surprise market internals. In the second, we update our LGBM portfolio. The reason the two are intertwined is that FOMC surprises tend to have an impact on risk factor rotations.
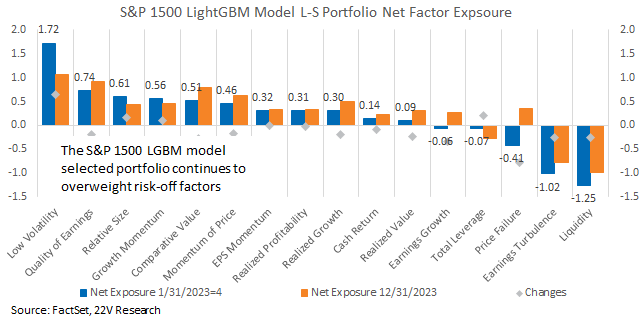
Starting with the FOMC, on days where the Fed surprises markets, which we define as meetings where financial conditions shift relative to their pre-meeting trends, risk-off factors tend to lead. Specifically, Low Vol tends to be the best performing factor, which is exactly what we saw the past Wednesday. During this rate hiking cycle though, in the month AFTER the FOMC surprise, risk-on factors tend to outperform. Returns and sensitivity to Low Vol tends to be negative following surprises. What that means for February is that Low Vol is likely to struggle, while Price Reversal, risk-on, and Growth (more on that in the full report) are likely to lead. So how is that connected to the LGBM portfolio?
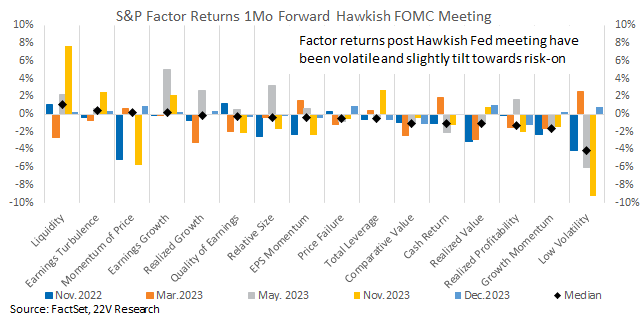
As a reminder, the LGBM portfolio is our machine learning system that attempts to separate the S&P 1500 into a long-short, Dollar neutral portfolio, rebalanced each month using factor, macro, and sentiment readings as features. The model returned more than 5% in January, in part due to its preference for Low Vol stocks heading into January. The LGBM favors risk-off factors most of the time, and that feature preference remains true for February.
So, the FOMC event, which is exogenous to our model, suggests a preference for risk-on, or at least tilting AWAY from risk-off, is the correct stance for February. The LGBM model has increased exposure to Low Vol. We will not override the portfolio as it is designed to be systematic and has delivered consistent strong returns over its tested and live running period. That being noted, it is important to know what the model DOESN’T know. In this case, what the model is unaware of is that a risk-off tilt is likely a headwind over the next month.
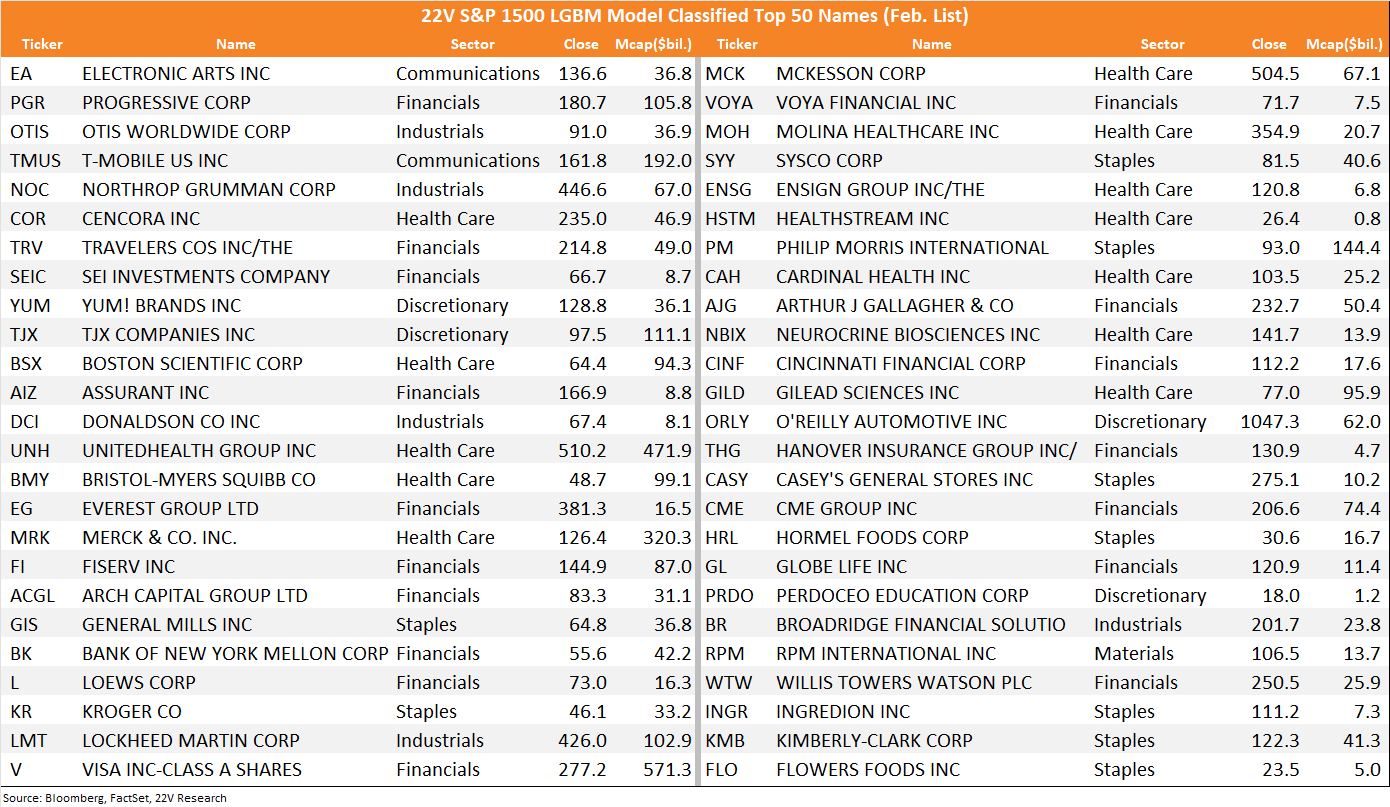
We list the current top/bottom ranked stocks according to the model at the end of this report. A complete list of its ranks are available upon request. We can also run custom screening on your universe using the model rankings.
FOMC Impact on Factors: At the FOMC meeting last week Powell indicated fewer hikes this year and a later start date than futures were pricing. The result was another risk-off rotation that saw the S&P rise to an all-time high at the expense of smaller caps. Low Volatility and Momentum rallied. Both factors have performed well around FOMC surprises during the current rate hiking cycle. A strong payroll number added volatility to internals and saw Growth and Momentum factors outperform while Low Volatility slipped lower. So, the FOMC is more hesitant to cut AND growth is stronger than investors were forecasting. So, the question is where does that net out for market internals going forward?

Internals following FOMC surprises have been mixed this cycled but tilts toward risk-on leadership. Filtering FOMC days for periods where financial conditions trends have reversed shows Liquidity and Earnings Turbulence have the best returns over the subsequent month. Low Volatility has been the worst performing factor. One likely reason for that trend this cycle is that macro and earnings data have consistently surprised to the upside. So, disappointing FOMC days led to an initial risk-off move that is reversed over the next month as data continues to confirm that the economy and markets are growing despite high short rates.
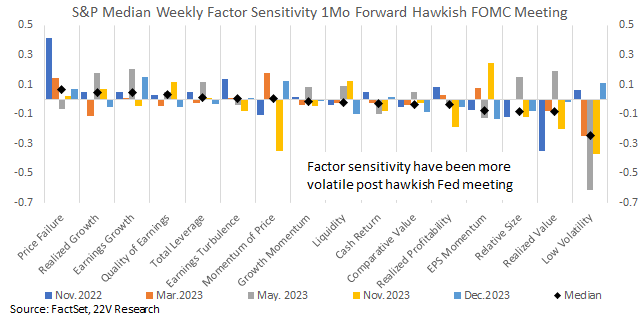
S&P factor sensitivity 1 month after FOMC surprises suggests a similar trend as historical returns. Specifically, Low Volatility tends to be a poor performer after those surprises. Price Failure and Growth factors have the highest sensitivities. In other words, stock prices were more likely to reverse after FOMC surprises and S&P names with strong Growth characteristics are more likely to be favored.
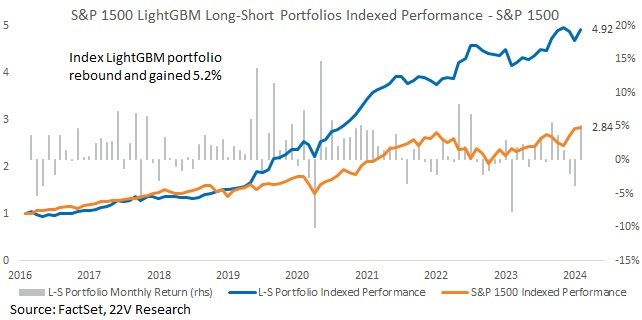
Broad Gain by our LGBM Portfolios: We are also rebalancing out LGBM portfolio and updating the performance tracking today. After a stalling in December our S&P 1500 LGBM model resumed its outperformance in January, rallying 5.2% and adding to the model’s 8 years of gains (HERE). 61% of the stocks in the long portfolio outperformed, helped by the model’s mix of low vol, quality, and momentum tilts.
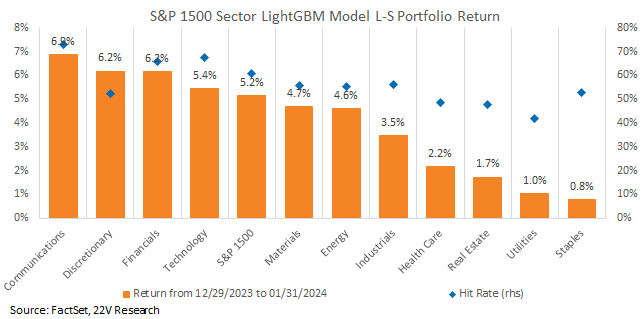
Outperformance was broad with the model’s selection adding to returns across all sectors. Early Cyclicals including Communications and Discretionary saw the greatest gains. Historically, the model performers best in broad sectors with lower correlations. Defensive LGBM baskets returns were also positive but less so.
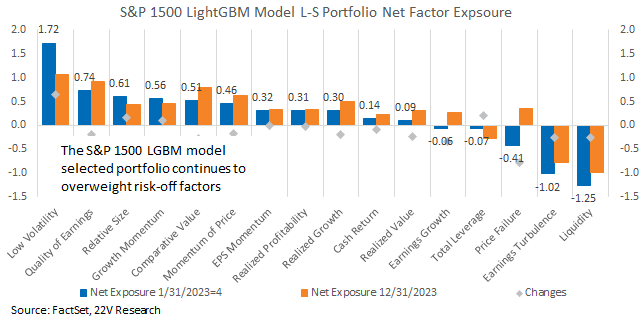
Risk-off factors contributed the most to the portfolio’s gain as Low Volatility outperformed at the expense of risk-on factors. The LGBM portfolio for January was most exposed to risk-off factors and least exposed to risk-on factors. Other than factor exposure, the current LGBM portfolio has been positively exposed to most fundamental factors. The model’s ongoing preference for Low Vol is a risk given the post FOMC backdrop we outlined above. The model has a persistent risk-off preference that reduces upside during strong risk-on rallies, but has proven effective at reducing drawdowns and riding out higher vol periods.
Below we list the top 50 names within S&P 1500 ranking by the index level LGBM model. A full list of S&P 1500 ranking is available by emailing us.