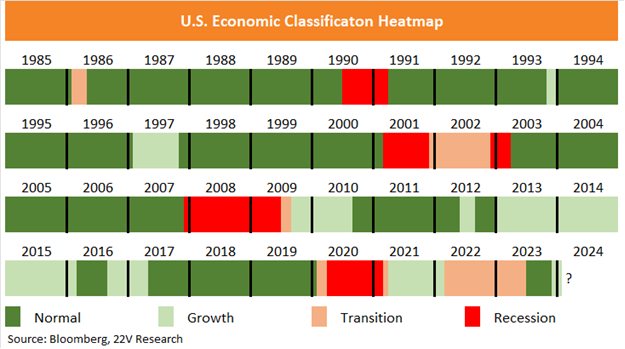
SUMMARY: This week, and especially today, is all about events. Keep in mind that firm economic data is aligned with our 22V Macro Regime Model rotation into a Growth backdrop. As we discussed (HERE), historical rotation into Growth always came with NTM GDP growth expectation improving and favors GARP. We should expect to see a broadening out of equity markets (average stock does better) in a Growth backdrop as well. Assuming no shocks that drive economic expectations significantly lower.
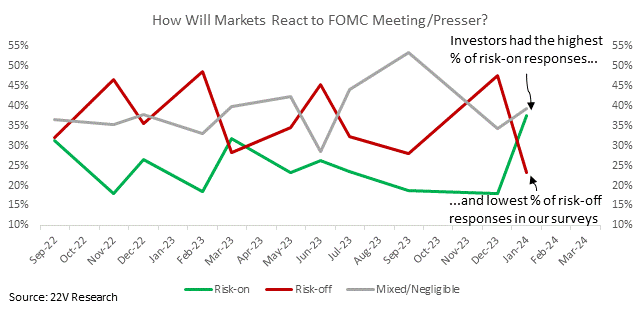
On To the Events: Heading into the FOMC, 38% of our survey respondents expect the FOMC meeting/presser to be risk-on. 39% think mixed/negligible, and only 23% risk-off. That’s the highest percentage of risk-on responses and the lowest percentage of risk-off responses we’ve had since we started our surveys in 4Q22. More people are focused on Payrolls at the end of week though and we would agree that Payrolls are the much larger swing factor for risk assets. The two known economic tail scenarios reside primarily with the labor markets. I.e. labor market data either weakens quickly (6+ cuts to avoid recession gets priced) or payroll growth remains well above 100k (75-100k is estimated to keep the urate flat) and wages stay firm or even hook back up. And the Fed signals we need much tighter financial conditions.

On the FOMC: To the extent Powell focuses on wage growth firmness, vs other indicators of labor market loosening, that would be at the margin hawkish. And could make slight upside beats to payroll on Friday a much larger issue. Otherwise, we are with consensus that this meeting will be about Powell not committing to a March cut and emphasizing that the data will determine if a March cut happens or not.
Full report below…
MARKET VIEWS: The stronger than expected economic data (stronger than stale 2024 GDP estimates of 1.3%) and a Fed still likely to cut should continue to favor risk-on factors (SMID GARP has performed well all month) and the average stock over the mega caps. Today is all about events, but keep in mind that improving economic activity data are aligned with our 22V Macro Regime Model’s rotation into a Growth backdrop. As we discussed (HERE), historical rotation into Growth always came with NTM GDP growth expectation improvements and favors GARP. We should expect to see a broadening out of equity markets (average stock does better) in a growth economic backdrop as well.
Now On to The Events: Heading into the FOMC, 38% of our survey respondents expect the FOMC meeting/presser to be risk-on. 39% think mixed/negligible, and only 23% risk-off. That’s the highest percentage of risk-on responses and the lowest percentage of risk-off responses we’ve had since we started our surveys in 4Q22. More people are focused on Payrolls at the end of week though and we would agree that Payroll the much larger swing factor for risk assets. The two known economic tail scenario risk reside primarily with the labor markets. I.e. labor market data either weakens quickly (6+ cuts to avoid recession gets priced) or payroll growth remains well above 100k (75-100k is estimated to keep the urate flat) and wages stay firm or even hook back up. And the Fed signals we need much tighter financial conditions.
Peter Williams notes (HERE) that yesterday’s JOLTS signaled the labor market continues to be less tight at the margin. This may reduce near-term risk management concerns for the Fed, but this release is not impactful enough to shift many officials’ broader views on the state of the business cycle. Peter continues to think that cutting rates will be based on inflation data. The layoffs rate, jobless claims, and WARN notices all suggest that firms are hesitant to actively reduce headcount. There is little sign of outright weakness in layoffs or openings especially, while hires and quits suggest the churn bullwhip is ongoing.
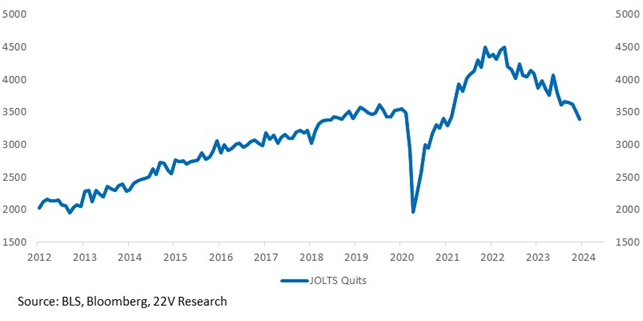
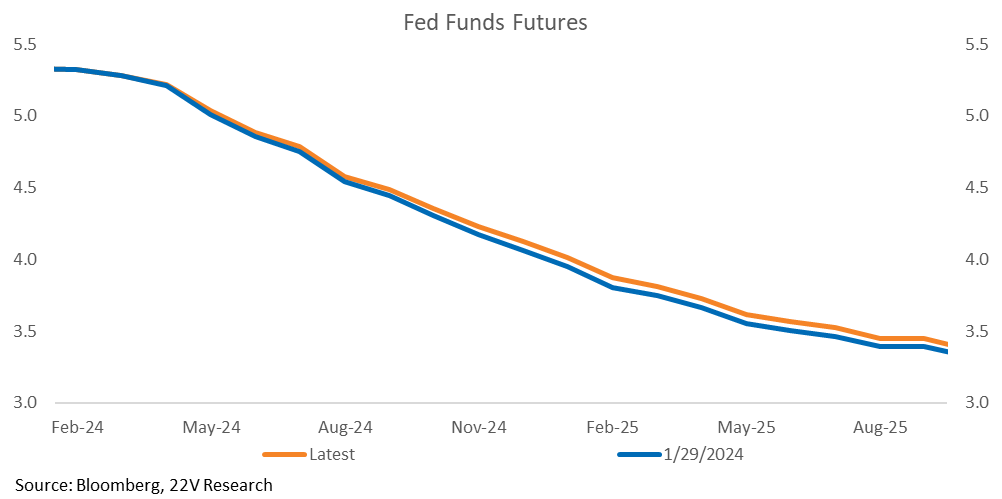
This release does not show underlying weakness in the labor market, indicating that the economy is still strong. Equity markets are beginning to price in possibly less cuts in the year ahead than originally expected, especially if this week’s data continues to be hotter than expected. For today, to the extent that Powell focuses on wage growth firmness, vs other indicators of labor market loosening, that would be at the margin hawkish. And could make slight upside beats to payroll on Friday a much larger issue.