

Bottom Line: Risk-on and Value factors worked last week. Low Vol, a risk-off factor, was a drag across all segments outside of Mega caps. That shift is consistent with market internals catching up to macro trends like steepening curves and narrowing spreads (easier FCI in general). There is more room for risk-on factors to “catch up” to the current level of financial conditions in a normal economic expansion, which is what we are in right now according to our Macro Regime Classification Model (HERE). Fundamental factors (Earnings and Growth momentum, Value and Growth. Hence, our preference for GARP), should show more persistent outperformance.
Relevant News: The Dallas Fed manufacturing PMI came in much weaker than expected (-27 vs -11 expected) and is consistent with weakness in other Regional PMIs. The survey-based data continues to be VERY difficult to square with the hard data. The Dallas Fed is not the focus though given the massive amount of tier 1 data hitting later this week and that data (and other events like Earnings / Fed meeting) will be the driver of risk assets.
Things to Watch [Consensus]:
Mon 1/29 | Tues 1/30 | Wed 1/31 | Thu 2/1 | Fri 2/2 |
JOLTs [8700K] | ECI [1.0% QoQ] & FOMC | Payroll w/ revisions & AHE [180k, 0.3% MoM] | ||
Mon 2/5 | Tues 2/6 | Wed 2/7 | Thu 2/8 | Fri 2/9 |
ISM Service Index [52.4] | CPI Revisions |
Geopolitics: Update on Middle East Geopolitics
Expect to see a major escalation in the US response (to the death of US servicemen by the hands of Iranian proxies in Syria/Jordan), most likely directly targeting Iranian personnel/assets in the region. It also seems likely that Iranian ships assisting the Houthis in the Red Sea will now be targeted. This remains a proxy war, but surely all Iranian personnel outside Iran will now be fair game for US air/missile strikes. Overall, the level of proxy fighting in the ME will now increase, as the US once again will seek to reestablish its supremacy on the escalation ladder by “hurting Iranian assets in the region”. At the same time, we continue to believe that a direct confrontation with Iran will be avoided and that the direct attacks on Gulf oil facilities will similarly be avoided.
Economics: Thinking Through Risks Heading into a Big Macro Week
Our fundamental fear, but certainly not our base case, is that the failure of wages to catch down to goods and services prices may be evidence that the labor market is more overheated than generally recognized. The combination of well above trend economic growth (IF economic growth stays above the 2.5%ish level) and current wage trends could lead to a much more hawkish than expected Fed. This is not a risk that will be priced this week, especially if the benign payroll estimates are roughly correct, but it is a RISK over time.

Source: Federal Reserve Banks of Atlanta and St. Louis (FRED), FH calculations
While it is not the house view, there is a risk that something happens to change the financial conditions/economic/earnings outlook this week. For example, what happens if we get a slightly hawkish Fed and something from the QRA (Quarterly Refinancing Announcement – where the US Treasury Department announces and quantifies its financing needs for the quarter ahead) that leads to a large spike in yields? Or a very weak payroll report and earnings disappointment that increases recession risk? Or some weird combination we are not thinking about? Speculative parts of the market could just flip back to risk-off again after rallying over the last week.
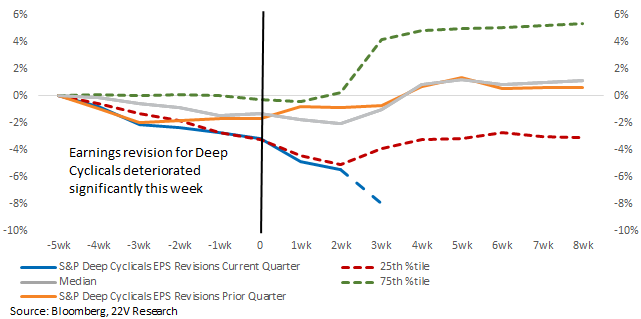
Quant & Portfolio Strategy: Deep Cyclicals Earnings Outlook Lagging Other Groups
Earnings revision for the S&P have been positive over the past few weeks, rebounding from an unusually low level at the start of reporting (more HERE). Deep Cyclicals are a source of weakness though. 4Q Deep Cyclical revisions were weak heading into reporting and have deteriorated since, which is aligned with sentiment deterioration. Deep Cyclicals have performed better as growth data has beat, but the fundamental underpinnings for the group are a concern.
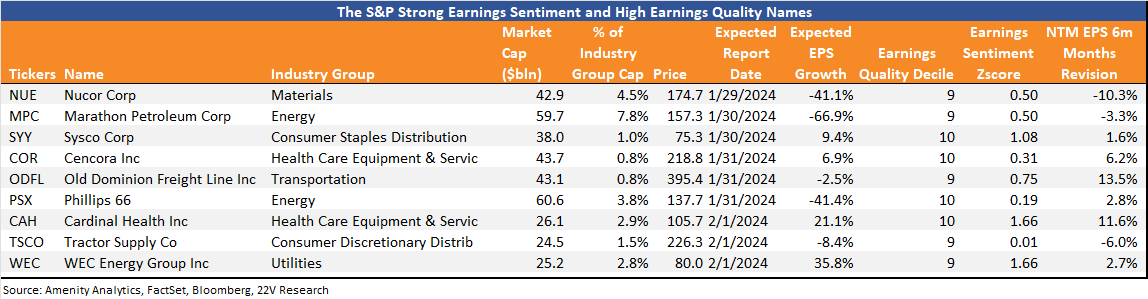
More than 20% of the S&P names will report next week, including 5 mega cap Tech names. Below we list the names meeting strong earnings Quality and earnings sentiment criteria reporting next week. Our earnings beat Swap (bbg MS22BEAT Index) is currently tradable based on the idea.
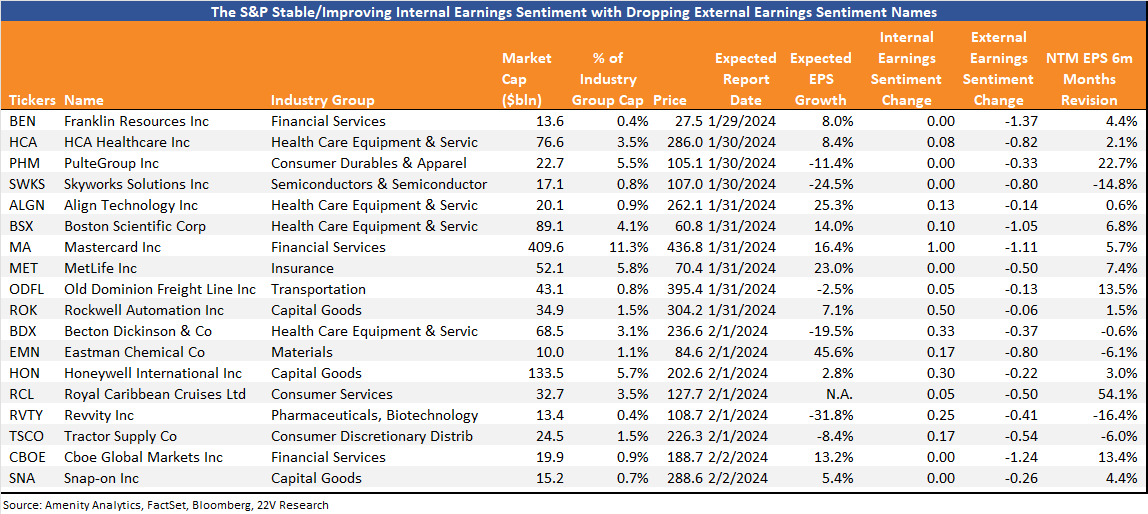
The names with increased/stable internal earnings sentiment and low external earnings sentiment in 3Q that are reporting next week are listed below. The external earnings sentiment rebound Swap (bbg MS22INEX Index) is filtered for same criteria to benefit from macro rebound.
Technical Analysis: Chart Spotlight – SXXP Index
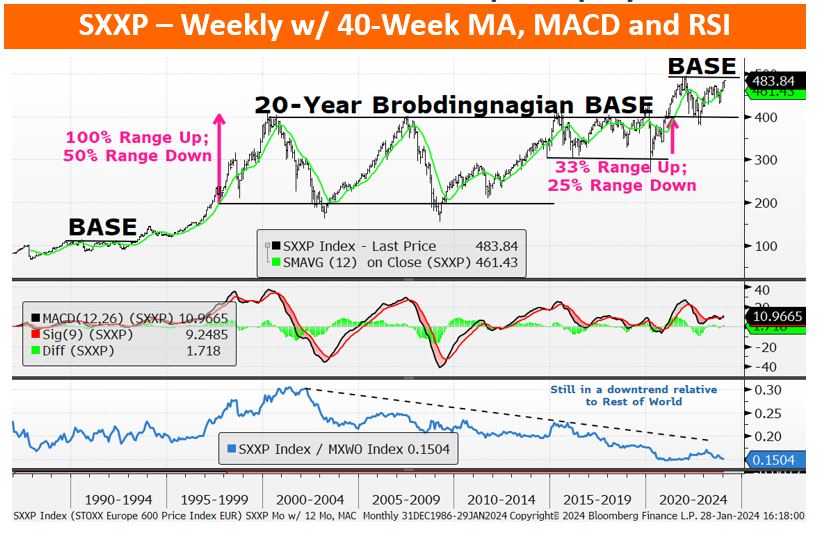
22V’s technical analyst thinks the BASE on a BASE pattern is a constructive setup for the SXXP Index and it’s above its upward-sloping 12-Mo MA. Also, the Monthly MACD is in good shape. The Index is weak relative to ROW, but that’s probably because it’s hard to compete with the US and its Tech weighting.
SXXP Monthly w/ 12-Month MA, MACD, & Relative to Rest of World:
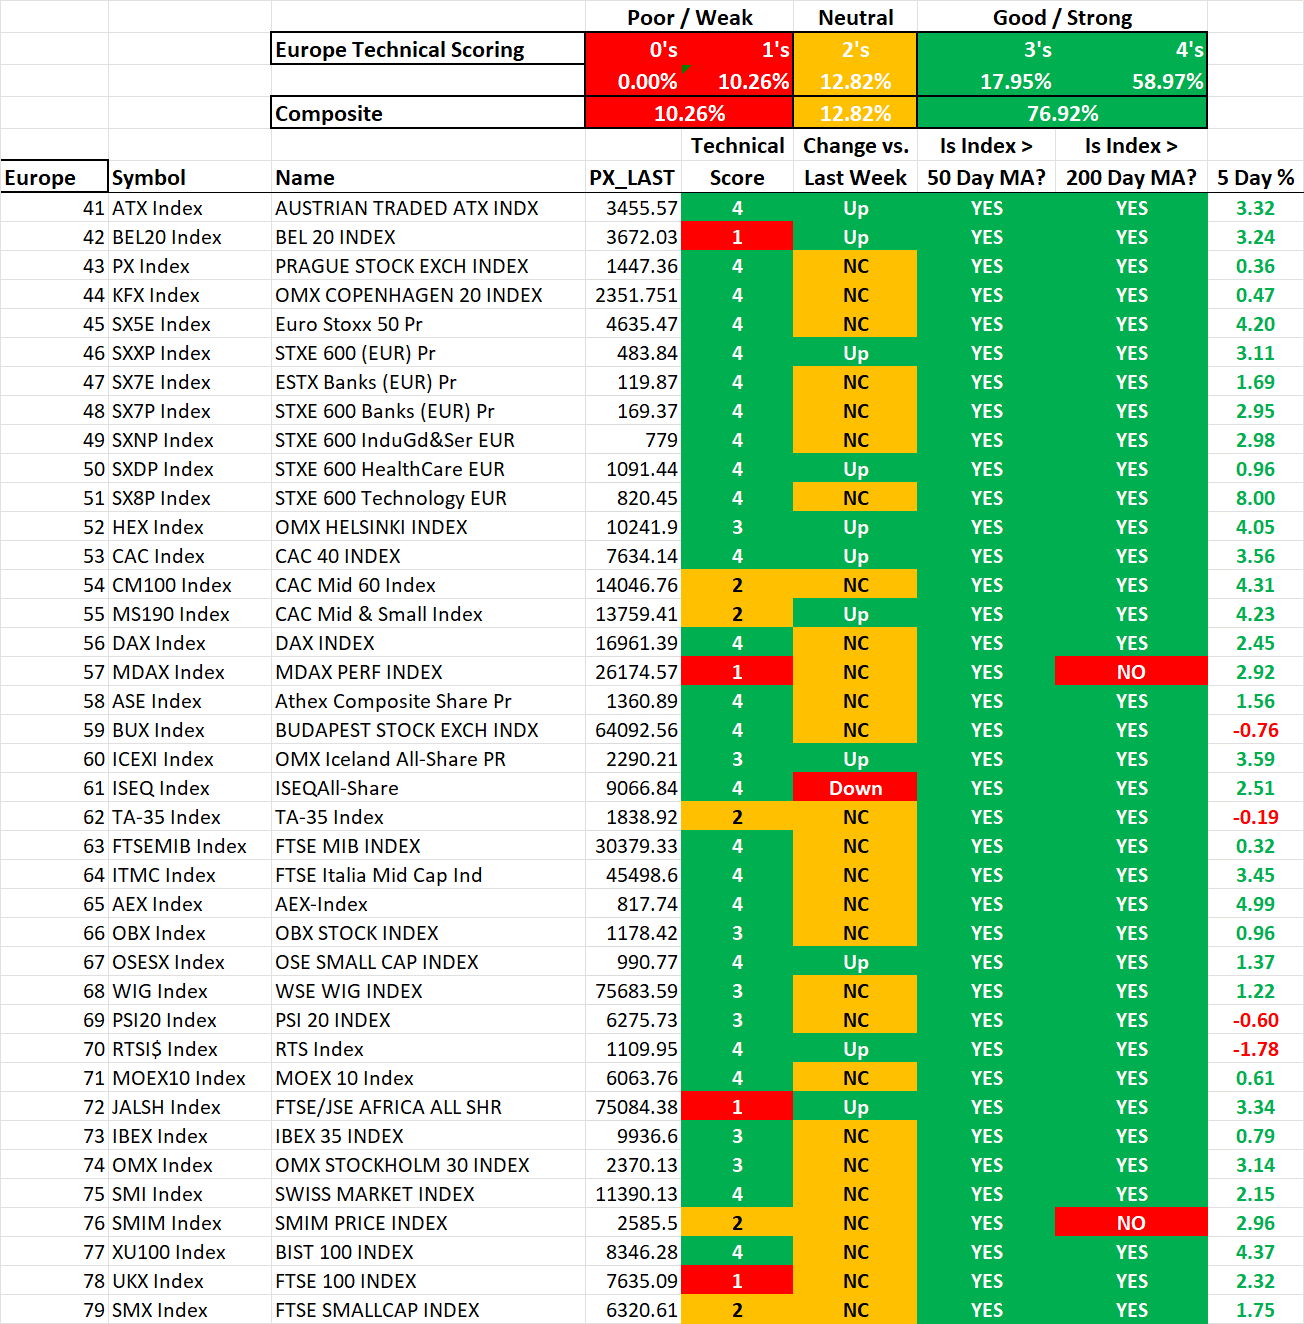
Please check the table below for a glance at the Technical Scoring results for European Equity Markets. The Composite Scores have 77% with Good / Strong Scores and only 10% with Weak Scores.
Source: 22V Research

