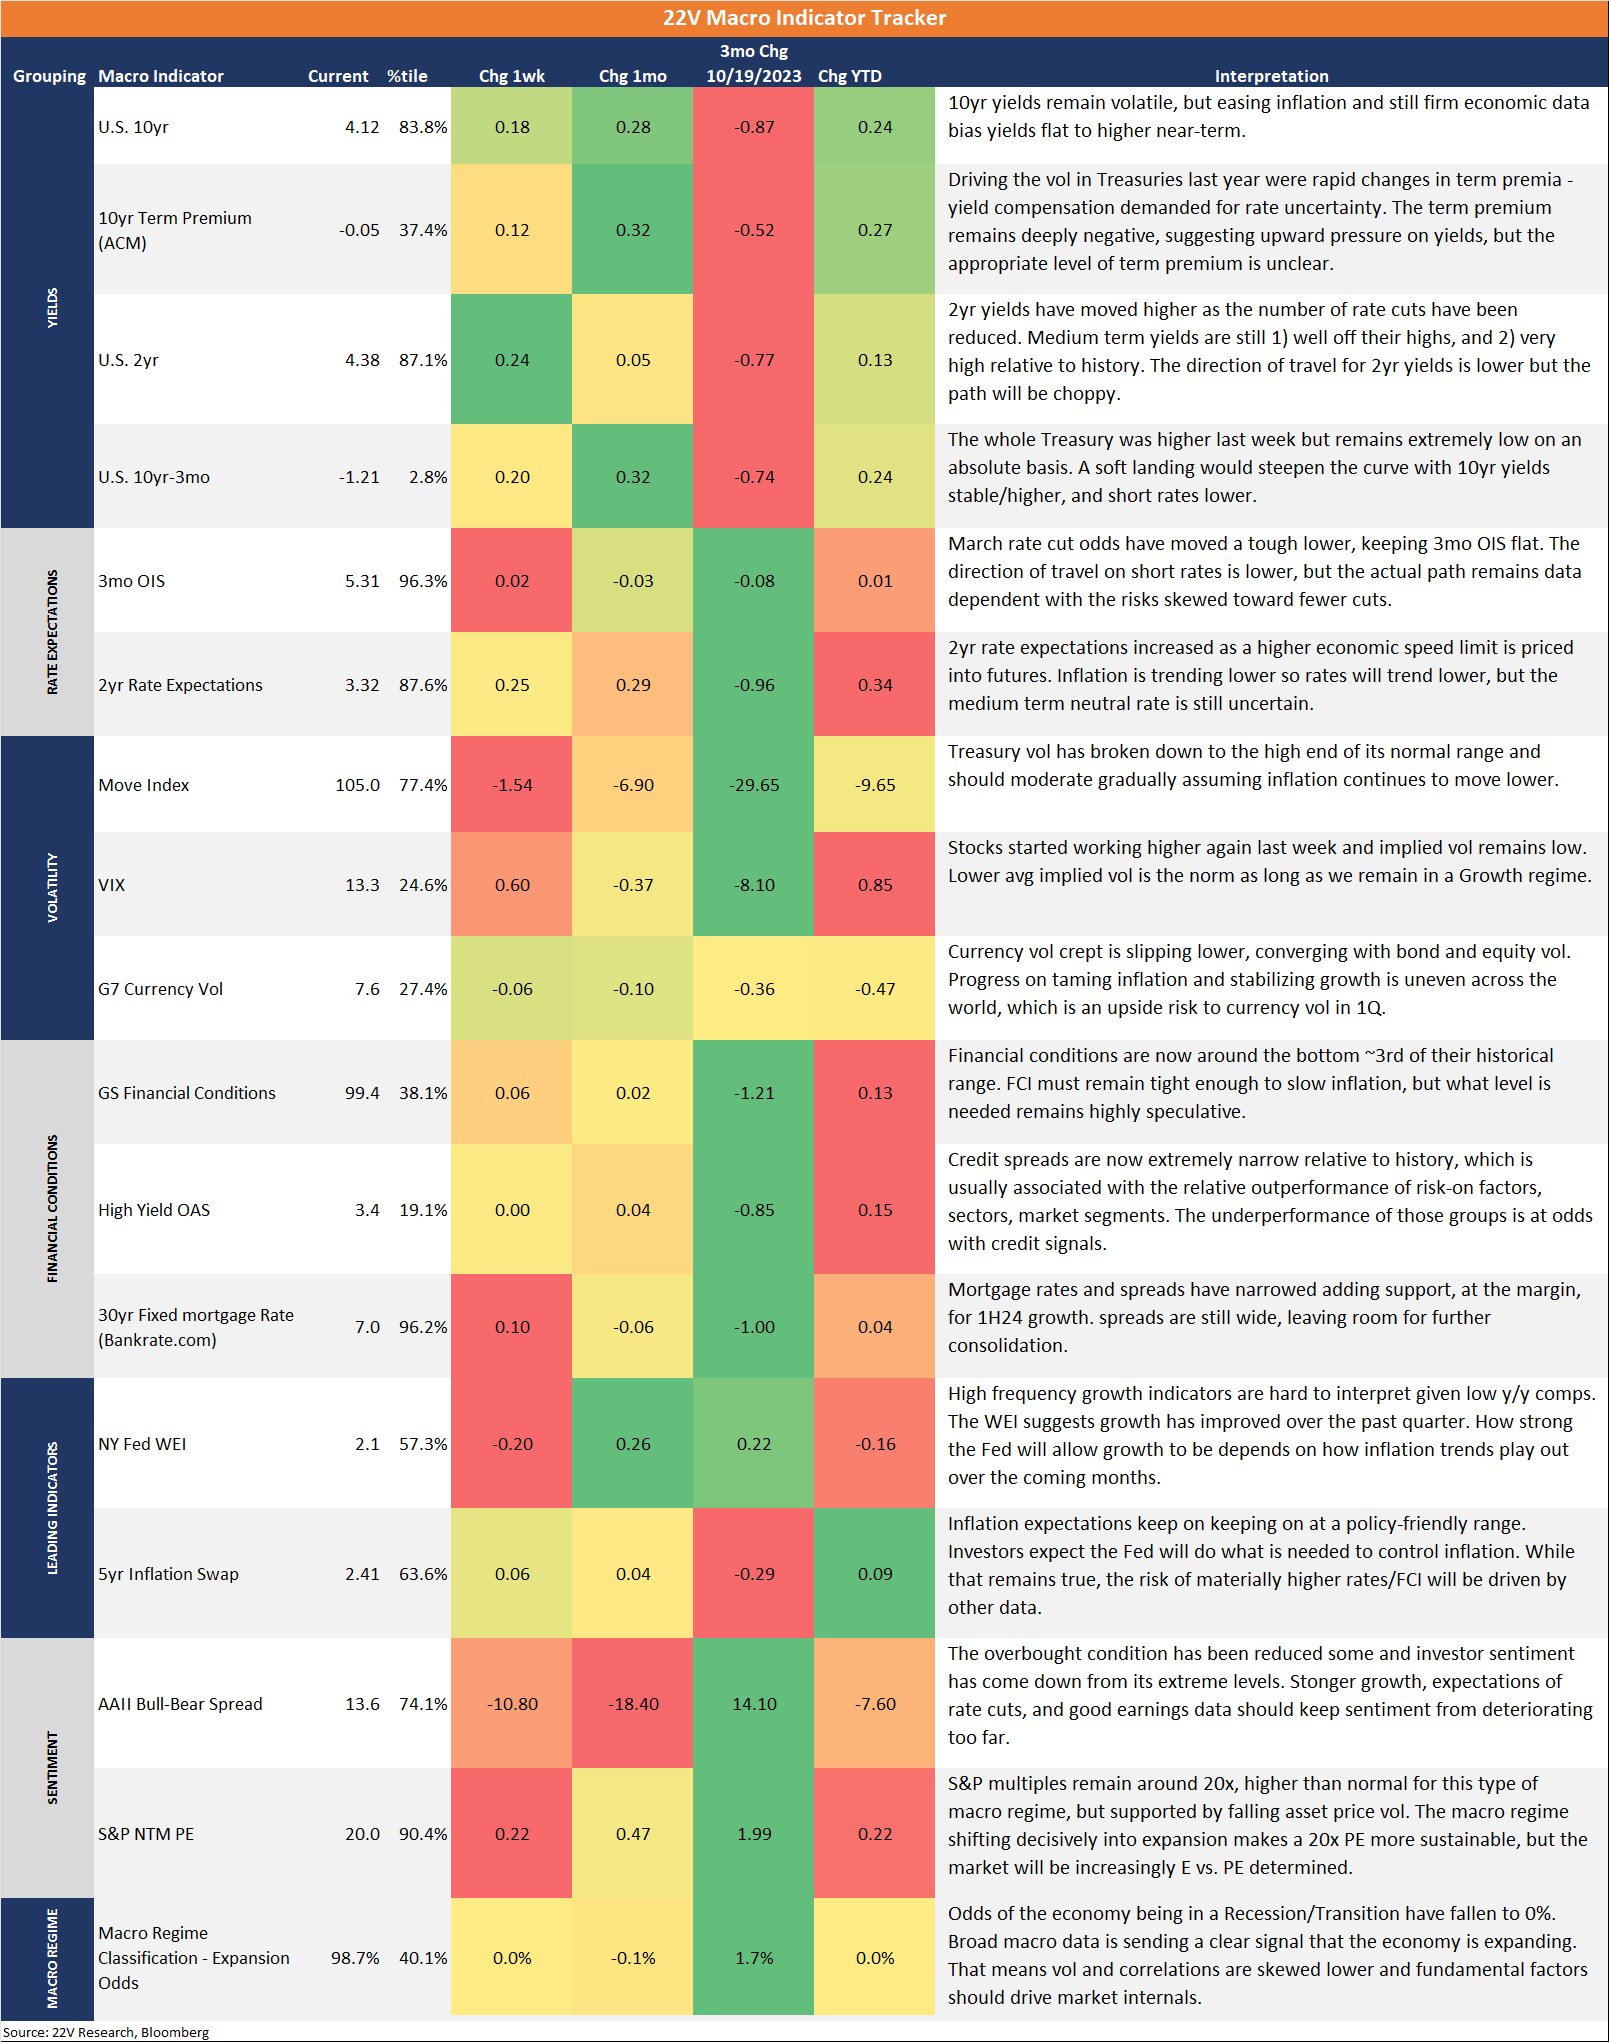
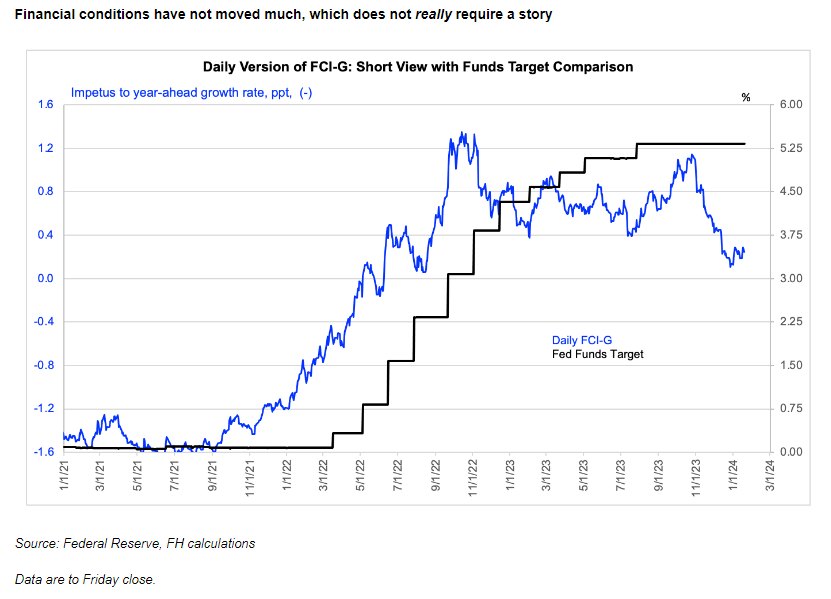
SUMMARY: The initial reaction to the repricing of rate cut expectations was to the underperformance of risk assets and a rotation into safe parts of equities (mega caps, Low Vol, etc.,). Gerard has been writing about how the Fed disappointing on rate cut expectations do not mean financial conditions need to tighten much. His note yesterday (HERE) documents how financial conditions have remained easy despite rate cuts being priced out over the past month. That is constructive for risk-on internals (risk-on factors, small caps, and Deep Cyclicals). The disconnect between rising yields, low credit spreads, low vol, and the broad risk-off move remains wide, suggesting upside to smaller caps, Value, risk-on factors.
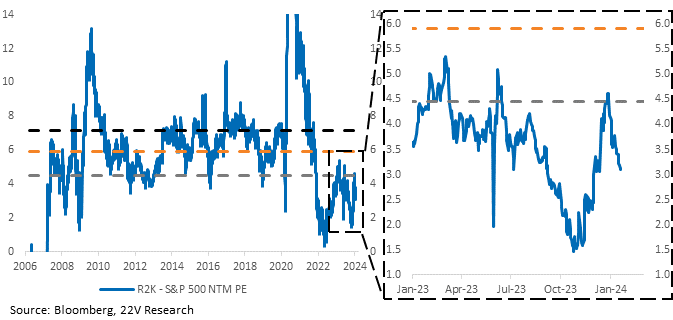
EXTREME VALUATION SPREADS: The NTM PE spread between the Russell and S&P is in its 13th percentile. The implied l-s return, on a pure valuation basis, back to the long-term median is +12.5%. FYI we are not anticipating the PE spread to move much wider given the Fed is likely unwilling to allow growth to accelerate too far above trend given the still sticky longer-term aspects of inflation. A return to the median PE spread between the R2K and S&P, under an economic Growth regime like the economy is currently in (HERE), is plausible.

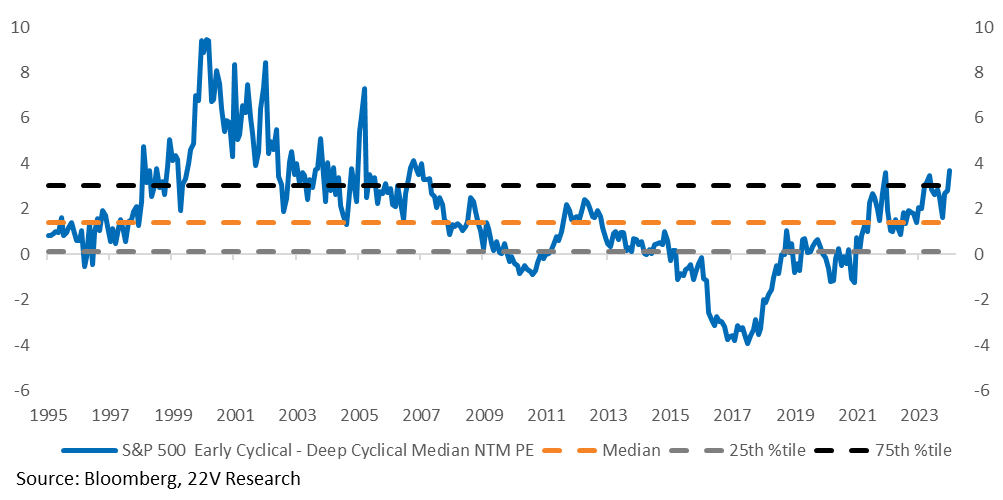
Spreads aren’t just wide between large and small caps. The recent outperformance of Early Cyclicals has brought the valuation spread between S&P Early Cyclicals (Tech, Comm Svcs, Discretionary) and Deep Cyclicals (Energy, Materials, and Industrials) to its 83rd percentile. Some normalization is plausible here too, though Deep Cyclicals rely on better RoW growth estimates too. Michael Hirson’s take that China will be hesitant to abandon its incremental stimulus approach is not a Deep Cyclical tailwind (more on that HERE). The bar is higher here vs small caps.
In the rest of the full report below, we update two important bits of market background. 1) implied rate vol has dropped to its 68th percentile, which is constructive to our risk-on call and 2) economic growth expectations still have not perked up, which we continue to wait on. Rate cuts being priced out without stronger growth estimates is not constructive to our risk-on call, but we expect growth estimates to firm. More details in the full report below…
MARKET VIEWS: Gerard has been writing about how the Fed disappointing on rate cut expectations do not mean much tighter financial conditions. His note yesterday (HERE) documents how financial conditions have remained easy despite rate cuts being priced out over the past month. That framework is constructive for risk-on internals (risk-on factors, small caps, and Deep Cyclicals).
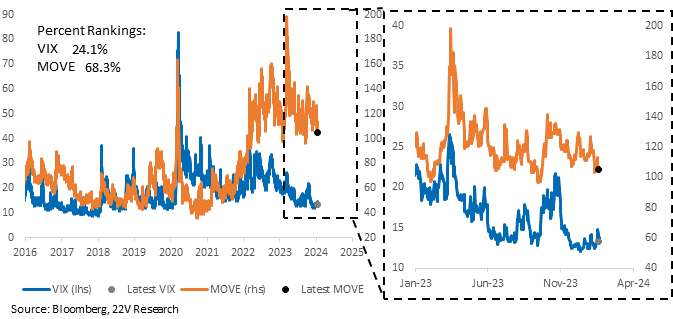
One tailwind and one stubborn headwind to the equity backdrop…
Implied rate vol has fallen from its 90th percentile at the beginning of January to its 68th percentile today. That implies less intensity around the rate path and/or data volatility. As rate vol continues to normalize relative to equity volatility, equity markets should reflect a more Normal economic backdrop, which should help extreme valuation spreads normalize. It seems likely that elevated implied rate vol was one reason small caps underperformed to start the year despite economic data indicating a firm growth environment without inflationary pressures.
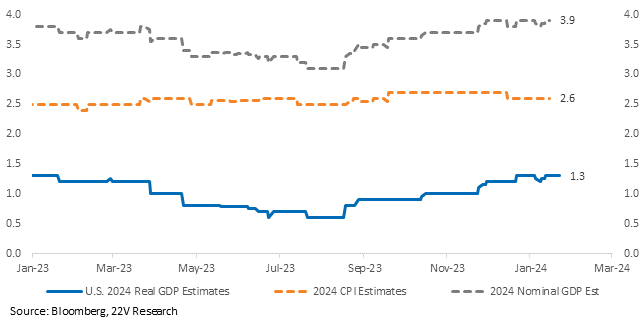
2024 growth estimates haven’t perked up, which we are still waiting on. This seems to be one of the reasons small caps continue to lag. Fewer rate cuts without better growth expectations is not constructive for risk-on internals. Given recent data, we expect growth expectations to level set higher, not risk-on factors, and small caps to level set lower.
EXTREME VALUATION SPREADS: The NTM PE spread between the Russell and S&P is in its 13th percentile. The implied l-s return, on a pure valuation basis, back to the long-term median is +12.5%. FYI we are not anticipating the spread move to its 75th percentile, given the Fed is not going to give the all-clear on growth longer-term. But the median valuation spread under an economic Growth regime, which the economy is currently in (HERE), is plausible.
Tech has started the year as the best performing sector, again. The recent outperformance of Early Cyclicals has brought the valuation spread between S&P Early Cyclicals (Tech, Comm Svcs, Discretionary) and Deep Cyclicals (Energy, Materials, and Industrials) to its 83rd percentile. Some normalization is plausible here too, though Deep Cyclicals rely on better growth estimates RoW too. Michael Hirson’s take that China will be hesitant to abandon its incremental stimulus approach is not a tailwind to Deep Cyclicals (more on that HERE). The bar is higher here vs small caps.
MACRO TRACKER: Macro data kept telling a better growth story last week, and equity markets/internals started listening toward the end of the week. The whole Treasury curve (10yr-3mo) steepened last week, Treasury vol eased, financial conditions remained stable at a low level, and credit spreads remained tight. At the same time, companies generally reported better than expected earnings, and the season-to-date beat rate is running ~86%. It is still early in reporting, but estimate revisions have rebounded, and earnings sentiment, though lower, remains high. The bottom line is that macro data is consistent with an upward revisions to near-term GDP estimates and management sentiment toward macro risk has improved. The disconnect between rising yields, low credit spreads, low vol, and the broad risk-off move remains wide, suggesting upside to smaller caps, Value, risk-on factors. Momentum has been the largest contributor to internals YTD and is at risk in the near term if the risk-off mood reverses. Lower Quality, higher vol SMID would benefit from risk-on reversal.