SUMMARY: The CEO of Homebuilder Lennar (LEN), Stuart Miller, noted that “As consumers have come to accept a ‘new normal’ range for interest rates, demand has accelerated, leaving the market to reconcile the chronic supply shortage derived from over a decade of production deficits,”. What the LEN CEO is saying has shown up in the data recently as hard housing data have stabilized around their 50th %tile level historically.
The LEN CEO comments conform to our view that 1) most of the impact from the initial tightening of financial conditions has been felt (peak housing drag was 3Q/4Q last year. 2) equilibrium interest rates are higher (see our higher R* report from earlier this week HERE) as nominal GDP can stay well above post-GFC levels. Greater nominal activity is thanks to higher debt to GDP levels, strong wealth effects, and lower private savings rates. A recession can still happen, but recession risk comes mostly from the Fed having to become more hawkish.
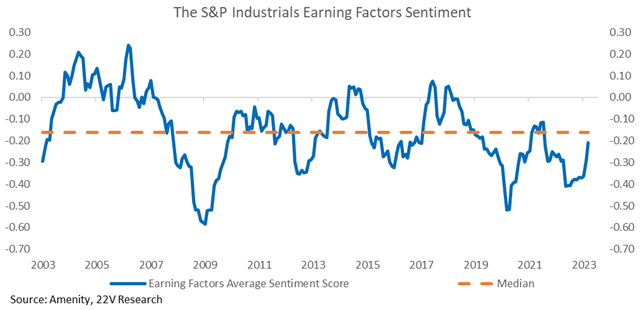
We were also forwarded comments from Honeywell (HON) management on the demand outlook improving, which would be consistent with our view of a bottoming in PMIs. Rather than just taking HON’s word for it though, and to avoid cherry-picking, we ran the Amenity natural language processing engine on earnings sentiment for Industrials. During the most recent earnings reporting season and in public comments since, management sentiment has rapidly improved. Industrials companies are sounding more positive when they talk on conference calls, at conferences, in public etc., The net of all the above is to be long Deep Cyclicals (Energy, Industrials, Materials) and stocks that benefit from destocking headwinds fading (retail and trucking, goods shippers). Other Cyclicals can work as well, and Defensives are a relative short.

Long FCX Trade Idea: Based on China stimulus plans that should reduce the left tail risk for commodities, the potential for a more stable copper curve that would reduce cash flow tail risk for commodity-sensitive companies like FCX (thanks to Colin Fenton for pointing out this idea. The implication is the stock can do much better than the commodity) and some technical work from John Roque, we propose a short-term long FCX options trade today. Details below.
Full report below…
MARKET VIEWS: Cyclicals continue to march higher relative to Defensives as investors discount lower near-term recession risk and focus on the potential reacceleration in parts of the economy. Like housing investment and production. On the housing side, the CEO of Homebuilder Lennar (LEN), Stuart Miller, noted that “As consumers have come to accept a ‘new normal’ range for interest rates, demand has accelerated, leaving the market to reconcile the chronic supply shortage derived from over a decade of production deficits,”. What the LEN CEO is saying has shown up in data recently as hard housing data has stabilized around its 50th %tile historically.
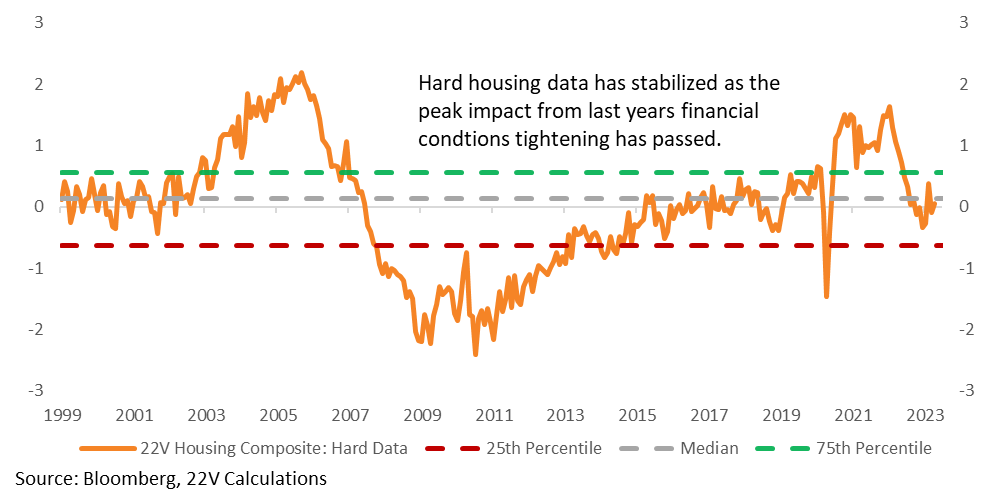
The LEN CEO comments conform to our view that 1) most of the impact from the initial tightening of financial conditions has been felt (peak housing drag was 3Q/4Q last year. 2) Equilibrium interest rates are higher (see our higher R* report from earlier this week HERE) as nominal GDP can stay well above post GFC levels assuming no recession. Recession risk will come mostly from the Fed having to remain more hawkish. As a reminder, nominal GDP can remove high and the US economy avoid a recession, despite 5% -5.5% Fed Funds given the high debt to GDP, strong wealth effect, and lower private savings rates. Forward outlooks in the Empire and Philly Fed have started to improve from unusually low levels.
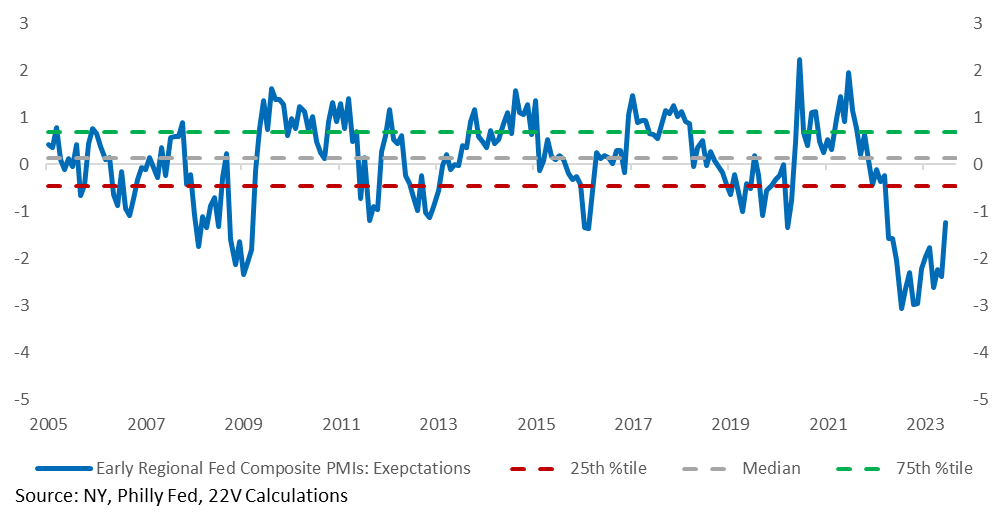
We were also forwarded comments from Honeywell (HON) management on the demand outlook improving, which would be consistent with a bottoming in PMIs and inventories adjusting. Rather than just take HON’s word for it though and to avoid cherry-picking, we ran the Amenity natural language processing engine on earnings sentiment for Industrials. Since this past April’s earnings season sentiment has improved. Industrials companies are sounding more positive when they talk at conferences, in public etc., this current quarter. The net of the above, we are long Deep Cyclicals (Energy, Industrials, Materials) and stocks that benefit from destocking being behind us (retail and trucking, goods shippers).
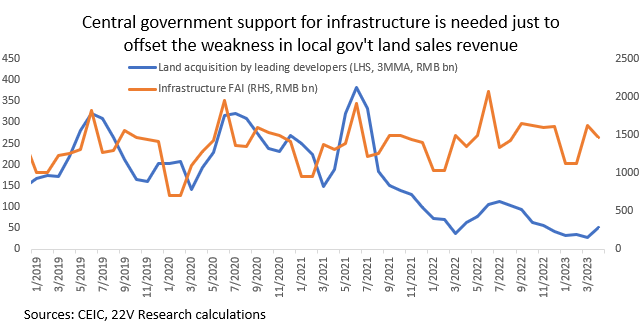
Long Copper: The Wall Street Journal had a report out yesterday that China’s central government is considering issuing special treasury bonds. Michael Hirson, head of 22V China research, thinks that (if the report is accurate) a large part of the stimulus will be to finance infrastructure projects. He notes that this support from the central government is essential to avoid infrastructure decelerating in H2, since local government revenues from land sales – a key source of infrastructure finance (see chart below) – are ailing due to property sector weakness. While such a move would be favorable for hard commodities, it would have limited effectiveness in boosting private sector investment and household confidence, which are key soft spots in China’s recovery. Think of the stimulus as helping reduce a left tail in commodity prices near-term.
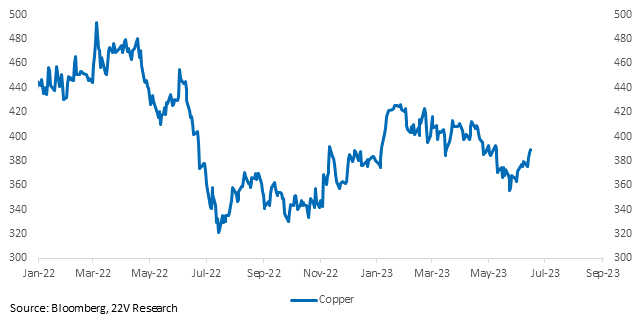
Copper has been trading in a range. Based on Michael’s work, it’s a good time to take a chance on a breakout. Colin Fenton, head of 22V Commodities research, prefers options that expire in July or August. If the forward copper curve is stable, and the odds of that increase if China is reducing the left tail risk in commodities, then FCX future cash flows will be more stable. That should benefit the stock even if the spot copper rate doesn’t accelerate much.
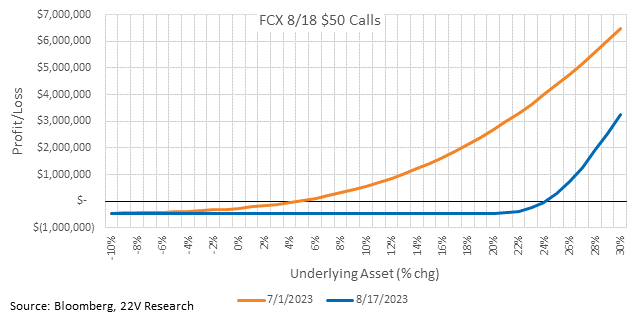
Options in Freeport-McMoran (FCX) are a good equity proxy. John Roque, 22V Technical Analyst, likes playing for a pop into the 50s. The FCX 8/18 $50 calls are trading around $0.25, a cheap way to play for a home run. That’s up 25% from here, but FCX has already had three 20%+ rallies and two 20%- drops this year. Returns are mocked up below.