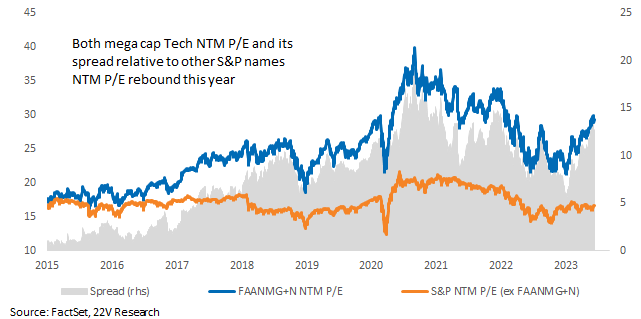
SUMMARY: Mega caps (MAANG+NVDA) lost -1.3% collectively last week, even as the rest of the S&P gained 98bp. The average stock was left out of the recent rally and is starting to catch up as soft-landing odds increase. NTM P/E for mega-cap Tech declined slightly last week but remains above its 80th %tile. The multiple spread relative to other S&P stocks is in its 88th %tile. We continue to expect consolidation of Megas relative to small caps for the next month or so.
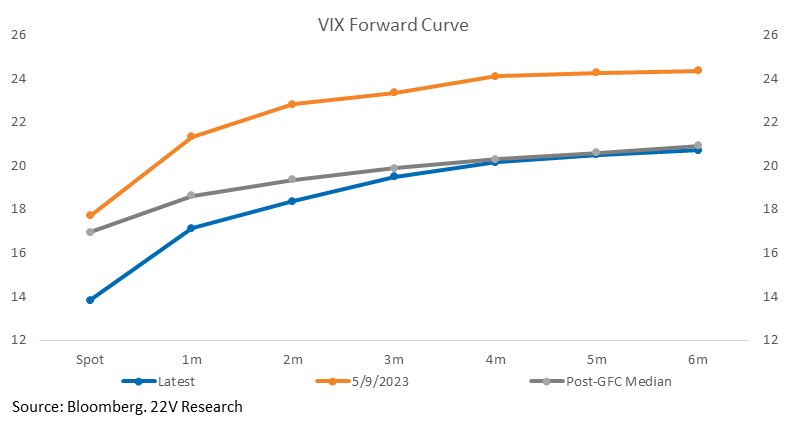
At the factor level, investors have been pushing Value and Earnings Turbulence names higher at the expense of Low Vol and Quality stocks. High Momentum names are also beginning to lag after posting a 98th %tile gain in May. The obvious risk this week is a strong CPI and a Fed that signals MORE urgency to slow economic growth. If that happens, financial conditions will tighten and front-month volatility should spike higher (spot VIX currently 14.5, implying 0.9% daily moves).
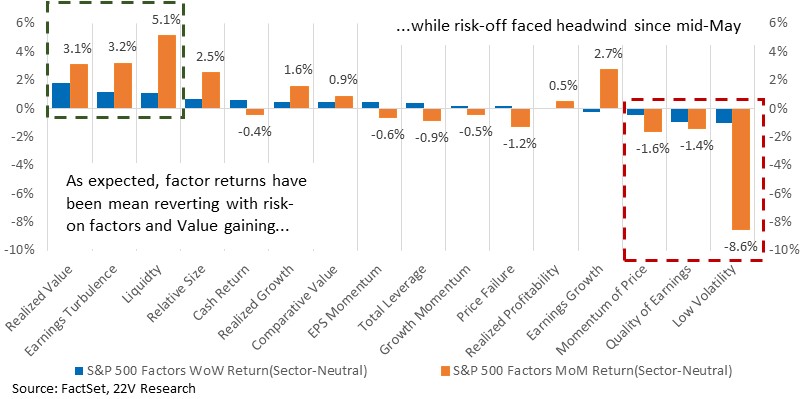
We expect the Fed to pause but retain its tightening bias. Some increase in the 2023 expected fed funds rate, from the Summary of Economic Projections (SEP) is possible. We don’t expect Powell to offer firm guidance at the July meeting. They are data-dependent, and we have another Payroll report and CPI before the July 26th meeting. Don’t expect much guidance for the rest of the year. The bottom line is don’t expect financial conditions to change much, which will keep PE in its current range and risk-on factors should continue to work higher. That means Realized Value, Earnings Turbulence, and Liquidity leadership at the expense of Low Volatility, Momentum, and Quality. That was the case last week and over the past month. Our Destocking Losers baskets are a favorite long idea as well (HERE).

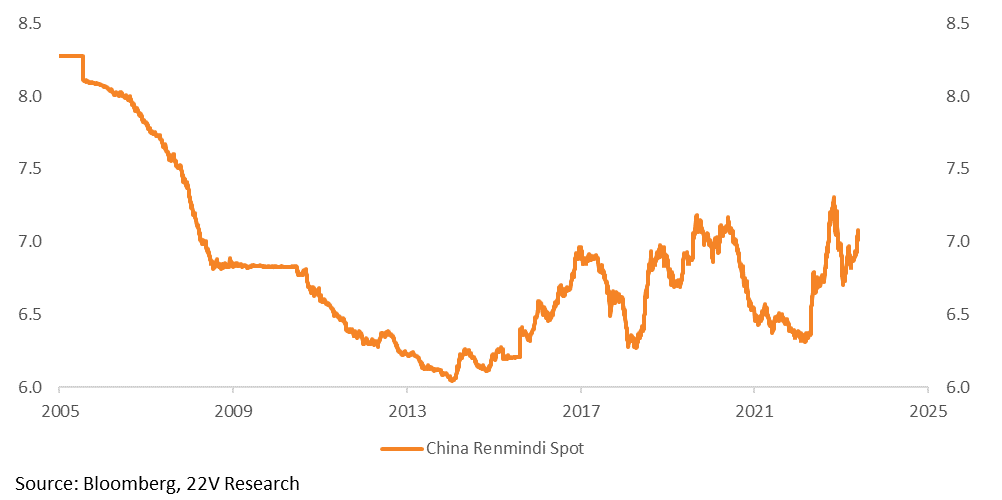
Oil Headwinds Not Helping: We also think Commodity Cyclicals should bounce, but the negative China growth narrative continues to get worse, and last week’s poor PPI data had the South China Morning Post talking about the dreaded D word (deflation) risk for China. The Chinese Yuan continues to move lower and a large stimulus is not on the table (Michael Hirson does not expect a large stimulus, HERE). Oil will likely struggle. Other risk-on factors can work well without oil moving higher (like retail, which we like near term). Just pointing out the specific China headwind.
As a reminder, Factor returns have been more mean reverting (consistent with transition periods, HERE) and since mid-May risk-on factors have led internals. Realized Value, Earnings Turbulence, and Liquidity took the leadership at the expense of Low Volatility, Momentum of Price, and Quality of Earnings over the past week as well as the past month.
Full report below…
MARKET VIEWS: Mega cap returns were volatile, but the broad market VIX closed Friday below 14, and small caps outperformed large by 12bps. Mega caps (MAANG+NVDA) lost -1.3% collectively last week, even as the rest of the S&P gained 98bp. The average stock was left out of the recent rally and is starting to catch up as soft-landing odds increase. The NTM P/E for mega-cap Tech names declined slightly but remains above its 80th %tile. The multiple spread relative to other S&P stocks is in its 88th %tile. Continue to expect consolidation of Mega caps relative to small caps for the next month or so.
At the factor level, investors have been pushing Value and Earnings Turbulence names higher at the expense of Low Vol and Quality stocks. High Momentum names are also beginning to lag after posting a 98th %tile gain in May. The obvious risk this week is a strong CPI and a Fed that signals MORE urgency to slow economic growth. If that happens, financial conditions will tighten, and front-month volatility should spike higher. Low Vol and risk-off factors in general would jump in that scenario. That would be a bad outcome for our mean reversion trade (long “destocking losers”, small caps, and deeper Cyclicals).
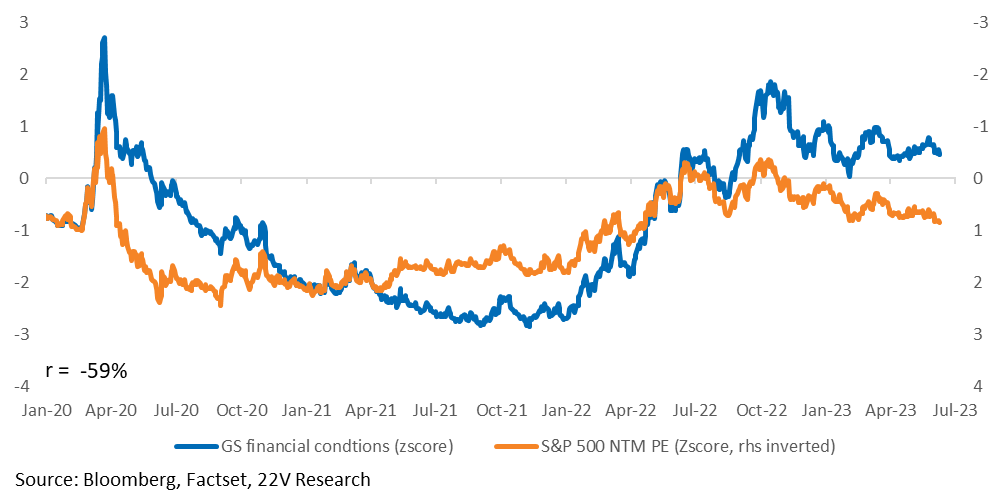
We expect the Fed to pause but retain a tightening bias. Some increase in the 2023 expected fed funds rate from the summary of economic projections (SEP) is possible. We don’t expect Powell to offer explicit guidance about the July meeting. Fed policy is data-dependent and there will be another payroll report and CPI release before the July 26th meeting. Do not expect much guidance about the rest of the year. FYI: Gerard estimates core services ex-rents are expected to be ABOUT 25 bps. That is his conclusion when looking at current consensus estimates. A June hike would be back on the table if this measure increases 40bp or more. Assuming that does not happen, don’t expect FCI to change much, which will keep PEs in their current range and risk-on factors should continue to work higher.
As A reminder, factor returns have been more mean reverting (consistent with transition periods (HERE) and since mid-May, risk-on factors have led internals. Realized Value, Earnings Turbulence, and Liquidity have taken leadership at the expense of Low Volatility, Momentum of Price, and Quality of Earnings over the past week and month. Near term, that trend will continue assuming recession risk remains low. Strong labor market readings (wages) or the Fed taking a more hawkish stance are the risks to ongoing risk-on outperformance.
Deeper Cyclical Worry: We also expect Deep Cyclicals (Energy, Industrials, Materials) to rebound relative to Early Cyclicals (Tech, Comms, Discretionary). The energy portion of that call is not being helped by Oil prices. The negative China growth narrative continues to get worse and last week poor PPI data had the South China Morning Post talking about the dreaded D word (deflation) risk for China. The Chinese Yuan continues to move lower and as long as that is the case, Oil will likely struggle.
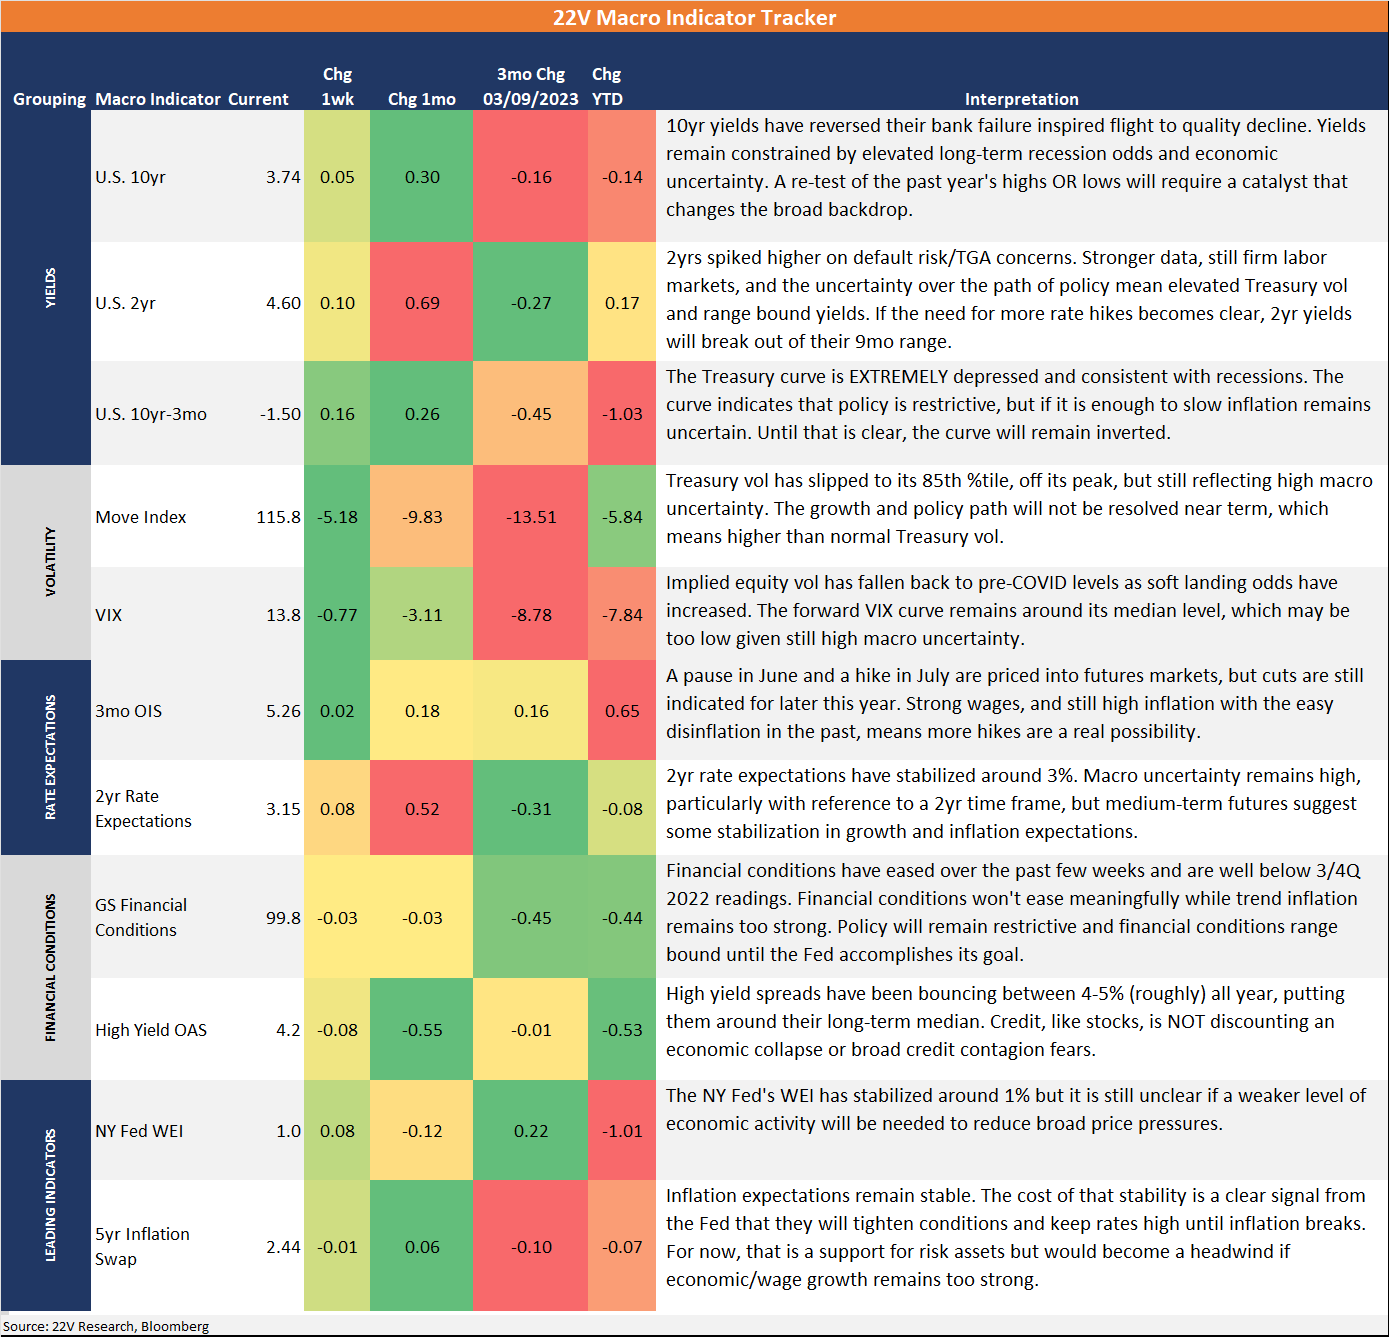
Macro Tracker: Market internals are catching up to the headline gains over the past few months. Mega cap returns were volatile, but the VIX closed below 14, and small caps outperformed large by 12bps. Mega caps (MAANG+NVDA) lost -1.27% collectively last week, even as the rest of the S&P gained 98bp. The average stock was left out of the recent rally and is starting to catch up as soft-landing odds increase. At the factor level, investors have been pushing Value and Earnings Turbulence names higher at the expense of Low Vol and Quality stocks. High Momentum names are also beginning to lag after posting a 98th %tile gain in May. The Style trade remains muddled as both Growth and Value rankings are strongly positively correlated with risk-on factors. Put simply, money flowing into risk-on ETFs/baskets is likely lifting Value and Growth as well. However, Value will likely keep outperforming as mega-cap Tech is predominantly Growth. This week, the Fed and CPI report can potentially be major market-moving events. Recession risk is largely a function of central bank policy, which is largely a result of inflation trends (direct and indirect). Slowing super core inflation and a signal from the Fed that they will remain on hold would mean higher soft-landing odds and be supportive of risk broadly. Higher inflation and more hawkish commentary from the Fed would mean higher vol, lower PEs, and general weakness in equities. Implied vol is low, especially relative to macro uncertainty. Markets are, in a sense, discounting further easing of uncertainty. As we cannot have a high conviction call on the direction of inflation, we are sticking to thematic trades that are more independent of broad market moves.