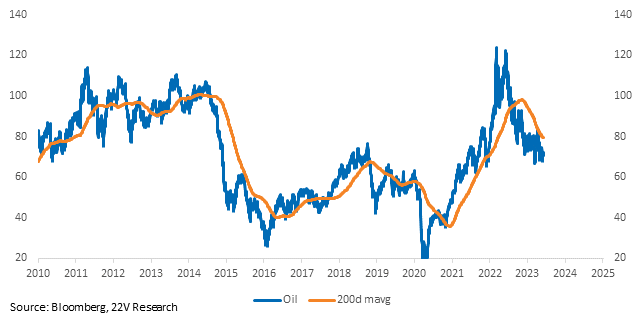
SUMMARY: Oil reversed its gain overnight. As 22V’s Commodity Head Colin Fenton cautioned after the OPEC+ “production cut”, enthusiasm would likely cool once the elements of the deal were more closely studied and more broadly understood. In short, the deal cut production targets but not actual production. See his report (HERE). We still think Deep Cyclicals (Energy, Industrials, Materials) can work over the course of June given low nearby recession risk and as industry group mean reversion plays out, but the oil price moves are not helping today.
Long Destocking Losers (XRT/IYT if you use ETFs): Yesterday we talked about how the “destocking losers” XRT and IYT stand to benefit from lower near-term recession risk (HERE). 1Q GDP data suggested inventories have probably over-corrected (HERE) and that has likely continued in 2Q (see the ISM new orders, production, and inventory sub-components). With an ok economy and strong labor markets, the destocking headwind should fade. Inventory sentiment, which is an objective score of how optimistic or pessimistic management teams sound about their inventory levels/outlooks based on the Amenity natural language processor, for the members of XRT has increased. In short, what companies are saying about inventories, or the future of inventories, is much better. This is an aggregate measure and will likely be surprising to most people. It was to us.
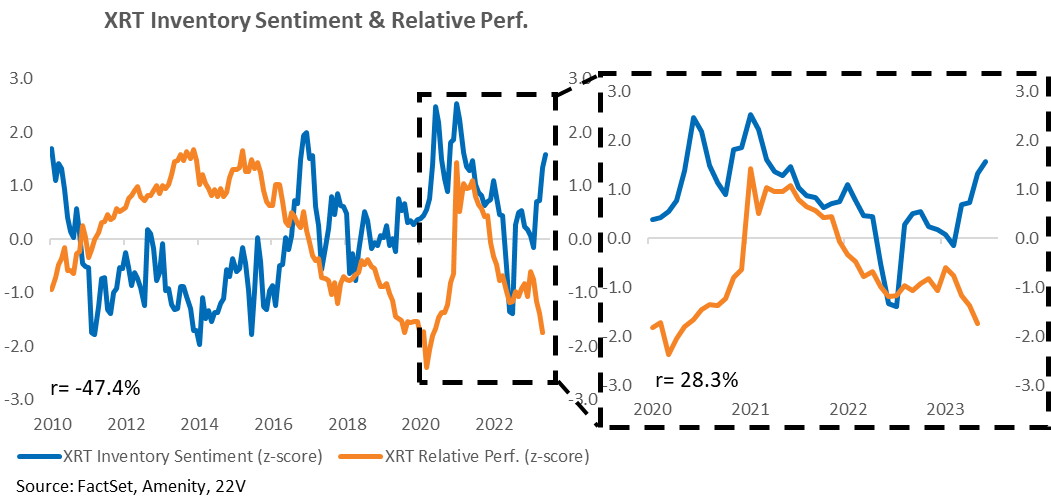
The above being said, Inventory sentiment is NOT well correlated with equity returns as fluctuations are not always important and other factors contribute more to changes in the attractiveness of Retail names. Over the past few quarters, inventories were a broad concern given the rapid pace of rate hikes and the broad assumption that a near-term recession, potentially a deep one, was inevitable. With inventory concerns front and center for investors, the rebound in management sentiment is an important signal and one we don’t see being tracked/discounted by the market.
Also, if we isolate the post-COVID period when inventory concerns became a much bigger issue for companies, inventory sentiment and XRT relative performance moved together. That is why the increase in inventory sentiment is interesting to us now. Especially if personal consumption expenditure growth remains in the 2% range. This seems likely given labor market trends, net worth effects, and level of savings rates.

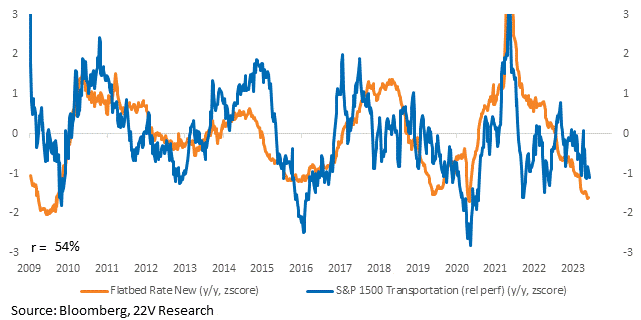
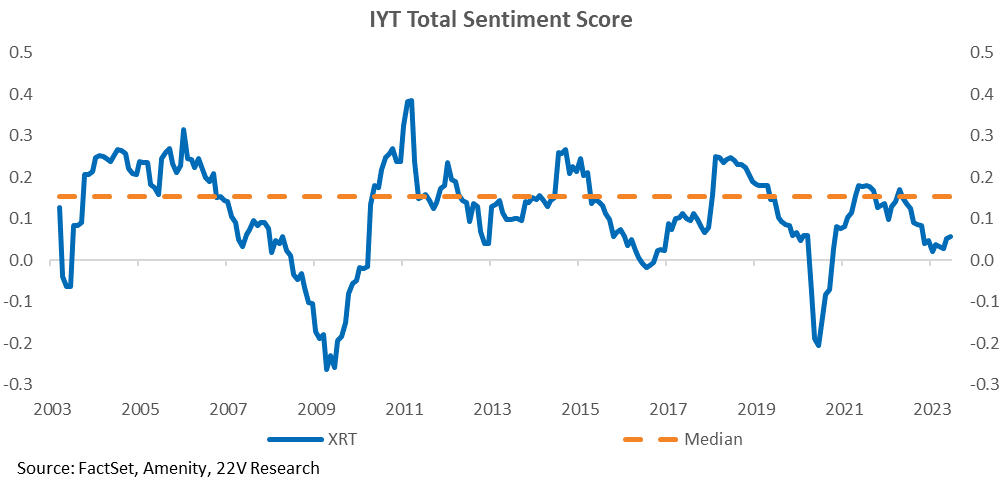
Total sentiment for the constituents of IYT is worse than the XRT but has bounced off its lows. Transports are a second-order beneficiary of destocking ending, so we aren’t surprised sentiment isn’t picking up on restocking, which has not happened yet. For the trucking names in particular, a bottoming out in flatbed freight rates would be an important signal.
Full report below…
MARKET VIEWS: Oil reversed its gain overnight following the brief pop after OPEC+ deal to cut production targets. Colin Fenton, 22V’s Commodities Head, had a note out yesterday (HERE) highlighting how the deal cut production targets but not actual production. On net, he thought oil futures prices may spurt higher in a knee-jerk reaction to the likely headlines of a “million-barrel cut”. However, he cautioned that enthusiasm would likely cool once the elements of the deal were more closely studied and understood. Headwinds to oil remain longer-term.
Long XRT and IYT: Yesterday we talked about how the “destocking losers” XRT and IYT stand to benefit from lower near-term recession risks (HERE). 1Q GDP data suggested inventories have probably over-corrected (HERE). With an ok economy, the destocking headwind should fade. Inventory sentiment, which is an objective score of how optimistic or pessimistic management teams sound about their inventory levels/outlooks based on the Amenity natural language processor, for the members of XRT has bounced.
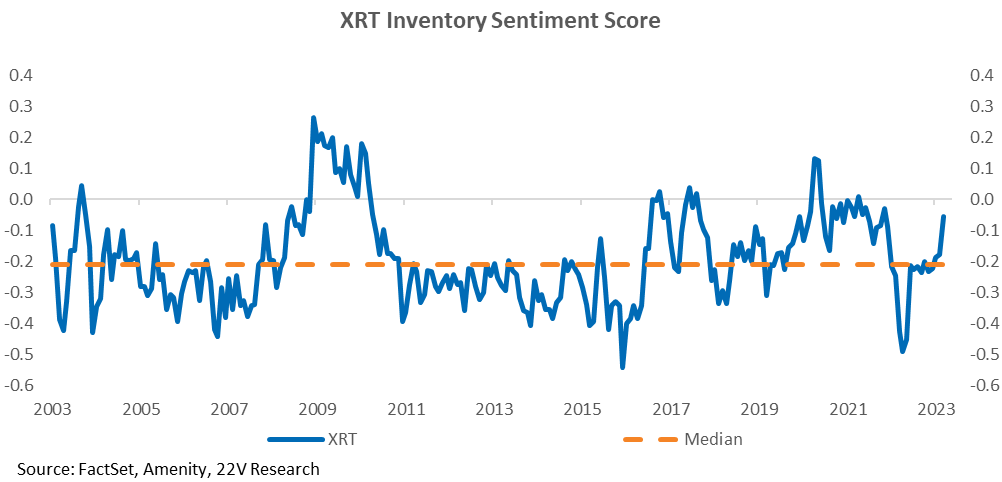
Inventory sentiment is not always correlated with equity performance. However, sentiment reflected the inventory concerns that were such a large headwind to XRT in 2021 and 2022. We think the rebound in sentiment is a meaningful tailwind.
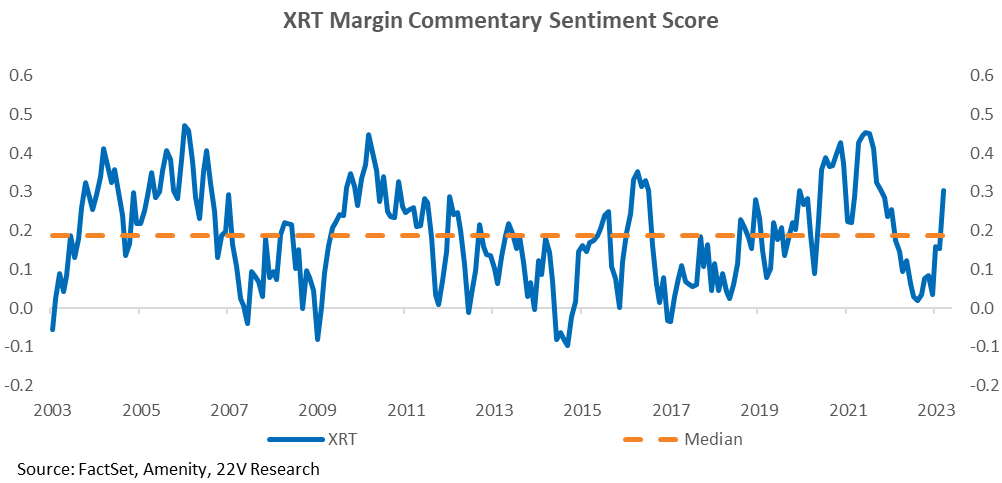
FYI the constituents of XRT have significantly better margin commentary sentiment as well.
Total sentiment for the constituents of IYT is worse than the XRT but has bounced off its lows. Transports are a second-order beneficiary of destocking ending, so we aren’t surprised sentiment isn’t picking up on restocking, which has not happened yet.
Flatbed freight rates are still low. We are watching this data point for improvement, which will feed into the equity performance of IYT.