Special thanks to Kim Wallace and Sandra Namoos, 22V’s Washington Policy team, for the assist on the debt ceiling commentary.
Quick summary of our survey results, investors:
- Think the S&P will fall from here, and 35% expect a new low (<3600).
- Expect the market to then rally into YE (median guess 8%), ending around 4000.
- Do not think the US will default.
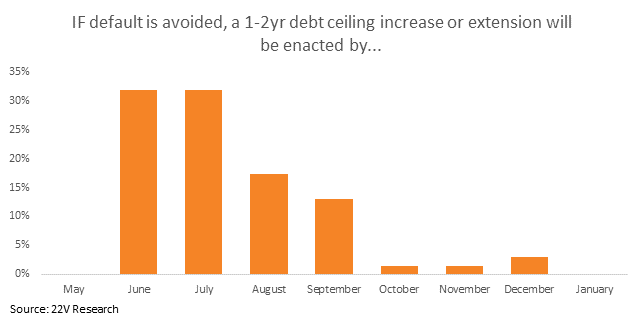
- Believe a 1-2yr debt resolution will be passed in the summer.
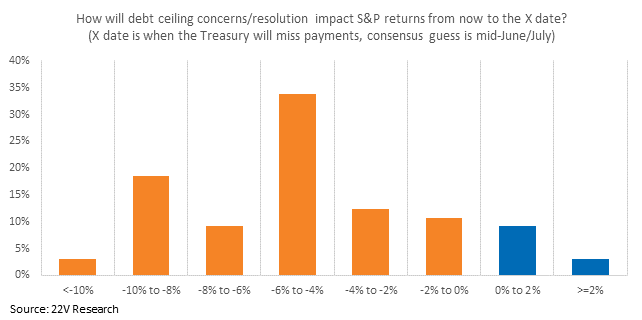
- Estimate the debt ceiling concerns will be a -5% drag on the S&P by the X-date.
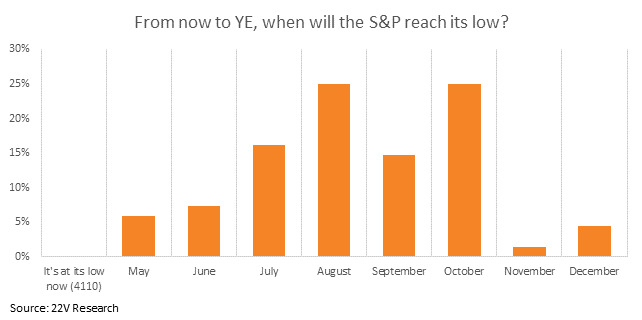
S&P Lows: Only 9% of the investors we polled think the S&P, from now to YE, will bottom above 4000. None think the bottom is in. All in, 41% expect a bottom above 3800 (low end of our fair value range), 65% see a bottom above 3600 (just above the 2022 low), and 35% think the index will hit a new cycle low by the end of the year. Median estimate is 3,675.

The perception of market risk picks up in July. Most investors (80%) think the bottom will be in 3Q or early 4Q…
… which is probably slightly ahead, timewise, of their recession expectations. The market does tend to bottom before economic growth bottoms.
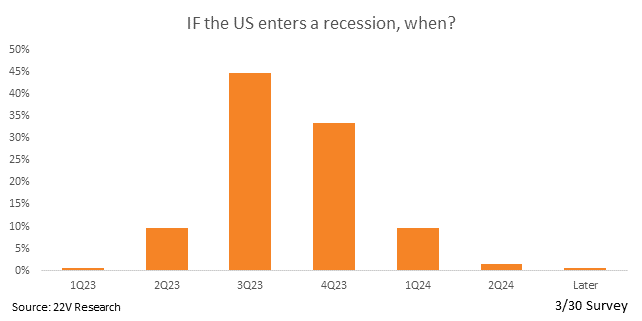
S&P YE Price Targets: The median year-end price target for the S&P is 4000, down -3% from current levels. There are clusters of responses around 3800 and 4200; all in 50% expect the S&P to end the year within our 3800-4200 fair value range. The tail is to the upside, with 31% expecting above 4200 and 22% expecting below 3800.
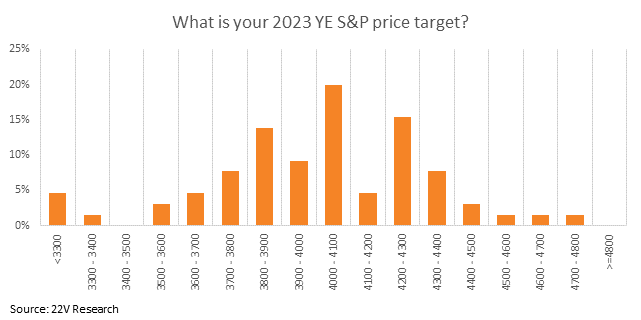
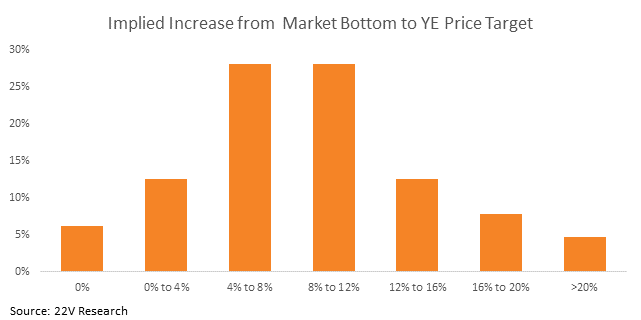
94% of our survey respondents have a YE price target higher than their expectations for the market low. The median implied rally is 8%. Again, the market tail is to the right.
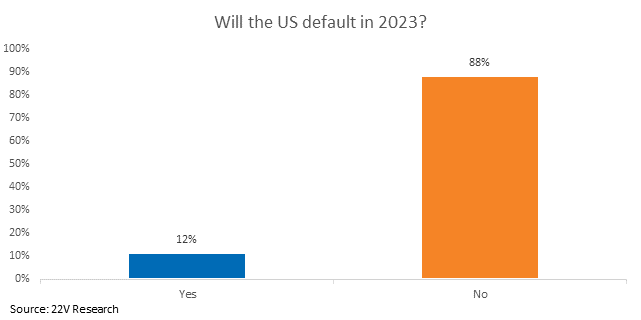
Debt Ceiling: In our survey, 88% of investors do not believe that the US will default in 2023. This lines up with 22V’s Washington team’s base case that the US will not default. As they’ve reiterated multiple times, there is no upside for either party in that outcome (HERE).
Interestingly, our survey shows the majority of investors appear optimistic that there will be a resolution to the debt ceiling this summer. While the Washington team expects Congress to pass a temporary suspension/extension of the debt limit ahead of the X-date (Treasury Secretary Yellen is expected to update Treasury’s June estimate shortly), Kim Wallace expects at least two short-term extensions/suspensions: one ahead of the summer X-date that goes to October 1, and another one while congress wraps up a year-end fiscal deal. The GOP House passage yesterday of its first debt ceiling proposal underscores Republican efforts to tie the debt ceiling to FY24 cuts in spending and the rollback of Biden administration priorities. This is just the start of a long and tortuous slog.
The median estimate of the debt ceiling impact on the S&P from now to the X-date is a -5% drag. 77% think the drag will be greater than -2%.