SUMMARY: Citizens Financial missed on deposits this morning. While bank earnings so far have not indicated trouble with deposits or a significant pullback in lending, most of the institutions that have reported were large and well diversified. There are lots of regionals left to report and still a lot of uncertainty around their numbers. We don’t have an edge on loan growth, but there will be winners and losers, which will create more dispersion and opportunity for stock picking.
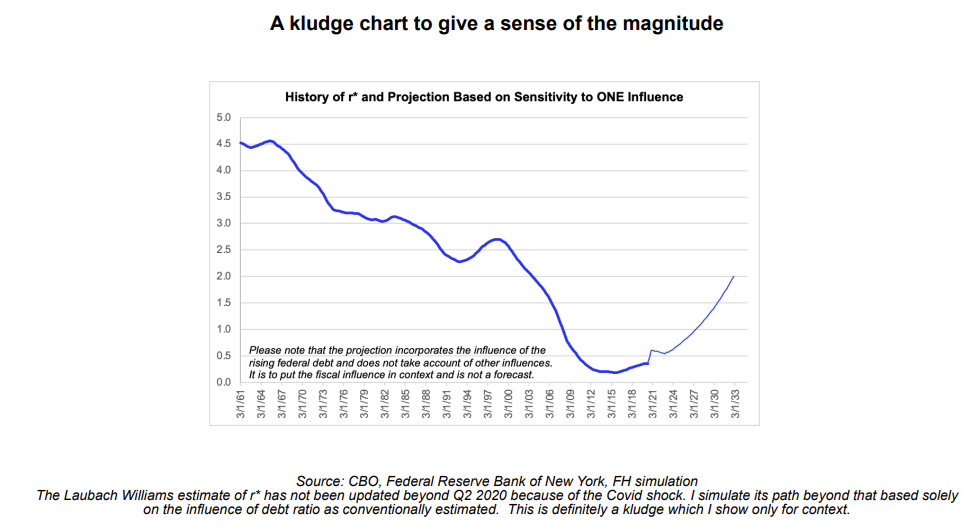
Yesterday, we talked about how economic data and declining systemic risk from banks bias US rates higher (HERE), and Gerard had a report out explaining how the neutral rate (the policy rate that is neither stimulative nor restrictive) has likely risen (HERE). Eurozone core inflation was flat at a high-level m/m and ECB chief economist Lane, formerly a dove, is calling for a period of below-trend growth to combat inflation. Global rates will probably be higher for longer, barring a collapse of economic data. Per the latest BofA survey, investors are record long bonds relative to stocks. The pain trade is bond yields and stocks moving higher.
Higher rates are a headwind to S&P fair value estimates, but that is offset by better earnings. Strong nominal growth is typically accompanied by strong earnings, as long as margins are stable. Margins are set to come down, but management sentiment, measured with the Amenity natural language processing tool, does not suggest a collapse. Again, we don’t think a deep recession is a given this year. We put +6mo recession odds at about 50/50.
And investors still expect poor earnings growth this year, with a median estimate of $207. However, management sentiment towards earnings has hooked up. There have been sentiment head fakes in the past, but generally sentiment firms ahead of a bottom in revisions. Continued improvement in management sentiment towards earnings would suggest earnings will beat investor expectations (though bbg consensus numbers still look too high).

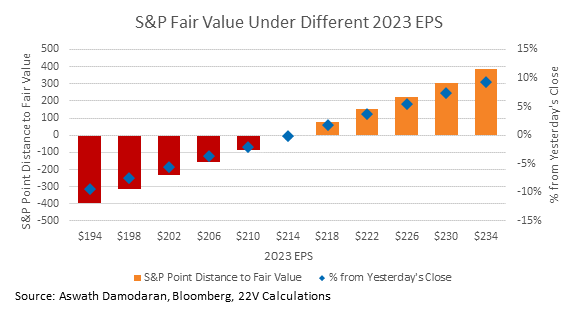
We estimate 2023 earnings at $214, which puts fair value right around current levels, and at about 130 points higher than fair value with EPS at $207.
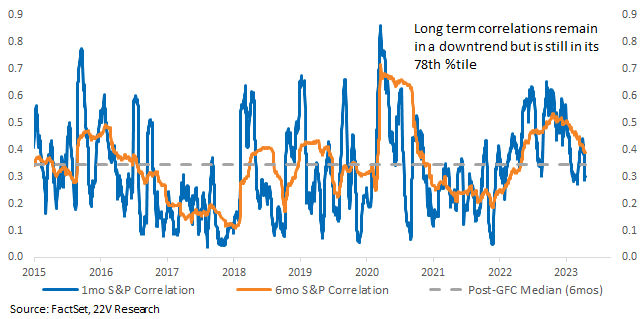
Fair value is still range-bound at approximately 3,800-4,200. There should be more dispersion in internals than gains at the index level. Intra-portfolio correlations are falling rapidly and should continue to do so during earnings season. Stock picking remains a better path to outperformance than market timing.
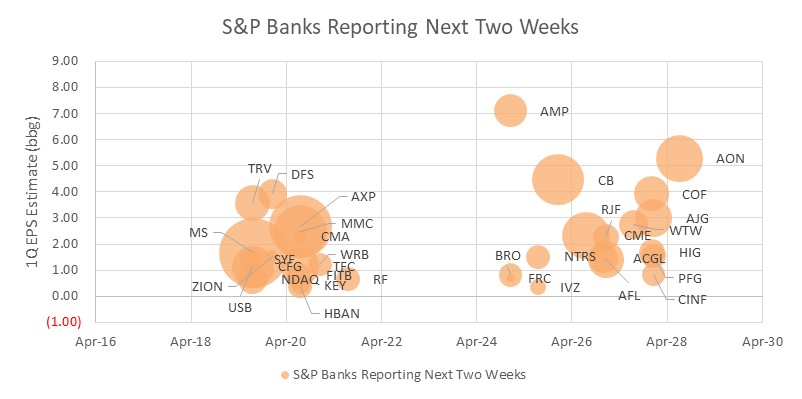
MARKET VIEWS: Citizens financial missed on deposits this morning ($172B vs $181B est). Over the next two weeks, another $1.2tril of banks and other financials will report earnings, including many regionals. Data so far hasn’t indicated trouble with deposits or a big pullback in lending, but most of the institutions that have reported were large and well diversified. A lot of uncertainty about the impact of bank failures/slowing growth remains. We don’t have an edge on the state of lending; our higher conviction take is we’ll end up with winners and losers, creating more dispersion and opportunity for stock picking.
Yields are higher globally this morning. UK core inflation was higher than expected. Eurozone core inflation was flat at a high level m/m. ECB chief economist Lane, formerly a dove, is calling for a period of below trend growth to combat inflation. Yesterday, we talked about how economic data and declining systemic risk from banks biases US rates higher (HERE), and Gerard had a report out explaining how the neutral rate (the policy rate that is neither stimulative nor restrictive) has risen (HERE). That means rates will probably be higher for longer, barring a collapse of economic data. Per the latest BofA survey, investors are record long bonds relative to stocks. That requires deep recession risk to be elevated short-term. The pain trade is bond yields and stocks higher.
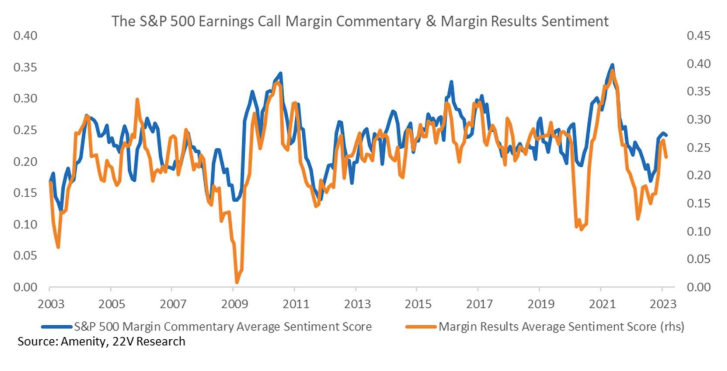
Higher rates reduce S&P fair value estimates, but that is offset by better earnings. Strong nominal growth is typically accompanied by strong earnings, as long as margins are stable. Like we covered in a quick 1Q earnings webinar yesterday (replay HERE), margins are set to come down but management sentiment, measured with the Amenity natural language processing tool, does not suggest margins will collapse. Again, we don’t think a deep recession is a given this year. We’ve got recession odds at ~50/50.
Investors expect poor earnings growth this year (median estimate at $207, HERE). Meanwhile, management sentiment towards earnings has hooked up. There have been sentiment head fakes in the past (sentiment improves but estimates remain in a downtrend), but generally sentiment firms AHEAD of a bottom in revisions (more details HERE).
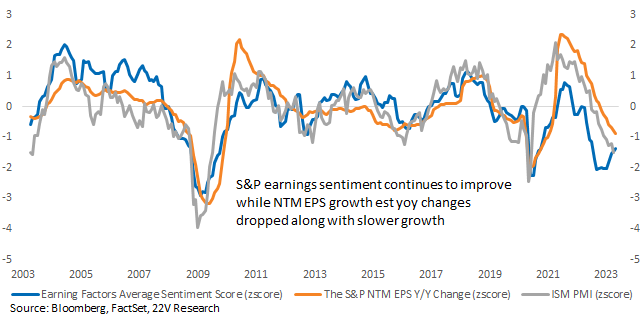
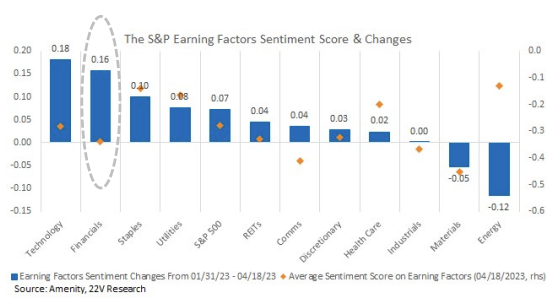
While still negative, the improvement in earnings sentiment is broad across sectors. Tech, Financials (yes, Financials), Staples, and Utilities have had the largest improvement (more HERE). Deep Cyclicals have fared the worst. Continued improvement in management sentiment towards earnings would suggest that investors’ poor expectations are unlikely to materialize.
We estimate 2023 earnings at $214, which puts fair value right around current levels, ~130 points higher than fair value with eps at $207.
The offsets of rates and earnings imply fair value is still rangebound from ~3800-4200. Going forward, there should be more dispersion in internals than movements at the index level. Intra-portfolio correlations are falling rapidly and should continue to do so during earnings season.