MACRO CONFERENCE TODAY: We are hosting our inaugural macro conference today via Zoom from 8:45 AM ET – 12:00 PM ET. We’ve got a great lineup of speakers covering everything from the Fed to supply chains to crypto. Agenda HERE and registration link HERE. Feel free to drop in for what’s interesting to you.
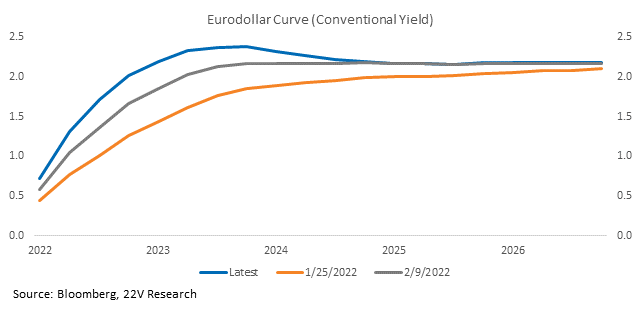
SUMMARY: The fed funds futures curve is inverted, which is consistent with bets of a quick and intense rate hike cycle. The high in the fed funds rate is around 2.5% in 2023, then cuts are priced in until roughly 2% by 2025. That means the terminal fed funds rate continues to be well anchored. Given current inflation expectations, the real fed funds rate would be negative longer-term if this scenario played out and yield curves would have a flattening bias. If the Fed doesn’t attempt to “reset expectations” and hammer home its desire to slow economic growth, financial conditions will not tighten since they already price in the rate hiking path. Financial conditions discount the Immaculate Tightening – inflation slows without the Fed having to tighten financial conditions significantly.
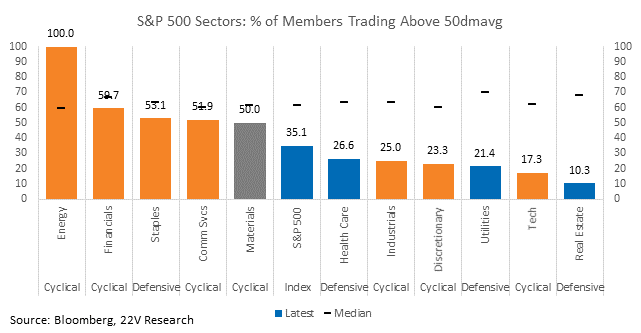
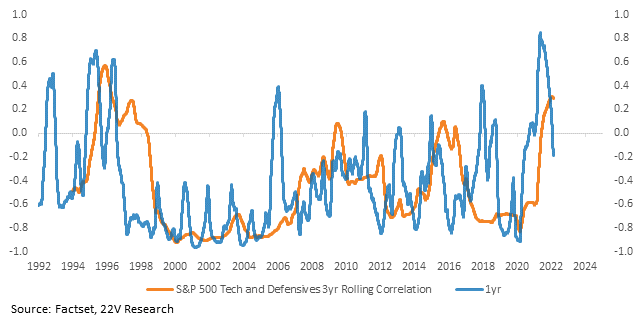
Short Term Yield Curve Flattening Implications: Flatter yield curves will benefit Tech stocks and be a headwind for Value. With 21% of Tech stocks trading above their 50-day moving average and yield curves flattening (WITHOUT a tightening in financial conditions), being short Tech is very tough right now. While Tech is oversold and benefits from a flatter yield curve, Energy and Financials are overbought. 100% of Energy stocks and 60% of Financials are trading above their 50-day moving average. Currently Energy (equally-weighted) is running at a +862% annualized relative outperformance vs the S&P and Financials at +185%, a thoroughly unsustainable rate. Cyclicals will continue to outperform until the Fed resets expectations, but Cyclical leadership can shift to Tech and Discretionary as Value reverts lower. Defensives lagged yesterday as 10yr yields increased. Also, keep in mind that Tech and Defensives generally have a negative correlation. The correlation was positive during the pandemic and is now reverting.

Longer Term Focus on Financial Conditions: The Fed could reset expectations for the terminal rate, which would alleviate some yield curve flattening pressure. With economic growth firm and core inflation a problem for the Fed, an anchored terminal rate and still easy financial conditions works against the Fed’s goals. Bottom line – don’t chase the market higher on the idea that flatter yield curves and easy financial conditions is the base case. Still flat yield curves and tighter financial conditions seems more likely.
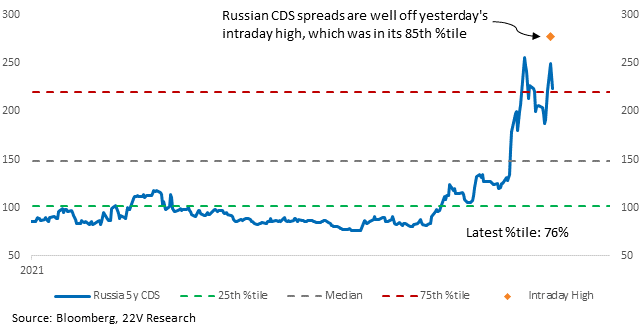
MARKET VIEWS: Risk assets are higher across the board as reports indicate that Russian troops are moving back to their regular bases and Russia’s top diplomat said diplomacy with the West could succeed. 10yr yields are back above 2% on the news and oil prices are off the highs. The Russian Ruble has moved back toward last Friday’s pre-escalation highs and Russian CDS spreads have tightened as well.
The fed funds futures curve is inverted, which is consistent with bets of a quick and intense rate hike cycle. Rate hikes are expected to stop with the fed funds rate around 2.5% in 2023, then the fed funds rate is expected to fall back down to roughly 2% by 2025. That means the terminal fed funds rate continues to be well anchored. Unless inflation expectations change, the real fed funds rate would be negative longer-term if this scenario played out and yield curves will continue to flatten. If the Fed doesn’t attempt to “reset expectations” about its desire to slow economic growth, financial conditions would not tighten much if what the forward market is pricing plays out (the Immaculate Tightening).
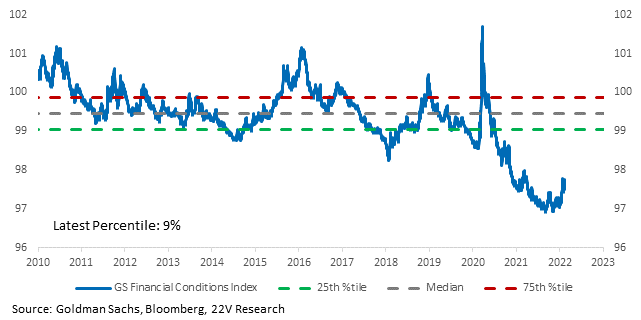
Financial conditions eased yesterday and remain near historically easy levels as yield curves have flattened. Again, that is consistent with the immaculate tightening theme (growth slows, inflation eases and the Fed tightens gradually without much impact on financial conditions) and, if it continues, will benefit Tech stocks and be a headwind for Value. With 21% of Tech stocks trading above their 50-day moving average and yield curves flattening (WITHOUT a tightening in financial conditions), being short Tech is very tough right now.
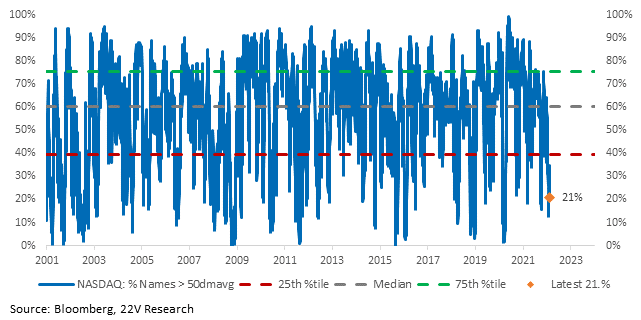
While Tech is oversold and benefits from a flatter yield curve, Energy and Financials are overbought. 100% of Energy stocks are trading above their 50-day moving average and 60% of Financials are. Currently Energy (equally-weighted) is annualizing at +862% relative outperformance vs the S&P and Financials at +185%. Cyclicals will continue to outperform until the Fed resets expectations, but Cyclical leadership can shift to Tech and Discretionary as Value reverts lower. Defensives lagged yesterday as 10yr yields increased.
Side note on Tech relative to Defensives – it is irregular for Tech to move with Defensives. Generally, the correlation is negative and sometimes, deeply negative. The correlation increased significantly post pandemic as UST yields collapsed and many Tech stocks benefited from work from home. The correlation is starting to decline again and that is likely to continue.
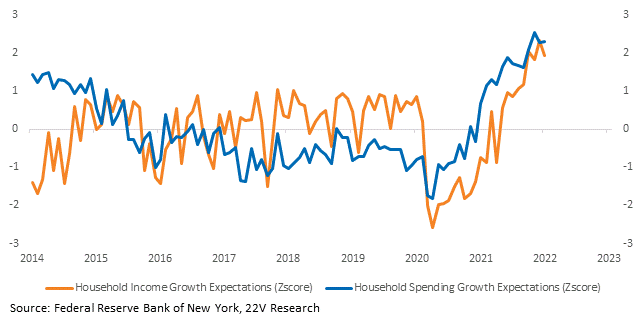
Quickly on what the Yield curve is signaling and how to think about it: First, demand growth is still strong and core inflation pressure exerts a hawkish influence on the Fed. Household income growth and spending growth expectations from the New York Fed survey yesterday points to robust demand growth. That is consistent with high frequency retail sales indicators, what retail companies have been reporting, what credit card companies have been reporting etc., Also, as DE Shaw has pointed out, the 10yr yields signal on economic growth has become much weaker. It is more of a hedging tool.
The terminal rate being pinned at 2% also anchors the 10yr. The Fed could reset expectations for the terminal rate, which would alleviate some yield curve flattening pressure. We are not making a prediction that they will, but we think it’s important to help everyone focus in on the terminal rate impact and the likelihood that it becomes a much bigger part of the discussion. Financial conditions are kept easy by firm growth and an anchored terminal rate and cuts priced in longer-term. The Fed knows this and if they want financial conditions to tighten, they will likely attempt to do something that alleviates an intense flattening of the yield curve.