
We are through the worst of the Omicron wave, so we are going to reduce the number of COVID reports we publish to 2 a week (Tuesday, Thursday). Daily updates are less useful today because uncertainty is declining and risks are fading. We will continue to provide updates on supply chains (the primary risk), labor shortages, restrictions (especially in China), and on whatever next captures headlines.
Our entire repository of COVID charts is HERE. FYI, we went over the U.S. in depth yesterday.
At the beginning of the Omicron wave, the range of possible hospitalizations was extremely wide based on different estimates of transmissibility, severity, length of wave, and length of stay. All the estimates were (at best) based on very early data. At worst, they were guesses. The term premium fell and equities briefly dropped. But compared to initial estimates, Omicron hospitalizations were tame. Reduced mobility (increased WFH, reduced travel) still caused a short-term decline in consumer spending that we expect to see reverse over the coming months. Another major wave would likely start the same – the unknown will be a headwind to 10yr yields and equities, especially COVID-sensitive industries. And, like at the beginning of Omicron, initial estimates of hospitalizations will not be very useful save to highlight the range of possible outcomes.

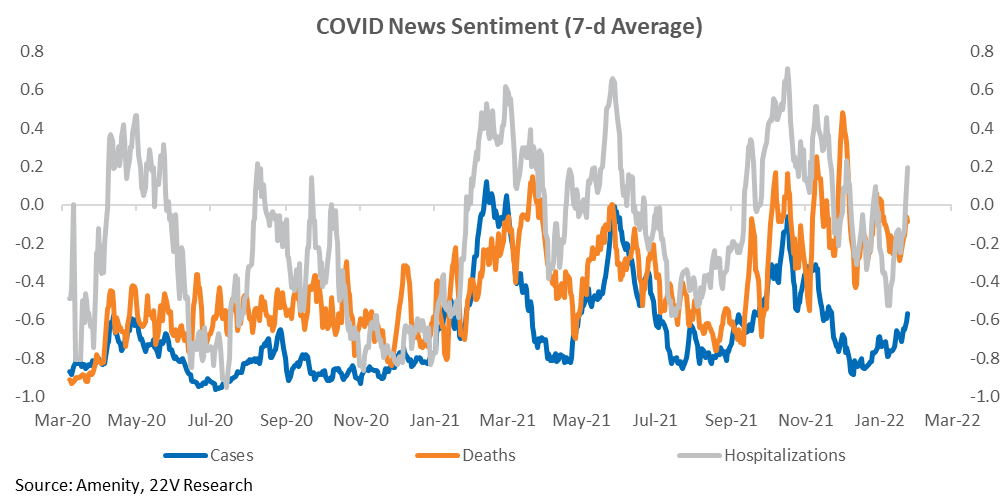
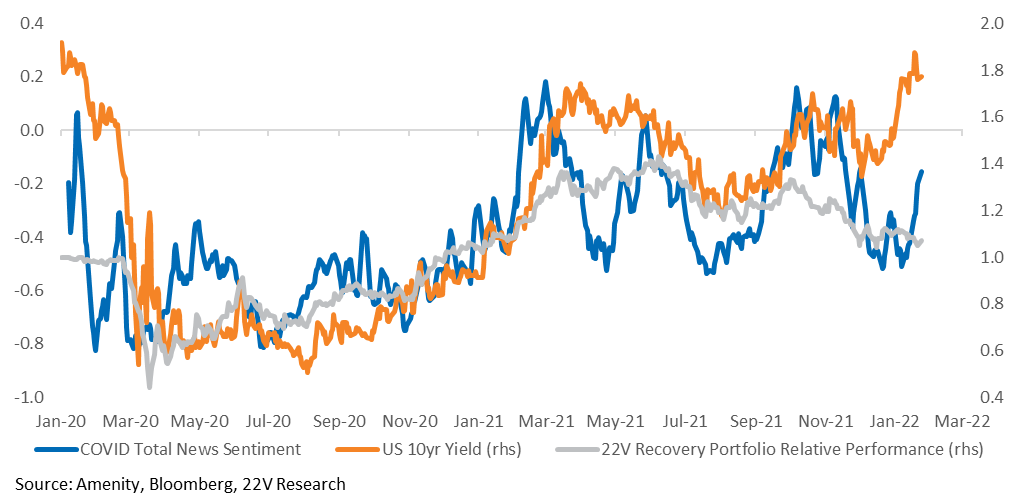
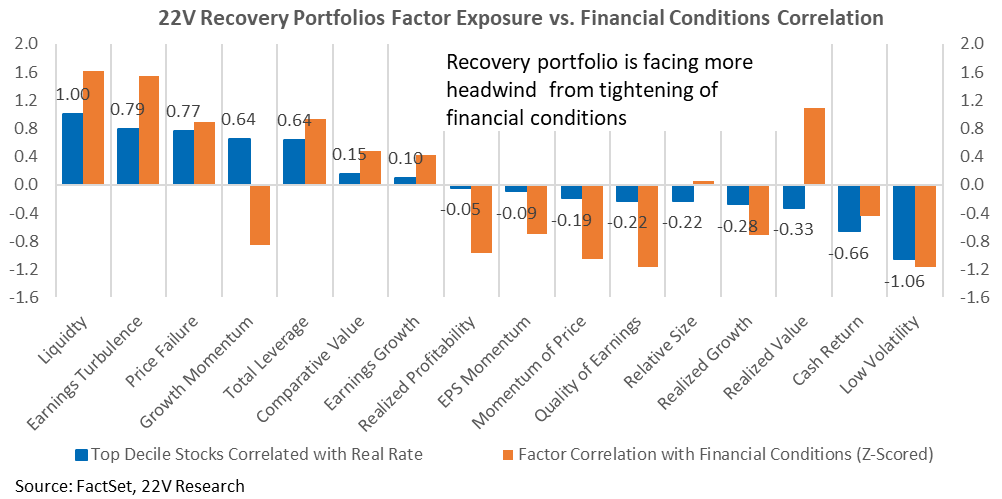
COVID sentiment is improving substantially across cases, deaths, and hospitalizations. Our Recovery Portfolio is not following; its factor exposure shows the portfolio is poorly positioned for tightening financial conditions and rising real rates.
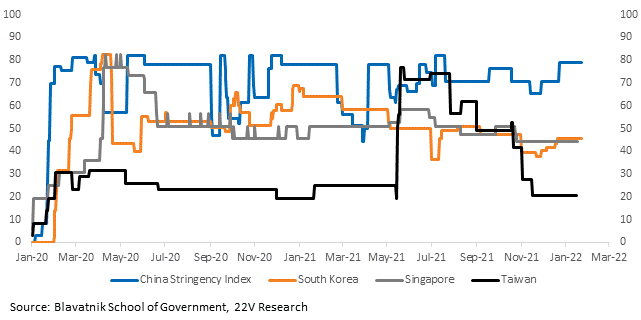
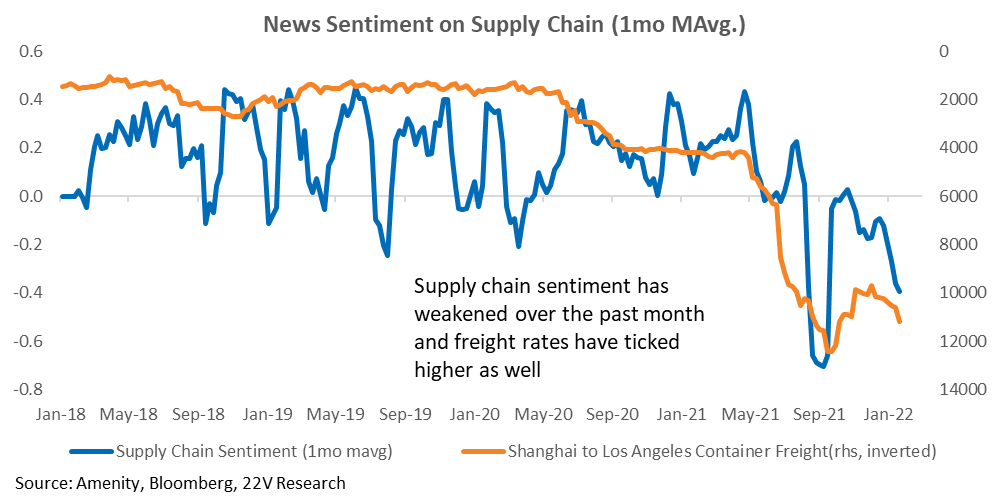
China has lifted its lockdown of Xi’an after a month but is increasing restrictions in Beijing ahead of the Olympics. COVID-zero still poses a threat to supply chains. The primary risk Omicron poses is widespread disruptions to supply chains that delay goods deflation at an inopportune time. Keep an eye on Oxford’s stringency indices to gauge restrictions, which are still easy (for now). Supply chain sentiment, calculated using the Amenity natural language processing tool, deteriorated again last week.
COVID trends in other supply chain countries are deteriorating. We will be monitoring whether restrictions and mobility follow.
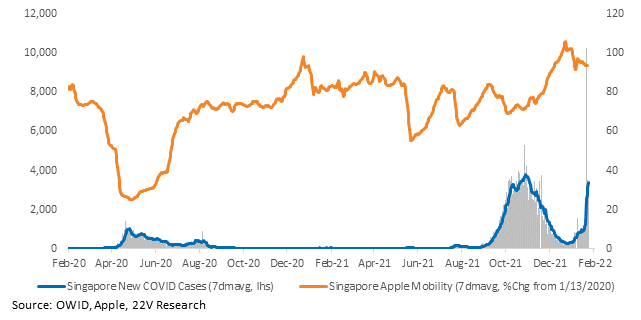
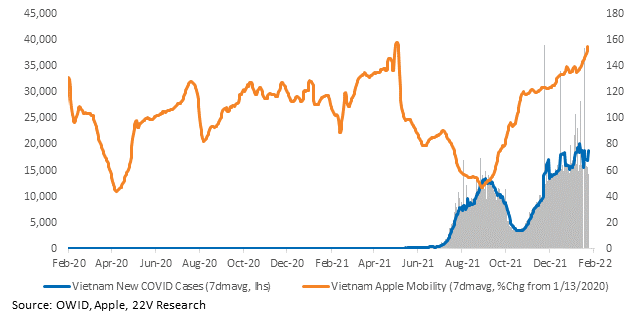
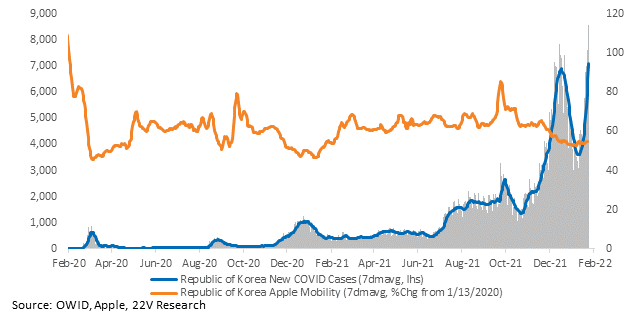
Charts for every state and country we have data for are HERE.

