
Our entire repository of COVID charts is HERE.
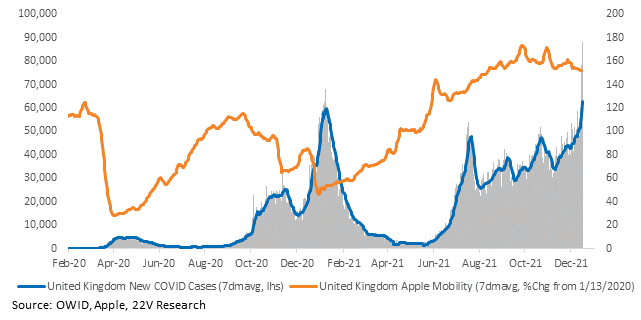
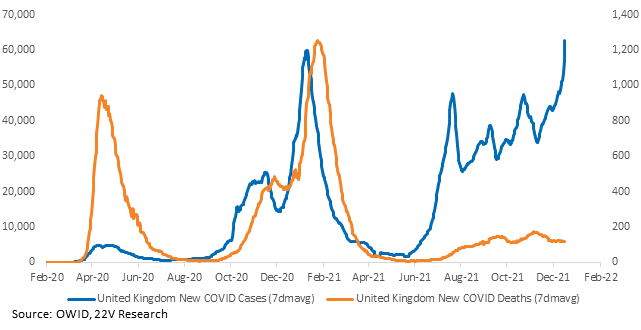
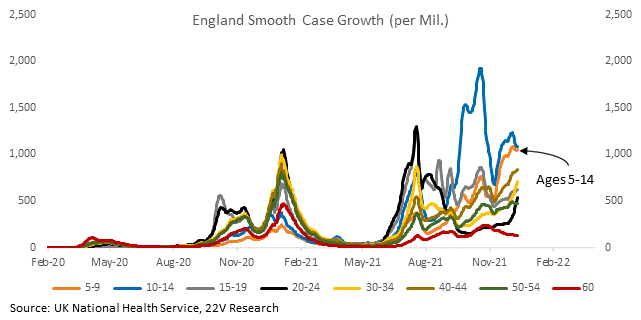
Quick message to start. Investors are keying of what is happening in the UK. Cases have surged and deaths are pinned. Same in NYC right now. That could change, but if UK case growth starts to roll, that will be the first sign to investors that Omicron risk is going to fade quickly. That will be the buy signal for Reopening stocks, Energy and Banks. It would alleviate a major headwinds for 10yr rates. Of course…if deaths in the UK jump quickly, don’t expect relief in Reopening, Energy and Banks. UK data is important. Much more so than the tweets about how severity is tracking or other anecdotes.
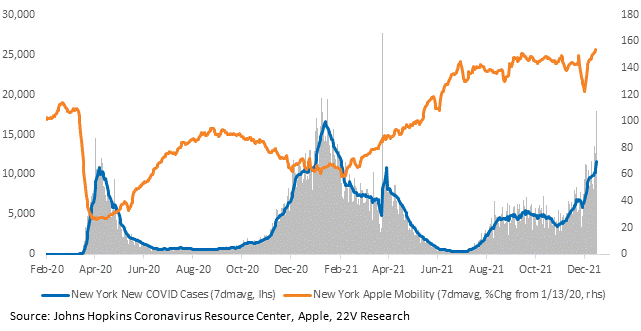
Today we start with a NYC update before quickly recapping what to focus on. NY recorded over 20,000 cases today. NYC health officials have reported Omicron is in NYC and spreading quickly. Case growth is accelerating. Hospitalizations and deaths lag case growth, but it’s worth noting that the Delta wave was much less severe than the winter wave, which was dwarfed by the first wave. Mobility stayed high throughout the Delta wave. Omicron does evade immunity more than Delta, but its severity is unknown and new treatments, like Paxlovid, will still help.

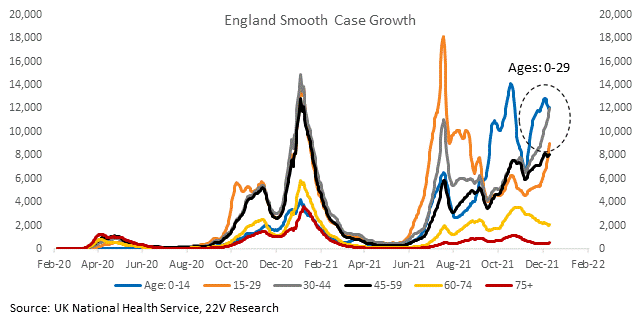
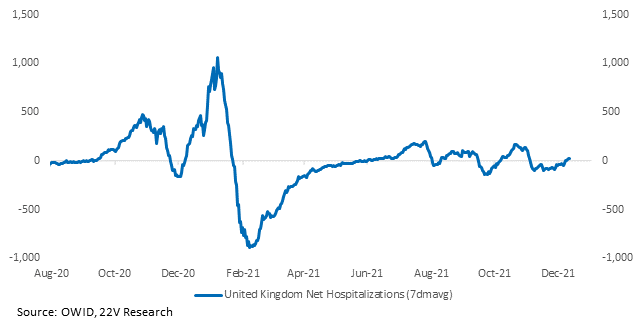
And now a short recap of what to focus on. The UK is a better comp than South Africa. We expect markets to trade off UK data. The ratio of deaths to cases stayed low throughout the delta wave. Treatments like Paxlovid that don’t rely on an immune response to Omicron should help the ratio stay very low, in turn limiting the economic impact. As of right now, case growth is accelerating and moving up age cohorts (0-14 to 15-29). Net hospitalizations have turned positive. Mobility is still high. Everyone is waiting to see if UK case growth will roll over.
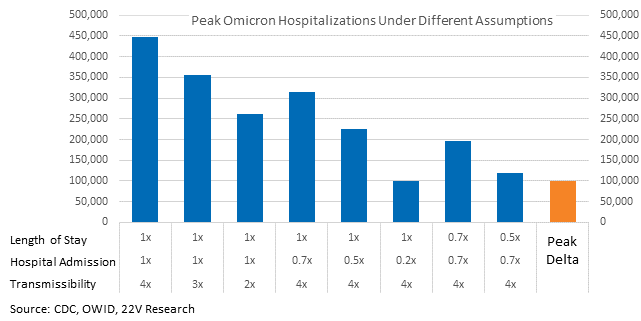
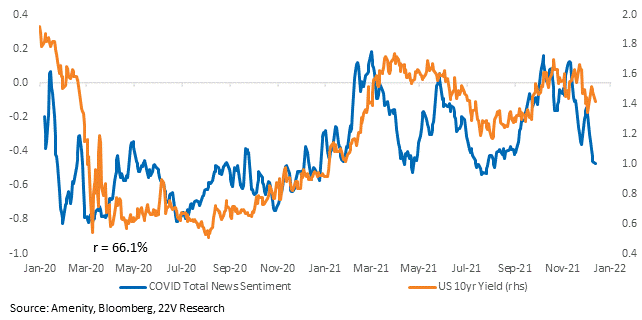
Uncertainty will remain elevated, affecting yields and market internals, until we have cleaner data. There is an incredibly wide range of hospitalizations under different estimates of transmissibility, hospital admission rates, and lengths of stay (check out more HERE), all of which we cannot currently estimate with any reliability. This is why the term premium has dropped, 10yr yields have fallen, and our Recovery Portfolio has underperformed.
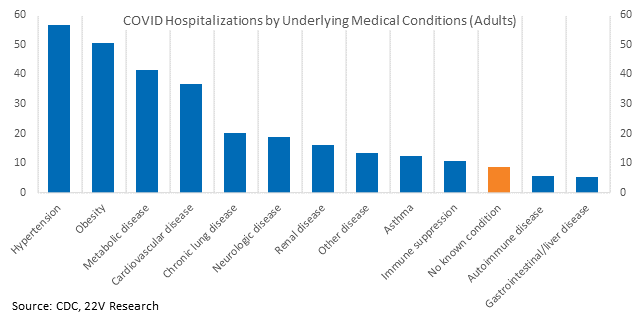
A large study in London found a prior COVID infection offers 19% protection against omicron, roughly as much as two doses of a vaccine (as much as 20% effective). We have been talking a lot about severity and the implications for hospitalizations under different assumptions of severity. News about vaccines and prior infections has been poor, but don’t forget about new therapeutics. Per Eric Topol’s substack, “Until now in the pandemic, our prevention and early treatment of Covid has relied upon our immune system: vaccines and monoclonal antibodies. Our immune response has been substantially evaded by Omicron. Along comes Paxlovid, a pill that could be readily administered which does not rely on our immune response. Omicron doesn’t evade this drug’s effect.” Paxlovid is nearly 90% protective against hospitalization and deaths. The FDA may authorize the drug by year-end. Several health experts think the immediate authorization will only be for people at high risk, but that is still meaningful considering most people who are hospitalized have comorbidities (CDC list here). The only sticking point may be supply; Pfizer can treat 180k people this year, but 21 million or more by the end of June 2022.
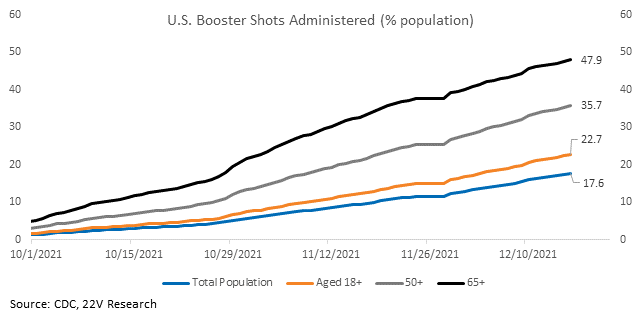
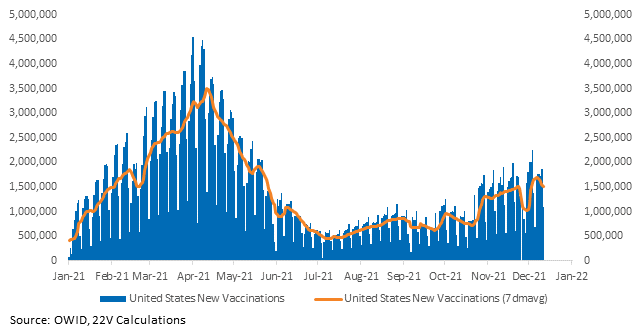
Adding a booster dose helped dramatically, blocking an estimated 55% to 80% of symptomatic cases. The booster campaign in the US is progressing.
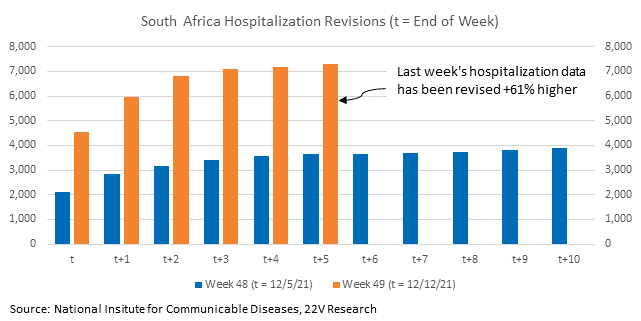
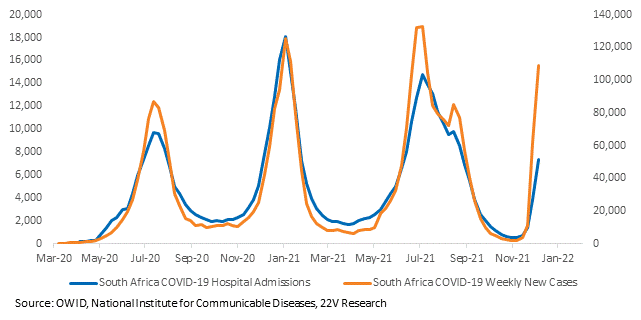
South Africa’s hospitalization data is closely watched. But it’s significantly revised weeks after initial data is released. Hospitalizations for the week ending 12/12 have been revised +61% higher so far this week. Additionally, South Africa’s development and healthcare system are not a great comparison to the developed world. We caution against extrapolating SA’s data. The UK offers a better comparison and publishes better data.
Charts for every state and country we have data for are HERE.

