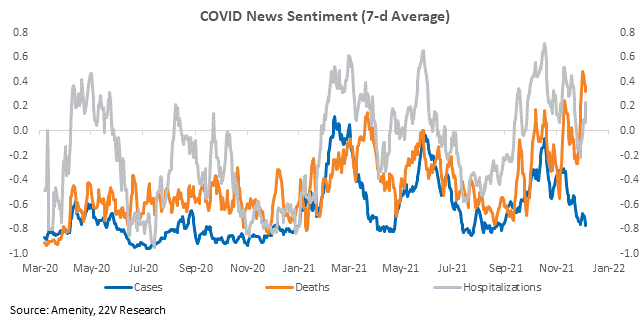
SUMMARY: The combination of relatively strong economic growth expectations (inflation expectations still high) and Omicron/China uncertainty are helping keep inflation expectations at a high level relative to 10yr yields (low real yields). News sentiment toward COVID remains poor, but hospitalization and death sentiment is high. That fits with the general consensus view that Omicron will have much lower severity and a limited impact on economic growth.

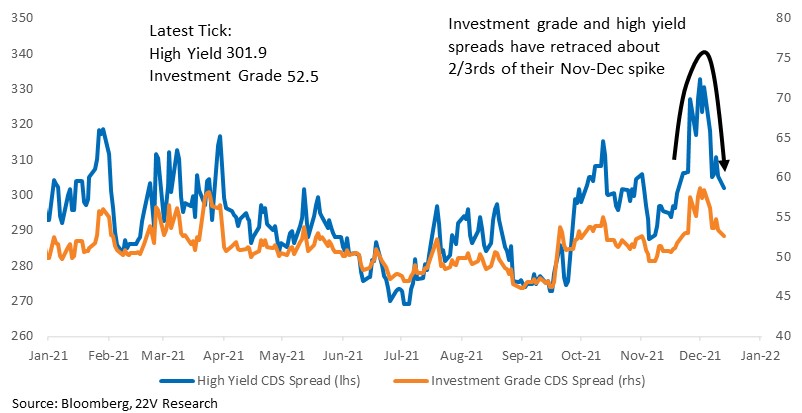
Relatively positive sentiment on COVID deaths and Hospitalizations helps explain the sharp contraction in credit spreads after a move wider since late November. Assuming the Fed doesn’t deliver a shock this week, which we don’t expect, credit spreads should stay relatively tight.
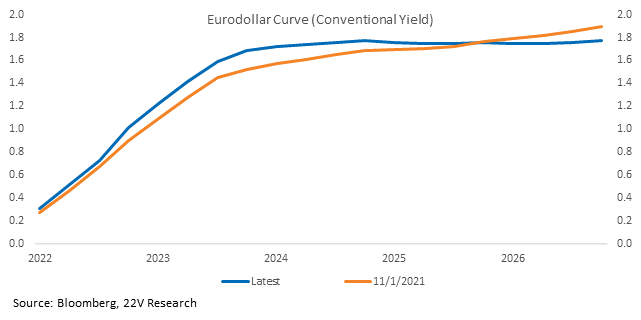
Quickly on the Fed, As Gerard noted, the Fed will tolerate “but does not desire above-2% inflation anymore, and it is willing to sacrifice its employment objectives to limit the inflation overshoot.” Markets have priced in this shift and the question now is how high rates need to go to limit the inflation overshoot. That means the Fed is data dependent and only time will tell. As long as the Fed does not indicate a funds path that is much different than what is current priced, expect less volatility around the Fed this week than feared. The data will drive the Vol.
After a sharp move higher, volatility is lower and unless Omicron news gets much worse, Low Volatility names will continue to decline. Low volatility names tend to be concentrated in Defensive Industries, so a move lower in vol would weigh on Household products, Food, Utilities and Telecom. FYI…Defensives have become very popular recently. Momentum and Earnings Growth names outperform as Vol moves lower and interestingly, Quality does not tend to give up gains when Vol declines. Quality does pretty well in high/low Vol. The net of the current backdrop, High quality non-Value Cyclicals will outperform Defensives unless Omicron news deteriorates.
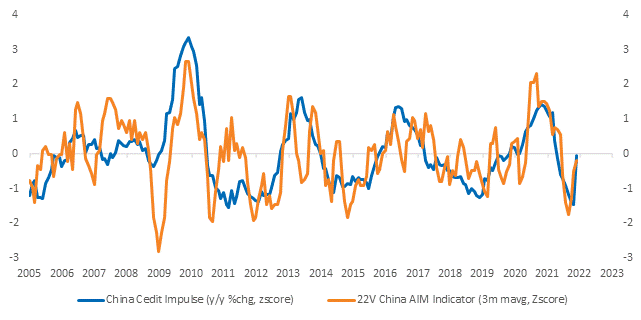
To get Value to work will require a sharp increase in 10yr year yields. Improved China data and moving past the peak Omicron wave would increase 10yr yields. As we noted yesterday, 10yr yields are being anchored by COVID uncertainty. Many sell side firms are calling for a 1Q China stimulus following China’s annual working conference last Friday. That stimulus could happen at the same time we are moving past the peak Omicron wave. 1Q22 is the time to play for the 10yr move to 2%.
Full report below…
MARKET VIEWS: Risk assets are higher again and real rates remain extremely low. The combination of strong economic growth (inflation expectations are still high) and Omicron/China uncertainty are helping keep inflation expectations elevated relative to 10yr yields. News sentiment toward COVID remains poor, but hospitalization and death sentiment is high. That fits with the general consensus view that Omicron will have much lower severity and a limited impact on economic growth.
Relatively positive sentiment on COVID deaths and Hospitalizations helps explain the sharp contraction in credit spreads after a move wider since late November. Assuming the Fed doesn’t shock anyone this week, which we don’t think will happen, we expect credit spreads to stay relatively tight.
As Gerard noted yesterday, the Fed will tolerate “but does not desire above-2% inflation, and it is willing to sacrifice its employment objectives to limit the inflation overshoot.” The markets have priced in this shift and the question now is how high rates need to go to limit the inflation overshoot. That means the Fed is data dependent and only time will tell. As long as the Fed does not indicate a funds path that is much different than what is current priced (a quicker move to 1.8% and then a pause), expect volatility around the Fed this week to be less than feared. The question is how tolerant (or not) they will be of an inflation overshoot and maybe we will get some clues on that this week.
Market internals shifted last week with Momentum and Earnings Growth gaining at the expense of Low Volatility and Value. To the extent that Vol continues to decline, Low Volatility names will continue to move lower. Low volatility names tend to be concentrated in Defensive Industries, so a move lower in vol would weigh on Household products, Food, Utilities and Telecom. FYI…Defensives have become very popular recently.
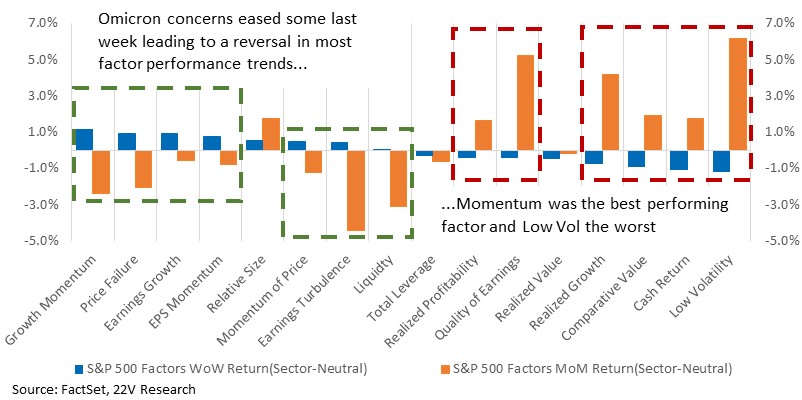
FYI…Quality of Earnings, Realized Growth and Realized Value (to the downside) do not tend to see big reversals as markets recover from big declines/vol spikes. So, Quality and Growth doesn’t have to witness a reversal. Low Vol names tend to reverse. The VIX has retraced most of its late-Nov/early-Dec spike over the past ~week.
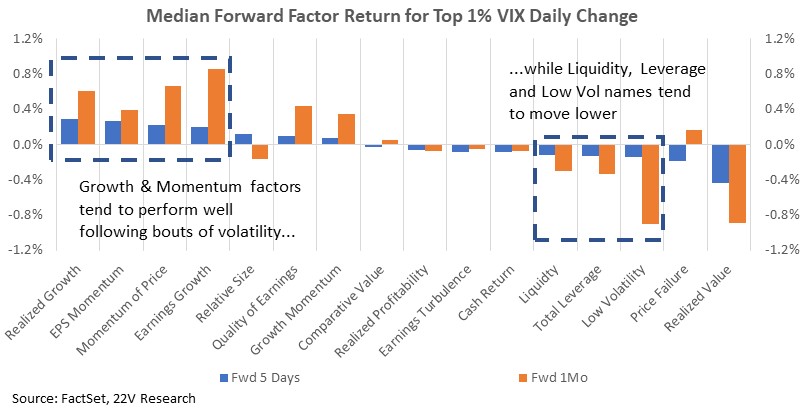
To get an extended rally in Value 10yr yield will need to move higher. Two factors would lead to a significant move higher in 10yr yields. 1) We get through the Omicron wave without a significant spike in hospitalizations (this will take time to figure out). As we noted yesterday, Omicron is the major overhang on 10ry yields currently. And 2) the China outlook improves. The high frequency data in China is becoming less bad and so is the 12-month credit impulse. Indications from the last Friday’s annual Central Economic Work Conference suggest fiscal stimulus is likely in 1Q22. Many sell side firms are calling for a 1Q China stimulus following the conference. If that stimulus happens at the same time we are likely past the peak Omicron wave impact, expect a significant increase in 10yr yields in 1Q. Until then, Quality and Non-Value Cyclicals will work and Defensives will lag.