SUMMARY: Based on the Amenity natural language processing tool (NLP), company commentary this earnings season was particularly poor (AAPL/AMZN the latest). Negative supply chain commentary is likely impacting investors sentiment on the outlook for inflation and margins. It also suggests higher volatility or sensitivity to moves in short rates, inflation data points or anything that suggests 1) supply chains are not improving or 2) the growth outlook will slow (slowing growth with persistent supply chain issues is a bad combo).
Likely related to supply issues, companies that miss earnings estimates have been more harshly punished this reporting season, while beats have generated smaller than normal gains. Relatively few companies have missed estimates, but avoiding those names has been more accretive to portfolio performance than normal.

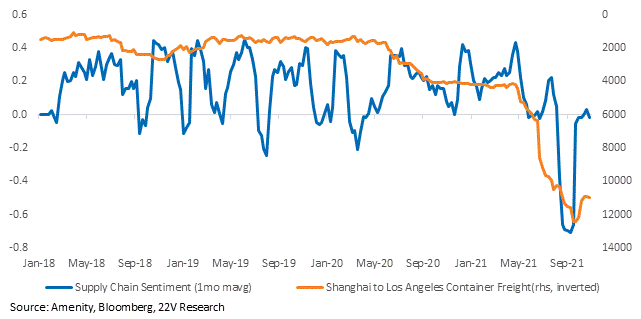
Inflation or supply chain issues appear to be getting better at the margin. Overnight it was reported that Putin ordered Gazprom to begin filling storage facilities in Europe and thermal coal prices in China are down -47% in just 10 days. Running Amenity’s NLP tool on news items related to companies and supply chains, finds supply chain sentiment has become much less negative. To the extent that continues, freight rates are biased lower over time.
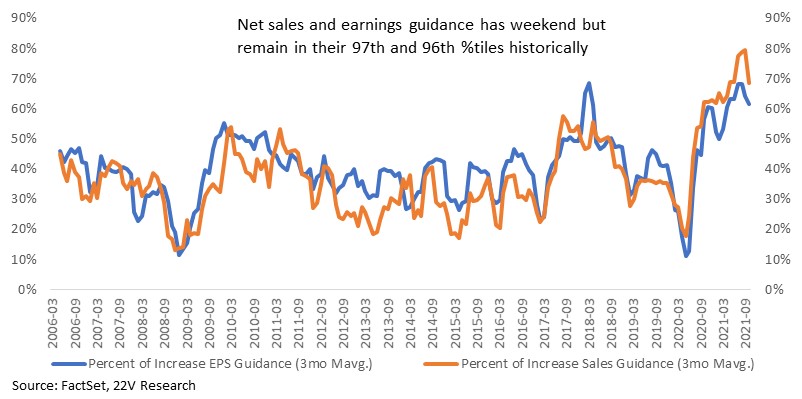
Assuming some stabilization in commodity prices, CPI pressures should ease amid a still strong demand backdrop. AAPL CFO, Luca Maestri said that demand was “very, very strong”. That helps explain the strong business commentary sentiment from earnings calls. Also, on a net basis forward revenue guidance is +68.5% versus a typical level of 37%. Net EPS guidance is 62% versus a longer-term median of 40%. We do not want to dismiss concerns about the incremental deterioration in guidance, but in any pre-pandemic period the level of guidance would be record setting.
The bottom line: the demand outlook is firm and if commodity prices settle down (supply responds) and supply chains free up (our base case), expect yield curves to steepen, volatility to be pinned and Cyclicals to outperform. We also like taking advantage of the sharp flattening of the yield curve and underperformance of small caps to be long IWM again. We expect some steepening in curves from here. We also review the unique backdrop of some deeper Cyclicals outperforming while Value is getting killed. That suggest investors are playing for strong economic growth but choosing to avoid Value when picking stocks within sectors. Stock picking is more important now.
Full report below…
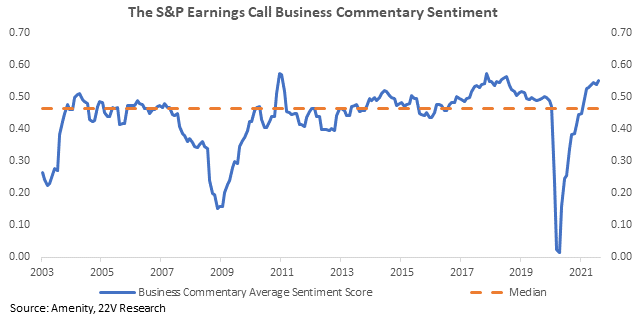
MARKET VIEWS: Tech is under pressure as both AAPL/AMZN earnings were held back by supply chain issues and in AMZN’s case specifically, labor costs. The AAPL/AMZN news fits with the broad earnings season trend of consistently negative supply chain sentiment. Based on the Amenity natural language processing tool (NLP), company commentary this earnings season was particularly poor. The negative supply chain commentary is likely impacting investors sentiment on the outlook for inflation and margins. It also suggests higher volatility or sensitivity to moves in short rates, inflation data points or anything that suggests 1) supply chains might not be improving or 2) the growth outlook will slow (slowing growth with persistent supply chain issues is a bad combo).
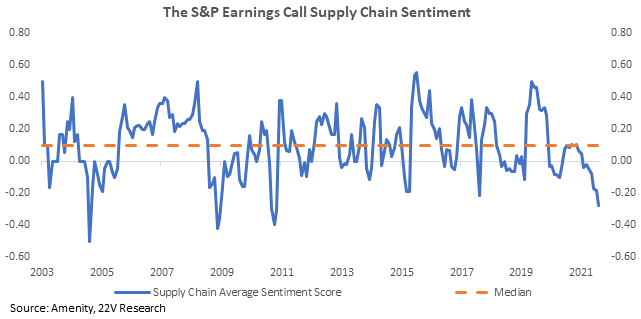
Consistent with supply chain concerns, companies that miss earnings estimates have been more harshly punished this reporting season, while beats have generated smaller than normal gains. That is consistent with the wide breadth of beats and is another indication that stock picking is coming back to the forefront of alpha generation. Relatively few companies have missed estimates, but avoiding those names has been more accretive to portfolio performance than normal.
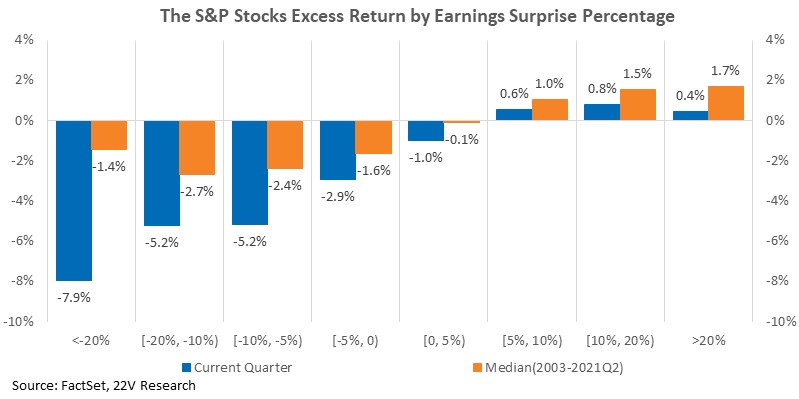
Some of the sticky inflation or supply chain issues appear to be getting better at the margin. Overnight it was reported that Putin ordered Gazprom to begin filling storage facilities in Europe (UK nat gas prices are moving sharply lower the last few days) and thermal coal prices are -47% in just 10 days. Also, when Amenity runs the same NLP tool for news items related to companies and supply chains, we find that supply chain sentiment has become much less negative. To the extent that continues, freight rates are biased lower over time.
LOOKING FORWARD: CPI data in Europe was higher than expected, but assuming some stabilization in commodity prices (seems likely from an impact on inflation point of view), CPI should ease over time. The demand backdrop is still firm though. European GDP came in better than expected and consumer spending drove the output numbers higher. The US GDP report suggested strong consumer demand going forward and the AAPL CFO, Luca Maestri said the that demand was “very, very strong”. That helps explain the strong business commentary sentiment from earnings calls.
Forward guidance, both sales and earnings, have rolled over some as the breadth of top and bottom line upgrades slows. Keep in mind that both readings are still exceptionally high. On a net basis (increases in guidance – decreases), forward revenue guidance is +68.5% versus a typical level of 37%. Net EPS guidance is 62% versus a longer-term median of 40%. We do not want to dismiss concerns about incremental deterioration, but in any pre-pandemic period the level of guidance would be record setting. The net net of the above sections, the demand outlook is firm and if commodity prices settle down (supply responds) and supply chains start to free up, expect yield curves to steepen, volatility to be pinned and Cyclicals to outperform. We also like taking advantage of the sharp flattening of the yield curve and underperformance of small caps to be long IWM again.
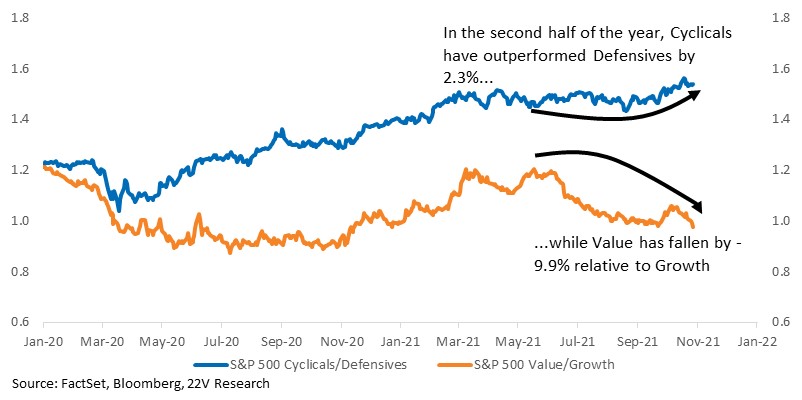
DEEPER CYCLICALS & CYCLICALS OUTPERFORM, BUT VALUE HASN’T. WHAT GIVES? First and foremost, it is important to understand the performance spread between Cyclicals vs Defensives and Value vs Growth. Cyclicals have outperformed Defensives all year and are +2% over the last second half of 2021. Since the end of 2Q, Value has underperformed Growth by -10%. That is a significant spread.
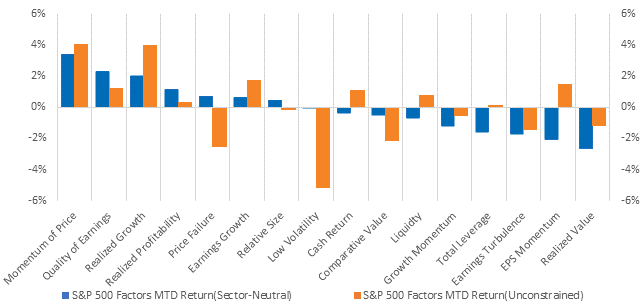
Two things to keep in mind on this front, which we cover in more detail in a Quant report released earlier today. There has been divergences between factors on a sector neutral vs unconstrained (unconstrained means factors can have heavy sector skews). Unconstrained performance was poor in October, but much better than sector neutral performance. One could argue that investors are buying Cyclicals but tilting toward the growth names within those sectors. Maybe strong economic growth, but consistent supply chain concerns or macro uncertainty in general is leading to that type of positioning.
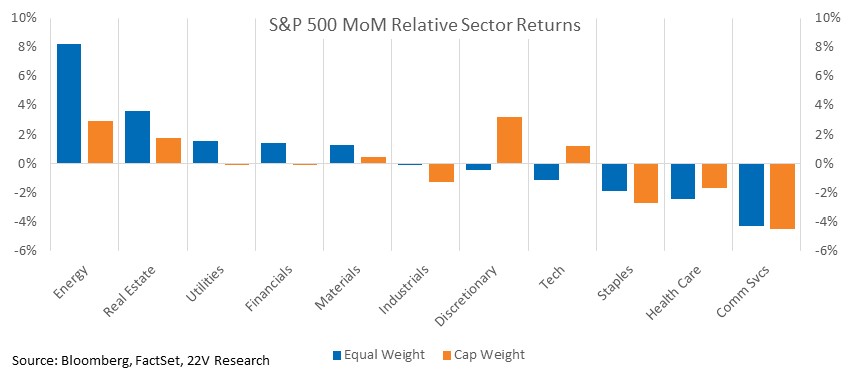
Also, it is important to keep in mind that factor exposure of a sector does not necessarily mean the performance of that sector will be correlated with the performance of the factor. Most ETFs and major index sector baskets are cap weighted while sector exposure is typically measured on a breadth (count rather than cap) basis. Energy has been the best performing sector over the past month on an equally weighted basis and second-best cap weighted. That is despite having a high breadth of Value exposure. Value has underperformed Growth by -4.1% MoM. The bottom line, people bought Energy but made sure to avoid the Value names. The other explanation is stock picking is becoming much more important in driving returns.