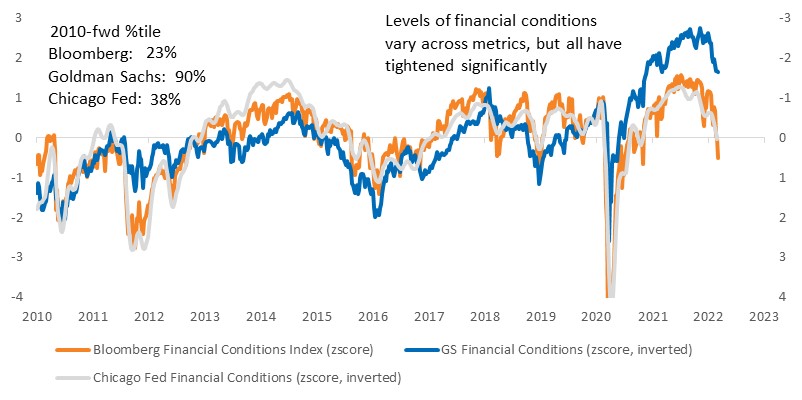
Since late-21, as it became increasingly clear that 1) inflation was proving more persistent than hoped, and 2) that Fed/global central banks would need to shift from accommodation to slowing growth, financial conditions have been tightening. Since the start of the war, defined using Russian CDS movements, financial condition tightening has accelerated sharply. Strong economic data, rising inflation expectations and consistent messaging from the Fed indicate investors need to position for further tightening of conditions.
Factors and industries best aligned to tightening have surged, on a relative basis. At the factor level, Earnings Turbulence, Liquidity, and Realized Value have struggled while Low Volatility and higher Quality of Earnings names have been the best performing style factors. Within Industries, Staples and Defensives have performed well while Financials and Autos have struggled.
When using factor screens, we recommend focusing on factors best aligned to what is likely to be a long-term and significant tightening on financial conditions. Let us know if you would like a list of names that fall into each grouping. We can also run style factor rankings on a specific universe of basket of names.

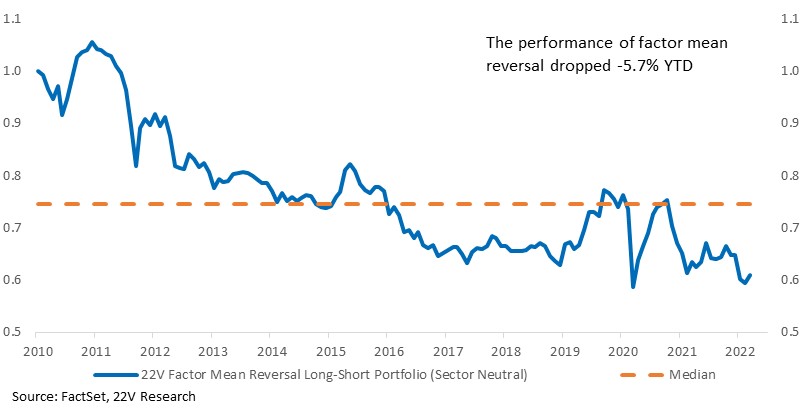
If peace breaks out, there is likely to be some rebound in industries that have suffered the most during the recent period of market declines. Importantly, factor mean reversal has been a poor strategy over most of the past several years. We would expect to see some rebound in risk-on factors short-term, but the lack of mean reverting tendencies at the factor level, along with the persistence of the tightening financial conditions trend suggests any factor rebound should be seen as an opportunity to add to Quality/Low Vol positions.
Positioning for Financial Condition Tightening: Since late-21, as it became increasingly clear that 1) inflation was proving more persistent than hoped, and 2) that Fed/global central banks would need to shift from accommodation to slowing growth, financial conditions have been tightening. That process accelerated over the past few weeks as fears of a war in Eastern Europe were realized. Strong economic data, rising inflation expectations and consistent messaging from the Fed indicate investors need to position for further tightening of conditions.
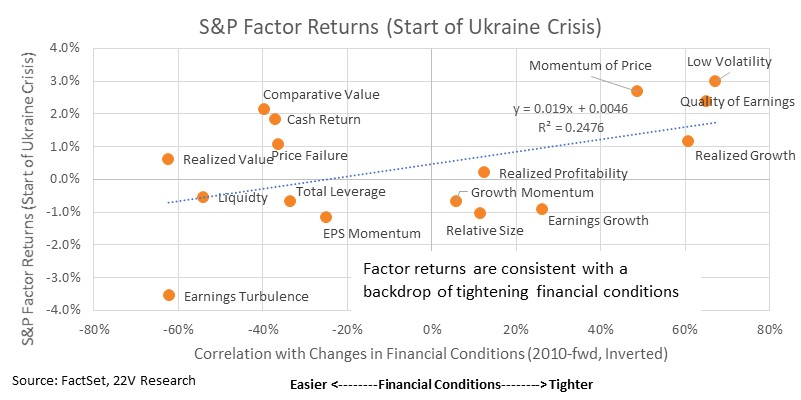
Since the start of the war, defined using Russian CDS movements, market internals have been well aligned with the tightening of financial conditions. Earnings Turbulence, Liquidity, and Realized Value have struggled while Low Volatility and higher Quality of Earnings names have been the best performing style factors.
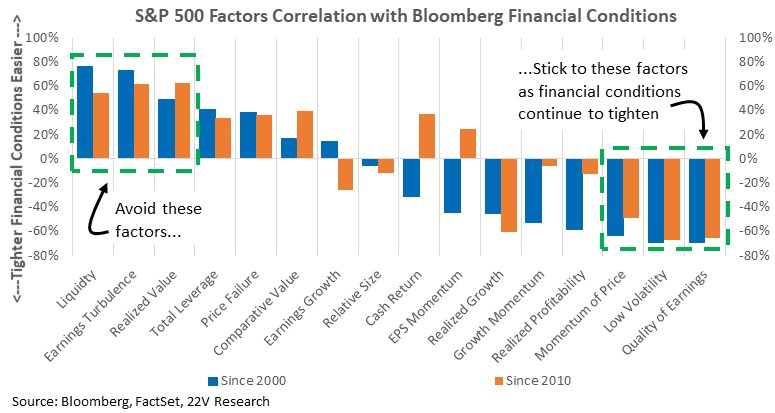
When using factor screens, we recommend focusing on factors best aligned to what is likely to be a long-term and significant tightening on financial conditions. Some factors have inconsistent returns over pre/post-GFC periods of tightening conditions, but high Earnings Turbulence, Low Liquidity, and high Realized Value have consistently struggled while names with higher quality earnings and lower vol and higher price momentum have consistently gained.
Industry group relationships are less consistent than factor returns but aligning to groups that have historically outperformed as financial conditions tighten has been a successful strategy over the past few weeks. Staples and Defensives in general tend to perform well while Financials and Autos tend to struggle.
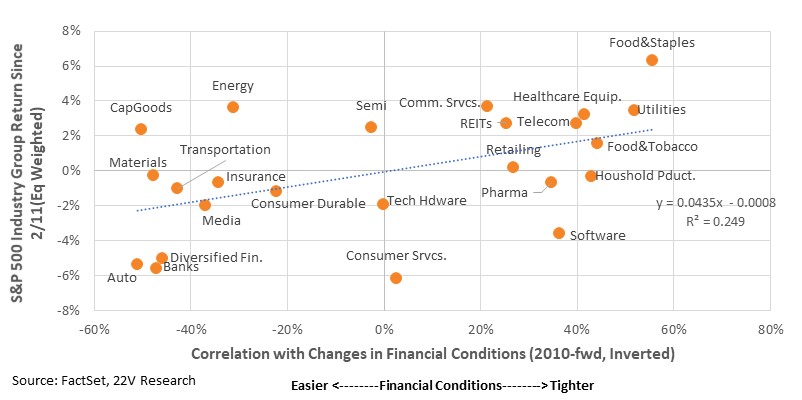
If peace breaks out, there is likely to be some rebound in industries that have suffered the most during the recent period of market declines. Importantly, factor mean reversal has been a poor strategy over most of the past several years. We would expect to see some rebound in risk-on factors short-term, but the lack of mean reverting tendencies at the factor level, along with the persistence of the tightening financial conditions trend suggests any factor rebound should be seen as an opportunity to add to Quality/Low Vol positions.