
Our entire repository of COVID charts is HERE.
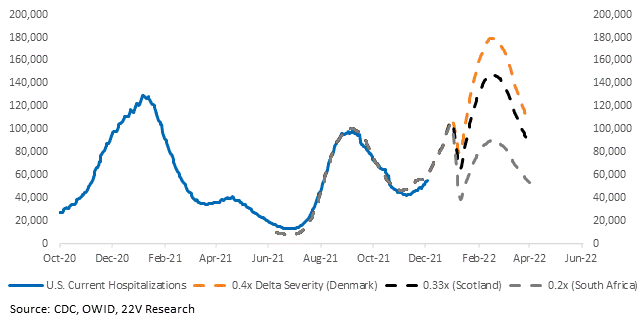
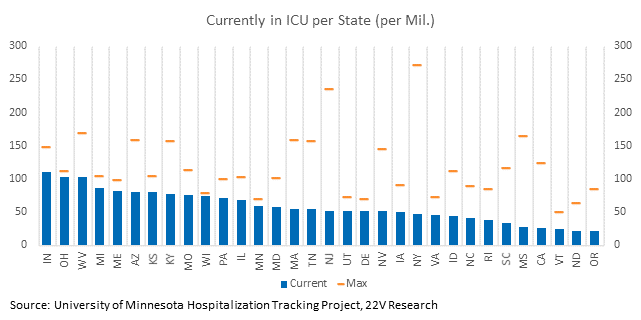
We’re going to keep things short today, recapping the most important recent developments. First, Omicron severity data, new therapeutics, and new booster data all indicate the worst-case scenarios are off the table, despite rapid case growth. It’s unlikely Omicron will be a significant demand shock.
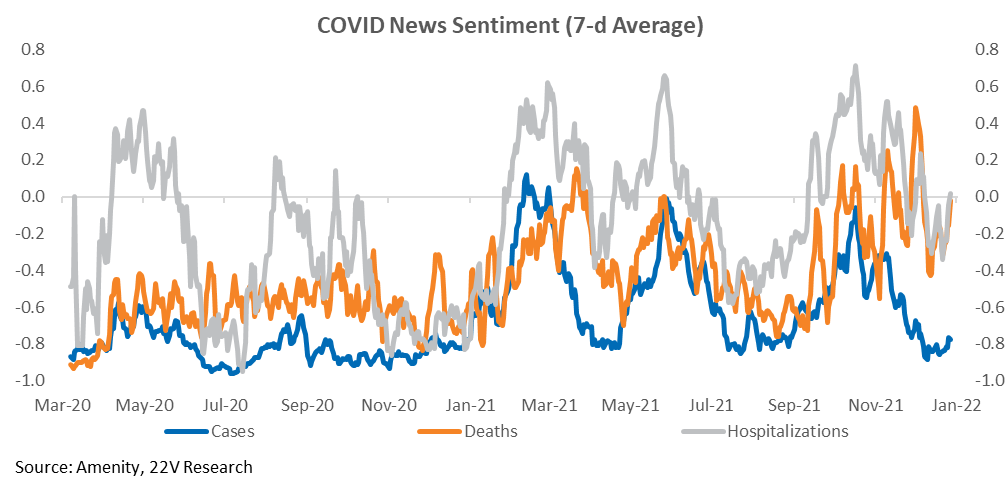
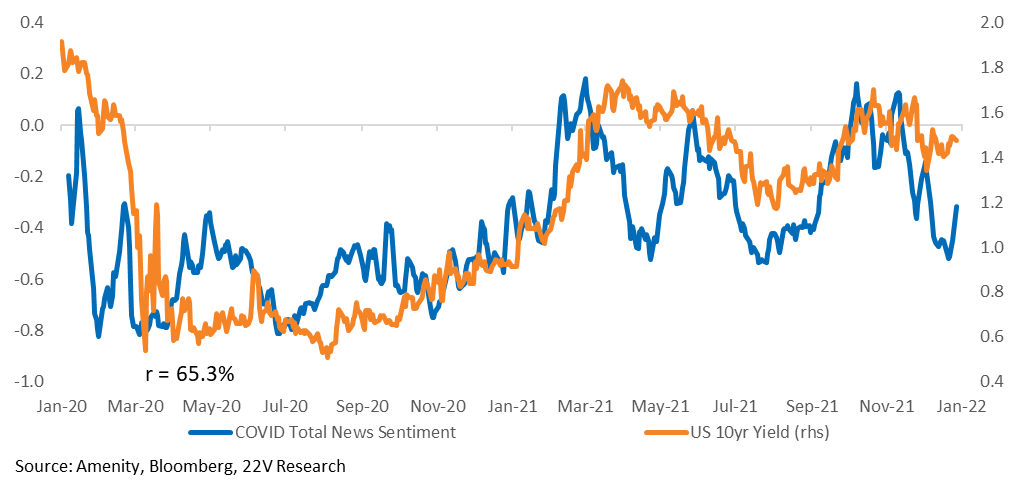
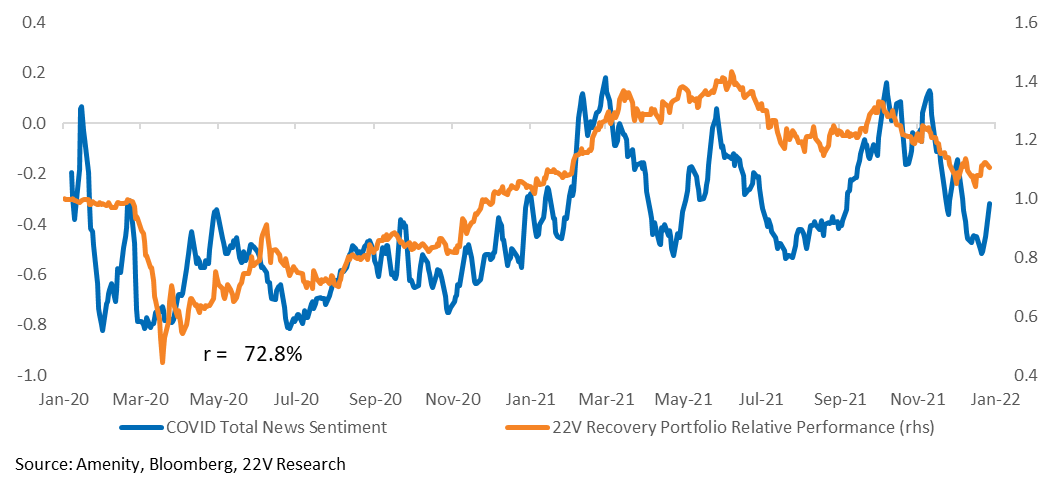
Second, COVID news sentiment, particularly concerning severe disease, is improving. Better sentiment alleviates a significant headwind to 10yr yields and to our Recovery Portfolio.
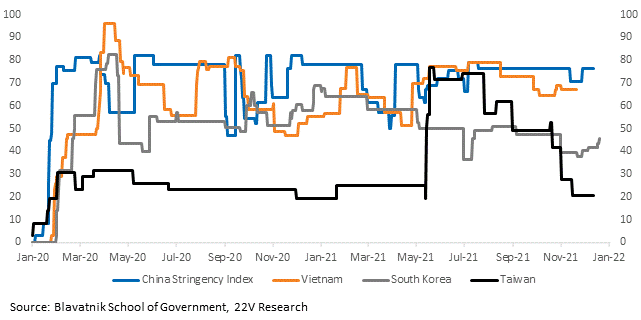
And third, the primary risk, as long as estimates of severity are roughly accurate, is now whether an Omicron outbreak in Asia disrupts supply chains. How countries respond to Omicron will have an important impact on supply chain issues near term, but there is not yet enough data to determine which way that will break. China’s zero-COVID policy appears to be in full effect. Supply chain sentiment is deteriorating while the intensity of supply chain news is increasing. Case growth in Asia ex-China is, for now, tame. We are monitoring Oxford’s stringency indices to track the level of restrictions. China and Vietnam are both have elevated COVID restrictions while South Korean and Taiwan do not.

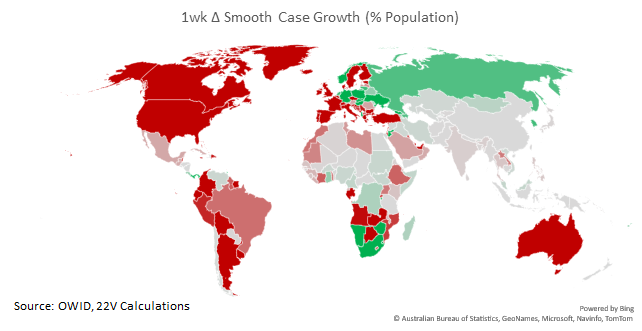
Charts for every state and country we have data for are HERE. Have a happy New Year.

