SUMMARY: The S&P has had a string of unusually large drawdowns. Small caps have been unusually weak with 62% of Russell 2K names -20% from their highs. 60% of Nasdaq names are down at least -10% and 52% of S&P names have corrected. Near term forward returns tend to be stronger than normal following large drawdowns, but that has clearly not been working over the past month. The hawkish Fed pivot and Omicron risk have overwhelmed the usual market reversal typical from oversold conditions and depressed sentiment readings.
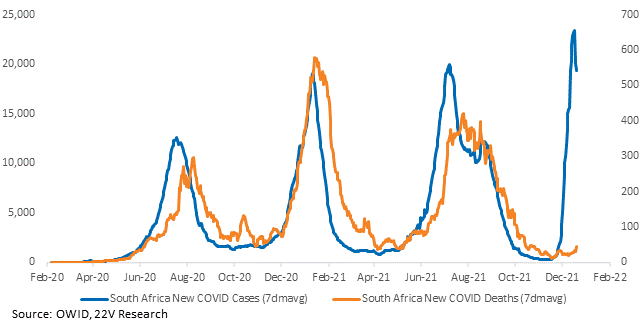
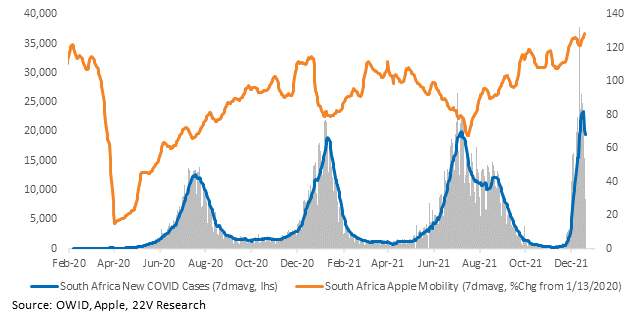
The CDC estimates 73% of US COVID cases are Omicron now, which means peak case estimates should be reached faster in the US give Omicron’s high R0. Cases appear to be peaking in SA and the UK should follow soon. Mobility in SA increased during the Omicron wave, indicating a natural rather than lockdown induced burnout of Omicron (assuming numbers hold). More importantly, deaths remain at extremely low levels. That pattern suggests a bullish outlook for the post-Omicron world. Especially as prophylactics become widely available (don’t forget about Paxlovid).
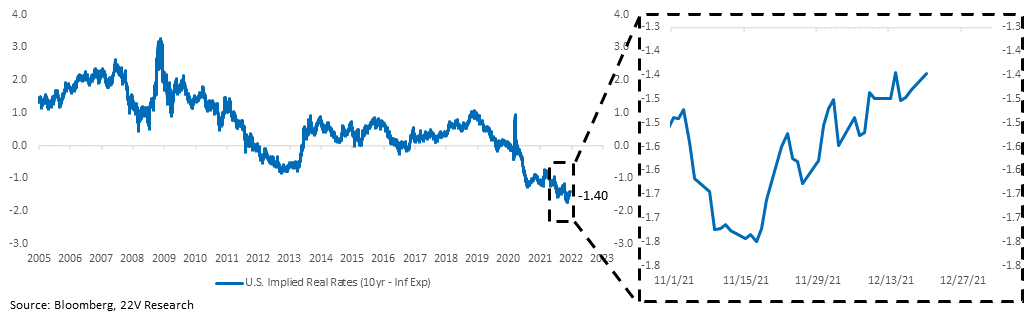
The Fed is focused on increasing real yields and to the extent that Omicron news improves, 10yr UST yields are headed higher. As we have noted, large declines in 10yr UST yields in 2021 have been associated with new variants. As those threats have passed, 10yr yields moved higher (10yr yields rose significantly following the peak Delta fear in mid-August).
Just like this in August and September (remember stagflation?), don’t extrapolate market internals when COVID fears accelerate. Doing so in Aug/Sept led some to call for a sharp slowdown in consumption, which proved wrong. The same arguments are being made today about the growth outlook. Growth will slow some but is still likely to remain above trend given the structural consumer, capex and inventory supports for the US economy. Set up portfolios to benefit from higher real rates (portfolio HERE).
Full report below…
MARKET VIEWS: Real implied yields, although still extremely low, increased yesterday and are slightly higher again this morning. So far, the increase in implied real rates has been a function of inflation expectations falling at a faster pace than UST yields. The Fed is focused on increasing real yields and to the extent that Omicron news improves, 10yr UST yields are likely headed higher. As we have detailed in several notes, the large declines in 10yr UST yields in 2021 have been associated with new variants. As those threats pass, 10yr yields tend to rerate higher (10yr yields moved significantly higher in the months following the peak Delta fear in mid-August).
CDC estimates that 73% of US cases are Omicron now, which means we should move forward peak case estimates for the US give Omicron’s high R0. It has already happened in SA and UK should follow soon. Mobility in SA increased during the Omicron wave, which would point more to natural burnout, not lockdowns, driving the decline (assuming the numbers hold).
Most importantly, cases have started to hook over and deaths remain at extremely low levels. If this pattern holds, a bullish outlook for a post-Omicron world develop. Especially as prophylactics become widely available (don’t forget about Paxlovid).

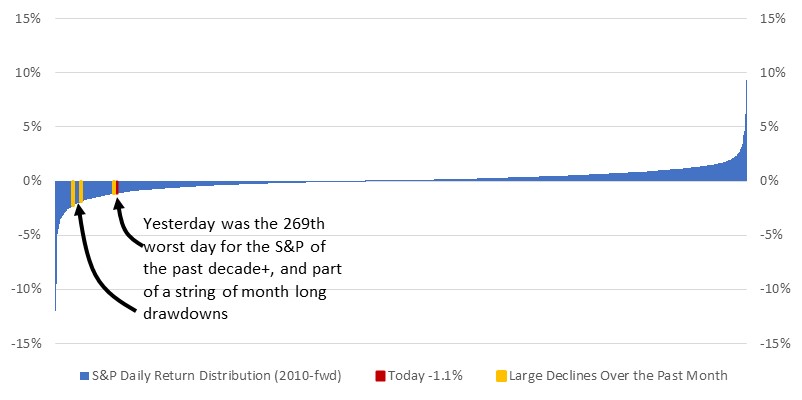
As far as drawdowns are concerned, yesterday was the latest in a string of large down days. Over the past month the S&P is down a little over -2.5%.
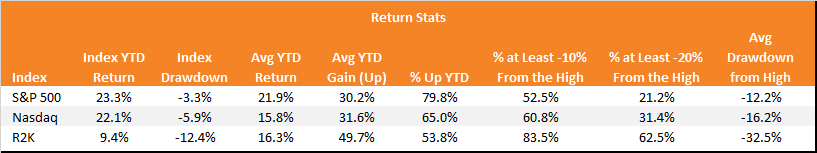
The drawdown has been most intense in small caps. 62% of small cap names are -20% from their highs. 60% of Nasdaq names are -10% and 52% of S&P names are -10%.
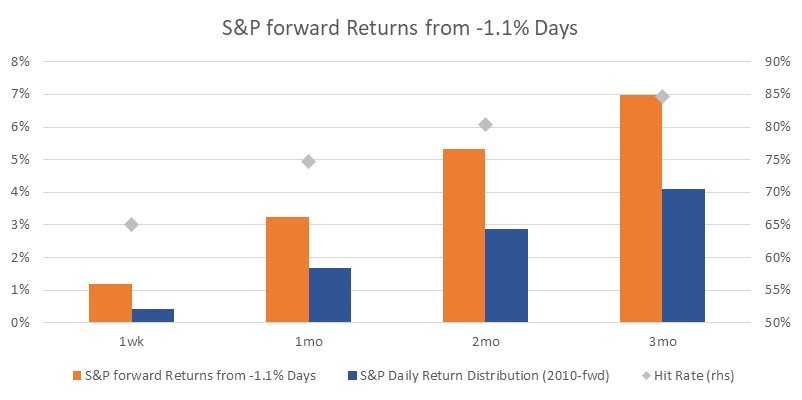
Near term forward returns tend to be stronger than normal following large drawdowns, but that has clearly not been working over the past month. Negative sentiment readings, clear oversold conditions for the average stocks, sentiment being unusually negative relative to hard economic data (all things associated with stronger than normal forward returns), have been overwhelmed by the combination of the hawkish Fed pivot and Omicron risk.
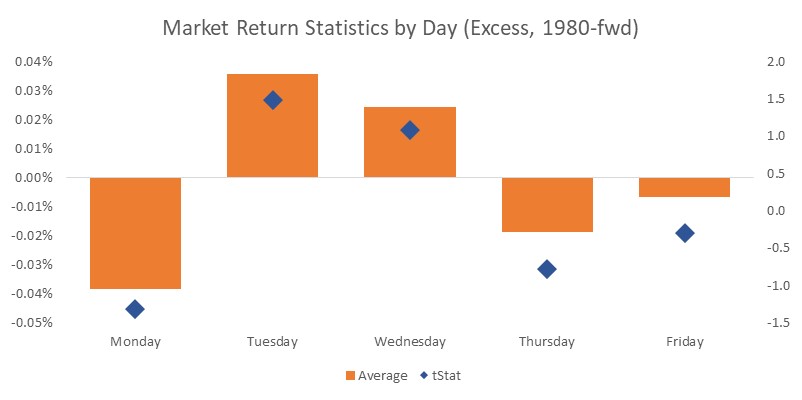
Tuesday’s do tend to be the best days for equities, so a bounce would be normal today. Many clients we talked to yesterday thought a “turn around Tuesday” bounce was likely. Given the market volatility of late, playing for one day reversals or extremely short term ideas seems like a fast way to lose money. Volatility is too high and news flow on Omicron too volatile.