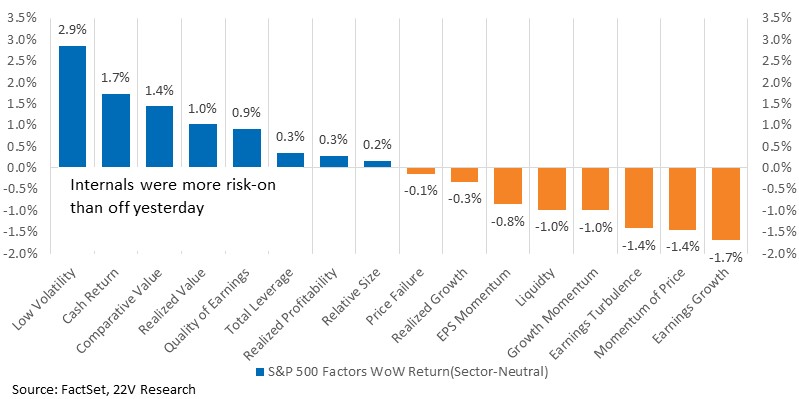
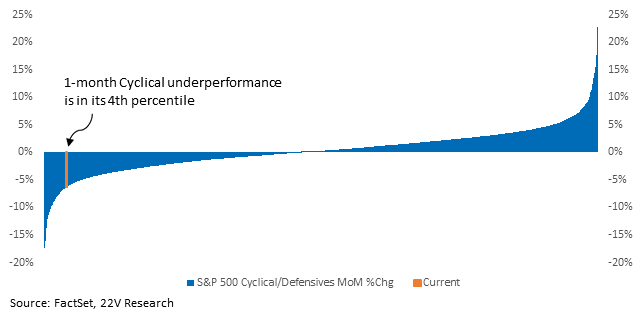
SUMMARY: BBB failing, the Fed pivot and increasing Omicron related shutdowns continue to support defensive and low vol assets as GDP estimates move quickly lower. Equities fell at the index level last week while Low volatility stocks and Defensives led factor internals. Defensive’s have had a 96th %tile move relative to Cyclicals over the past month and Low Vol names have gained 8% (l-s, sector neutral) a 95th %tile move and an exceptionally strong return for the factor.
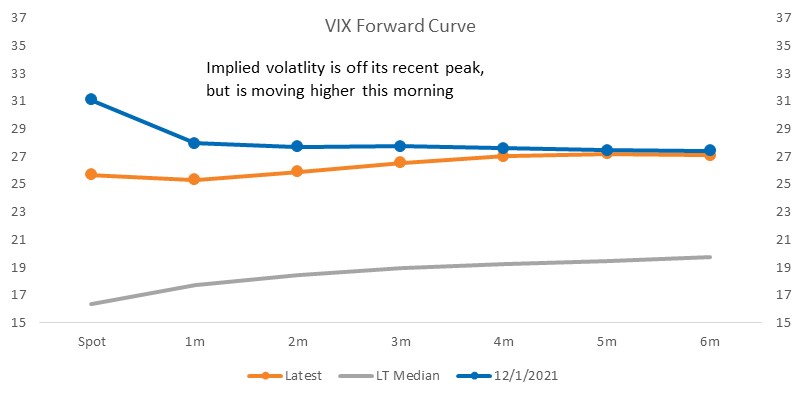
Implied vol is still lower than its early December high but is up significantly today. The rest of macro is RELATIVELY subdued compared to equities overnight. 10yr yields are down, but not meaningfully so and inflation expectations and credit are relatively stable. That could change in the next few hours, but for now, the volatility appears to be concentrated in equities. The VIX curve has shifted meaningfully higher and is well above its long-term median. Until Omicron risk fades, we would expect persistently higher implied volatility across the curve.
The fundamental backdrop for the US economy is still strong and Manchin essentially killing BBB is not going to change that. The Fed also is data dependent and is not interested in significantly slowing economic growth (they want real yields higher. Remember that).
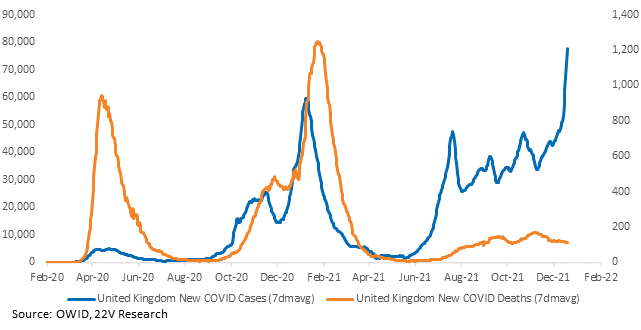
The bottom line: We continue to maintain that 1) a dominate but less severe strain is ultimately a positive but 2) the path to figuring that out is very difficult. We need to get through the pig in the python on case growth near term with obvious low severity. The news and political headlines will be hysterical as we move through this process. That is why the UK is so important. If UK case growth starts to taper off and deaths stay at low levels, it will signal that worst case scenarios are off the table. Low volatility and Defensive, which have had outlier relative performance over the past month, will come under relative pressure as that happens. Unfortunately, we likely need to wait until January to figure that out.

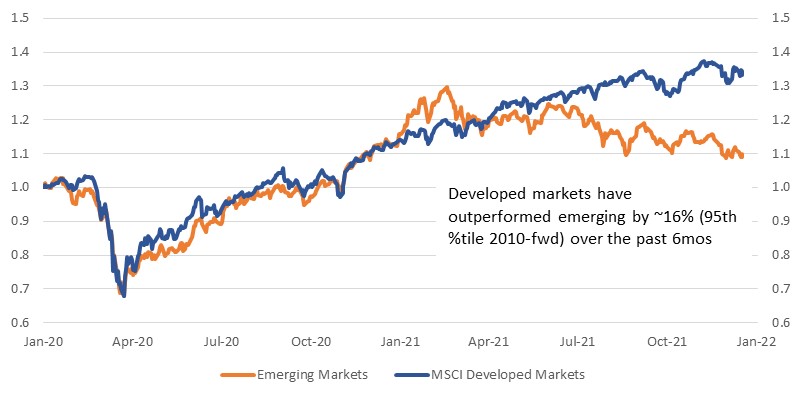
We also highlight a longer term reason why Emerging equities could outperform Developed next year. Developed markets have outperformed emerging by 16% over the past six months. Over the past 30 years (pre-GFC) and over the past decade (post-GFC), that has almost never happened. Over the next few quarters, as real rates rise in the U.S. and Europe, the gap between EM and DM performance should close in favor of EM.
Full report below…
MARKET VIEWS: Investors are internalizing Manchin giving up on BBB and increasing Omicron related shutdowns (the vast majority of which are coming from Europe) this morning. The failing of BBB, the Fed policy pivot and Omicron risk continue to support defensive assets as GDP estimates move quickly lower. Equities fell at the index level last week while Low volatility stocks led factor internals…
…And Defensives continue to outpace Cyclicals. Defensive’s have had a 4th %tile move relative to Cyclicals over the past few weeks.
Implied vol is still lower than the early December highs but is increasing significantly today. The rest of macro is RELATIVELY subdued compared to equities overnight. 10yr yields are down, but not meaningfully so and inflation expectations and credit are relatively stable. That could change in the next few hours, but for now, the volatility appears to be concentrated in equities. The VIX curve has shifted meaningfully higher and is well above the long term median. Until Omicron risk fades, we would expect high level of implied volatility across the curve.
Over the past month Low Vol names have gained 8% (l-s, sector neutral), which is an exceptionally strong return for the factor.
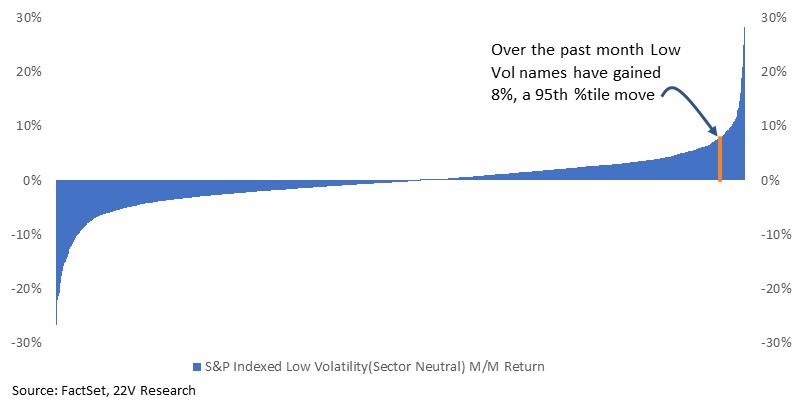
The fundamental backdrop for the US economy is strong and Manchin essentially killing BBB is not going to change that. The Fed is data dependent and not interested in crushing US economic growth. The significant portion of low volatility and Defensive stock outperformance is related to Omicron uncertainty. We continue to maintain that 1) a dominate but less severe strain is ultimately a positive but 2) the path to figuring that out is very difficult. We need to get through the case growth surge with extremely low severity. That is why the UK is so important. If UK case growth starts to taper off and deaths stay at unusually low levels, that will send a signal that worst case scenarios are off the table. Low volatility and Defensive will come under significant relative pressure when that happen. Unfortunately we likely have to wait until January to figure that out.
DEVELOPED VS DEVELOPING: Developed markets have outperformed emerging by 16% over the past six months. Over the past 30 years (pre-GFC) and over the past decade (post-GFC), that has almost never happened. In 2021, China decided to crackdown on speculative lending, big tech and property price gains, weighing on emerging market assets. Heading into 2022, the developed world is tightening policy at the same time authorities in China are signaling another round of stimulus/economic support. Over the next few quarters, as real rates rise in the U.S. and Europe, the gap between EM and DM performance should close in favor of EM.