Back China Strategy

China: Stimulus Moves Fail to Revive Macro Sentiment (CHESS update)

Published on October 7, 2026

∙ Download the PDF Report

By

Michael Hirson

Houze Song

This report updates the signals on China’s outlook from our proprietary China Economic Sentiment Series (CHESS) tool. CHESS uses LLMs to assess the sentiment of Chinese economists writing in the domestic financial media and in analyst reports. The result is a quantitative and visual expression of how views toward the economic and financial outlook are evolving.

China’s macroeconomic environment this year has been very subdued, with strong exports only partially offsetting the impact of weak domestic demand. Our annual China investor trip last month found few expectations of major stimulus coming along anytime soon (link HERE).

In recent weeks, however, Beijing has stepped up the pace of incremental policy support:

  • Financing for the “six networks,” an AI-focused infrastructure program announced last year, finally started to translate into activity on the ground in September. This was likely one factor behind a decent PMI reading for China last month.
  • On September 29, PBOC announced a mortgage interest subsidy to help revive property demand, and a series of actions to further boost financing for the “six networks.” (see our write-up HERE).

While some analysts refer to these moves as a “mini-pivot,” our own take has been skeptical. We see the actions as too small and too narrow to revive property or provide a meaningful boost to growth. The latest signals from our CHESS tool, which compiles the views on economic commentary within China, echo that cautious view.

  1. Stimulus Expectations Have Barely Budged

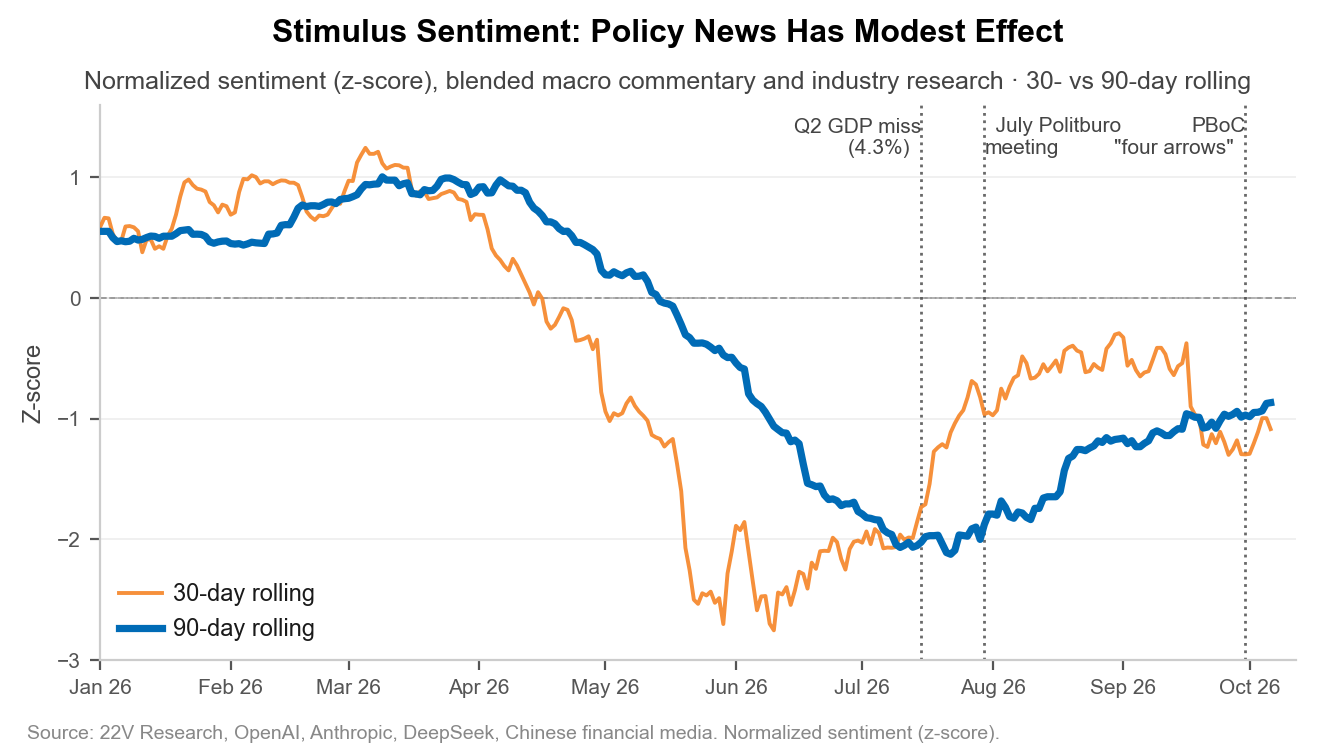
In the chart below, we show analyst sentiment towards the stimulus outlook: our usual 90-day rolling average (blue line), along with a shorter 30-day rolling average (orange line) to better capture reactions to specific announcements.

Stimulus expectations increased in mid-July after a very disappointing Q2 GDP release, which fed hopes that the end-July Politburo meeting on the economy would bring more pledges of support. The very incremental signals from that meeting failed to provide a lift, and stimulus hopes have since drifted lower again. Thus far, the reaction to the PBOC’s September 29 announcement has been quite muted.
  1. Household Demand is Depressed

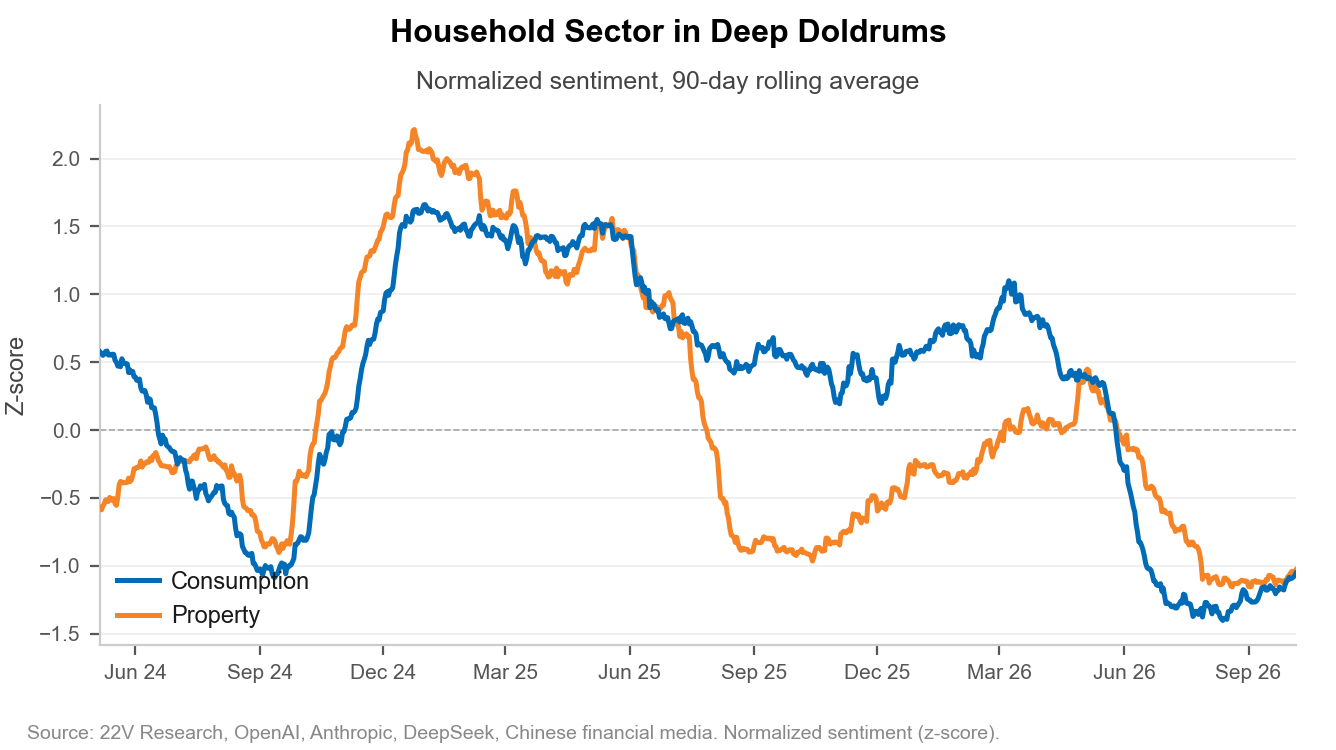
The weak state of private sector demand underscores why more policy support is critical. Demand from the household sector, in particular, is in rough shape. In the chart below, we show analyst sentiment towards consumption (blue line) and property (orange line). Both remain stuck at their lowest levels since before China’s September 2024 policy pivot.

Our analysis has centered on the weak labor market as the key reason why household activity is depressed. That calls for stronger fiscal policy to boost job and wage growth.
  1. Exports Are the Bright Spot

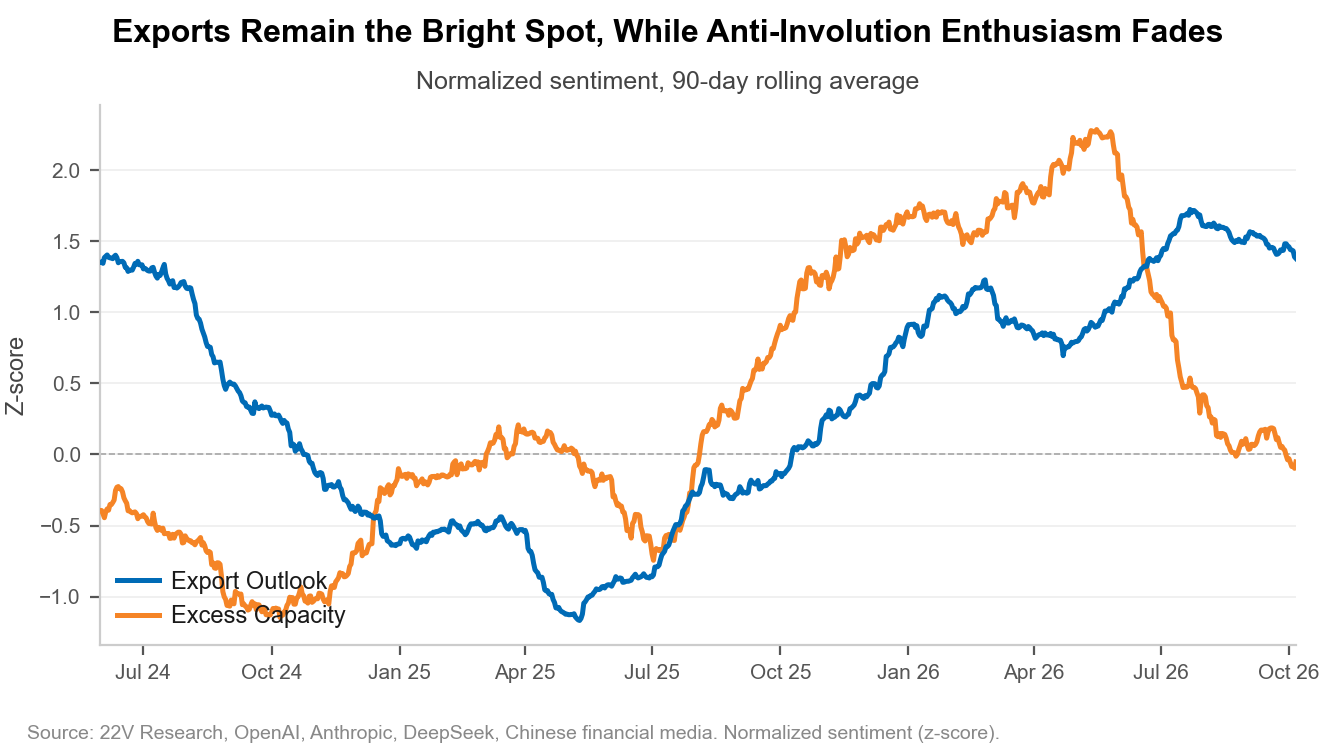
As has been the case all year, the main support for growth is the external sector. Analyst sentiment towards exports thus far remains quite positive. One of our main watchpoints in the weeks ahead is the state of China-Europe trade relations. The EU’s lead trade official, Maroš Šefčovič, is in Beijing this week to float proposals – such as voluntary export restrictions on hybrid vehicles – to head off protectionist measures coming from Brussels. Chinese interlocutors on our trip were skeptical that the two sides will avoid a “slow-burn trade war” starting this fall but did not view it as a major threat to China’s overall export sector.

In the meantime, analysts have become less positive about the impact of Beijing’s “anti-involution” campaign, which had been an area of enthusiasm since summer of 2025. The campaign seems to be losing momentum and efficacy. A key reason is that lack of demand-side support to the economy, which limits the efficacy and political will of efforts to constrain new supply.
  1. Bottom Line: Macro and Equity Market Outlooks are Subdued

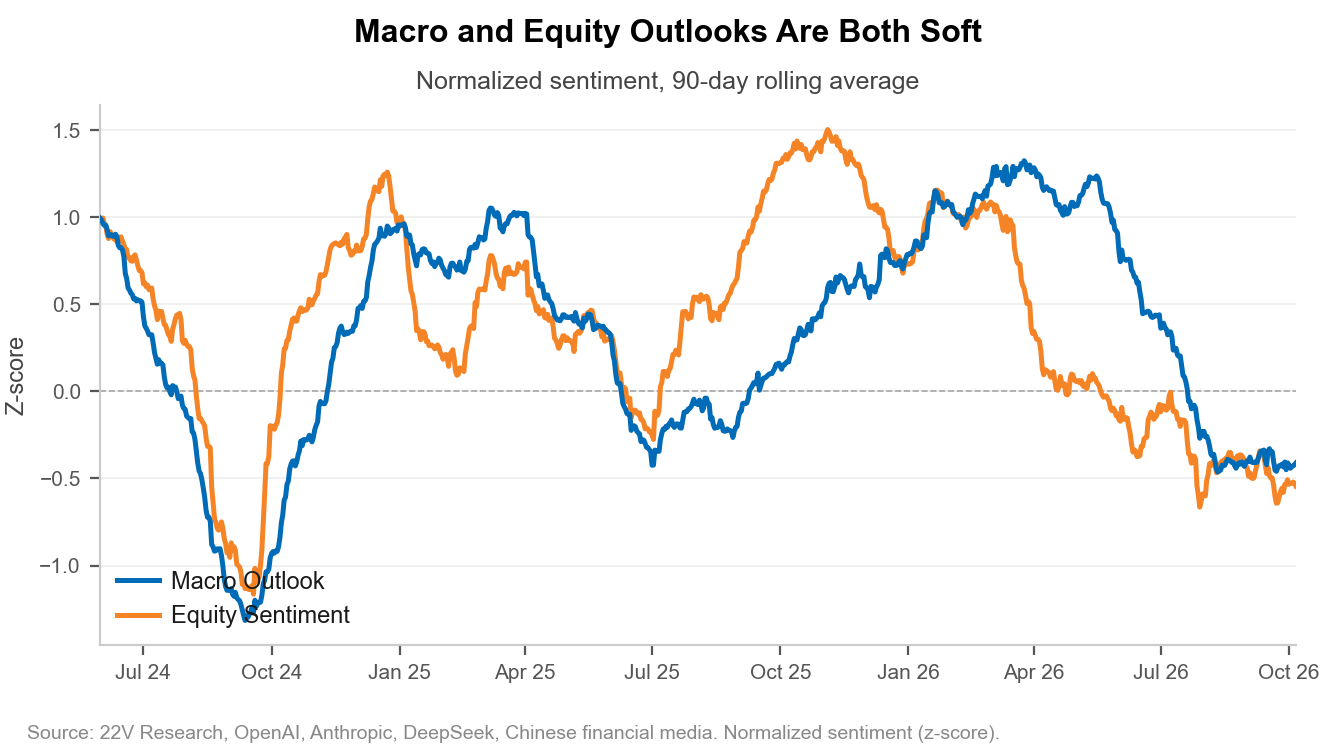
Exports are too small of an economic base to carry overall growth, and especially to drive an improvement in the labor market. The result is that analyst sentiment towards growth is net negative, measured against its historical average.

Analyst sentiment toward the equity market started to decline earlier in the year and has continued to drift downwards. The excitement in the equity market focuses on high-profile tech IPOs, of which more are coming in H1 – likely to include Moonshot AI (maker of the Kimi model), memory chipmaker YMTC, and AI national champion DeepSeek. However, a weak demand outlook limits the hopes for broad profit growth.
Near-Term Watchpoints:

  • October 19, China Q3 GDP: Unlikely to move the needle on stimulus
  • October 15-16, European Council summit, Brussels: European leaders will meet to determine next steps in the China trade dispute
  • October 19-22, Financial Street Forum in Beijing: Policy color from officials and economists
  • Late October, Q4 Politburo Meeting on the Economy: Unlikely to bring major new measures, as planners have turned attention to 2027

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.