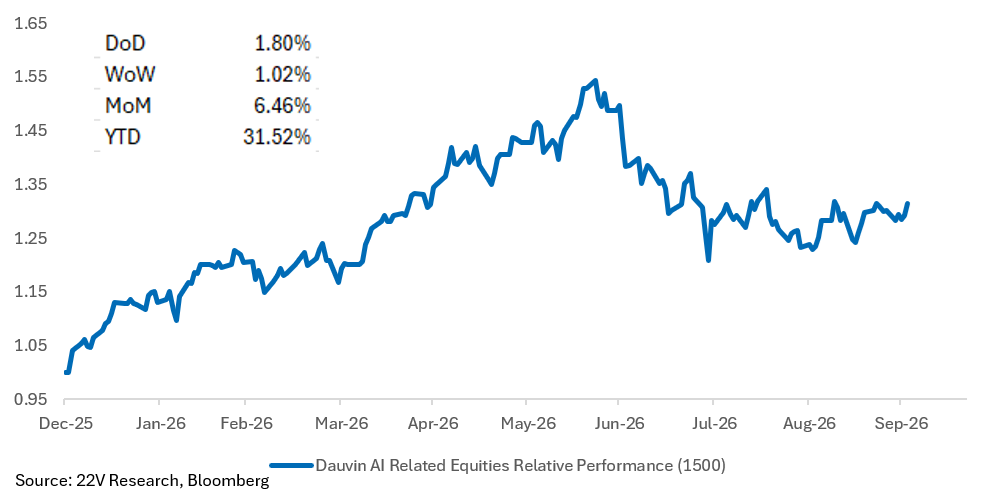
Bottom Line: The Path to the Market’s 4-5 hikes
To realize the market’s 4-5 hike path requires inflation at or above the current Fed forecast (Fed forecast is 3.4%, to reach this MoM core PCE would need to come in at 0.33%) and a labor market that keeps retightening (urate below 4.0%). Strong GDP growth, defined as real GDP growth above the economic speed limit of roughly ~2%, with inflation in line with Fed forecasts will keep rates elevated but not lead to more than 2-3 cumulative hikes.
Relevant News: Payrolls
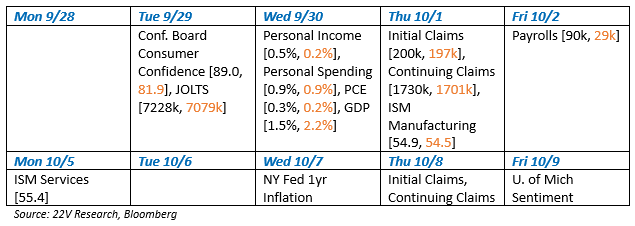
The September employment report was a tale of two surveys with soft payrolls and AHE prints versus an on net strong household survey. The Fed has deemphasized NFP relative to the unemployment rate and jobless claims given the weakness in underlying labor supply growth. This report aligns with that view as most measures of slack tightened on net despite weak payrolls but recent soft AHE growth in several sectors pushes back on inflationary worries for now and seems to have been the key part of the release. While labor market slack does seem to be improving, that observation has to tie into demand pressures on inflation which the AHE data lean against for now. Barring outsized surprises and shifts in labor market trends, it is the inflation data (near-term) and outlook (with influences from supply shocks, AI boom, and labor markets) that is driving the Fed at the moment.
Things to Watch [Consensus, Results]:
Strategy:
Europe’s impact on US assets – (HERE)
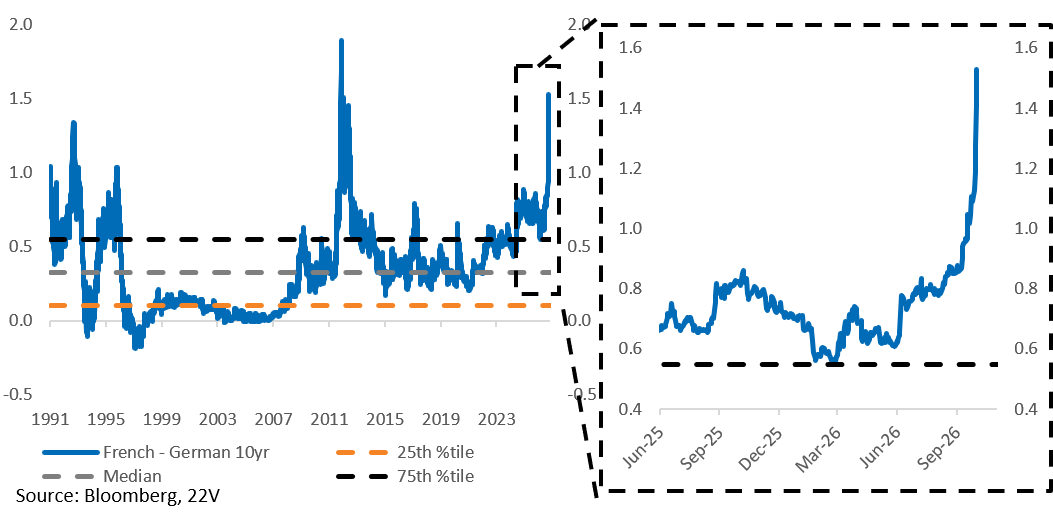
European risk assets have been under pressure recently and that intensified yesterday. Some EM currencies have the same issue. The Euro, the Mexican peso, European bank stocks as examples have traded poorly of late but accelerated lower yesterday. The increase in Energy prices and rates does impact the rest of world MUCH more than the US. The demand shock from higher energy prices will be born much more by the rest of world. Sovereign debt risk in France is an additional headwind for European assets. In short, the USD has tailwinds as US economic growth trends diverge further from European and many EM countries. Also, an increasing 10yr yields has generally been a dollar support.
Data Infrastructure / Commodities:
The AI Trade: Updated “Coiled Spring” Report and Data– (HERE)
22V Data Infrastructure/ commodities analyst, Dauvin Peterson, has identified a group of 91 AI capex exposed companies (the breadth of these companies benefit from strong AI demand), grouped into 12 segments (HERE). These are names that have seen significant multiple compression since mid-year and in many cases rising earnings estimates. The Strategy team would be long this basket now and think the names will outperform relative through 3Q26 EPS season.