

In my note last week, I mentioned that a somewhat surprising improvement in the US external accounts since earlier this year has made the short dollar theme less attractive. I follow up briefly in this note with a picture of how the dollar has recently been doing.
Probably the single best measure of the dollar’s overall performance is the Fed’s series of trade weighted exchange rate indexes. The media and some analysts prefer to look at DXY or nearby alternatives, I suspect in part because they are reported live, rather than with a lag extending occasionally just over a week, as in the case of even the daily value of the Fed indices. But we know the equation for the Fed measures and we have access to bilateral rates in real time, so it is no trick to fix that minor problem with the Fed measures.
The top left panel of the chart above shows a decade long run of the daily value of the Fed’s nominal index, with an estimate today at 2:00 PM EDT. Note that the dollar lost about 10% of its value from a post-1980s peak roughly at the time of Trump’s inauguration to its interim low almost exactly a year later. This decline came in two waves, with the initial one being steeper. But the dollar has recently returned to the top of the range that has held since that interim low. I suspect that the stabilization has to do with the external accounts, although the strength very recently is pretty clearly linked to the Fed.
The lower panel of the chart shows a longer run of history of the real value of the dollar, controlling for differentials between the inflation rate in the US and those in America’s trading partners. When zooming out like this, we see that the initial downdraft in the dollar after Trump’s inauguration has not been very large by historical standards. And this does fit into my view that movements of the dollar are very often less dramatic than breathless media commentary can let on.
The dollar looks fairly high in real terms by historical standards, but I am not sure that short dollar on the basis of valuation alone is very compelling here. The reason is that the energy renaissance in the US has probably moved up the equilibrium value of the real external value of the dollar, although in a way I would be pressed to quantify. Sometimes it is appropriate for a macro generalist to take a swing at the dollar, but that time has passed for now, so far as I can tell – or manage.
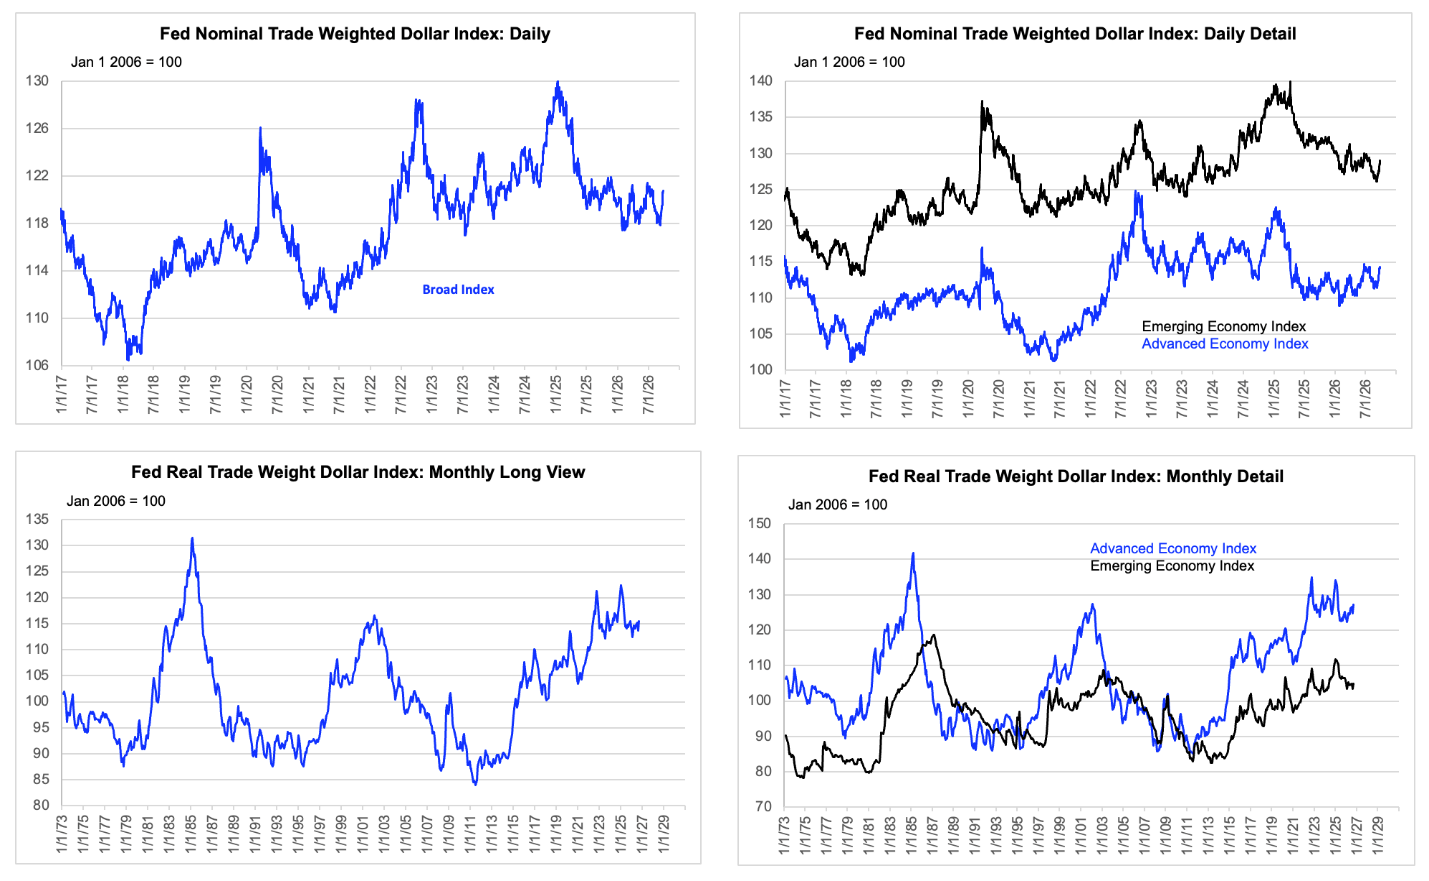
Daily indexes in top row are official to September 18 and estimated to 2:00 today. Monthly index are actual to August and estimated to 2:00 today, based on nominal exchange rates.

