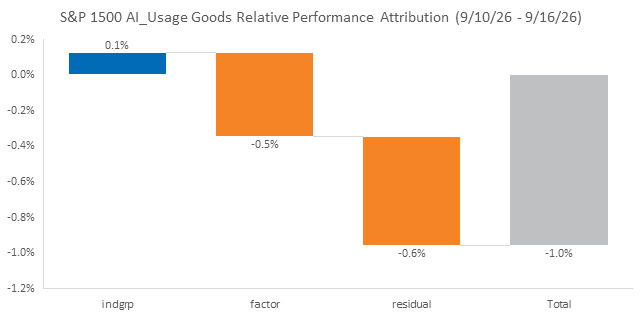
DAILY STRATEGY & WEEKLY AI Update: Performance within AI themes is consistent with our view that the FOMC was a bit more hawkish than anticipated but doesn’t change the central case for markets (HERE). Mild policy tightening and slowing of economic growth helps anchor inflation expectations but doesn’t increase recession risk. It increases the odds that the economic cycle last longer. Markets will be range bound as we go through the process of economic growth slowing and financial conditions tightening, but fundamental factors and stock/theme picking will benefit. Quantitatively, a decomposition of our AI baskets’ returns shows that idiosyncratic risk was still a large share of returns this week.
The macro backdrop of economic growth slowing in non-AI areas of the economy, but without meaningfully higher recession risk, implies 1) investors will reward strong eps growth and cash return, which is a tailwind for AI Services that have implemented AI, and 2) activity and investment in the AI buildout will continue to outpace non-AI cyclicals. As Dauvin Peterson, head of 22V Data Infrastructure/Commodities research has been noting (most recently HERE), compute shortage remains one of the most powerful (and investable) themes.
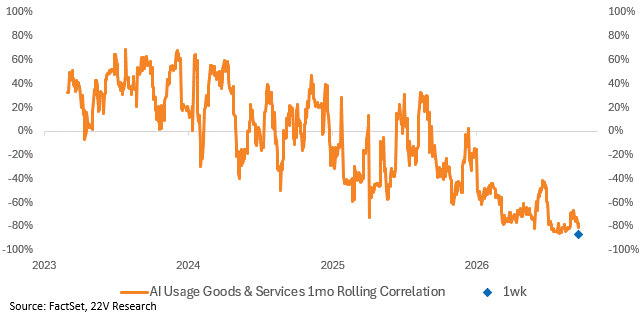
The two together imply that the negative correlation between AI Service and AI Buildout names will fade over time. The rolling correlation between the two baskets is still deeply negative (latest 1mo and 1wk both ~-80%), so the themes working together would be a major change.
AI headlines will continue to generate volatility that can overwhelm the macro backdrop, like the potential AI development slowdown news from this weekend, but if the macro backdrop does inform the direction of travel, it’s towards the buildout AND AI implementation working together.
Interesting articles and themes that have come up in conversations related to AI this week:
1) From our former colleague Ernie Tedeschi who is now at Stripe. Just like the AI jobs apocalypse was greatly exaggerated, so has been the SaaSpocalypse. At least as far as current business trends are concerned.
2) We have heard multiple people note that AI lab revenue must reach $1 trillion by 2029 to keep up with the hyperscaler (mag 5) capex. And how just replacing coding workers will not get to $1 trillion. It will take a much broader group of knowledge work companies to hit that mark The concern is that the rest of knowledge work will be slower to adopt AI tools. The ability of AI to spread to the rest of knowledge work will be an increasing focus for investors.
Charts…
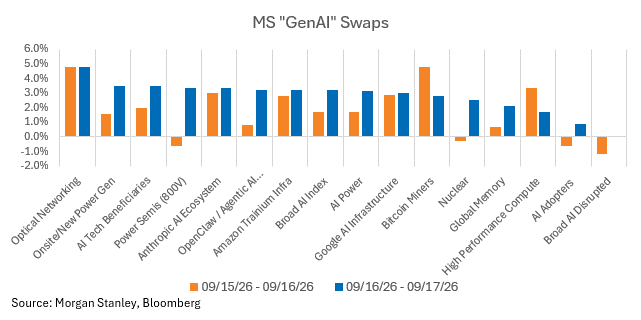
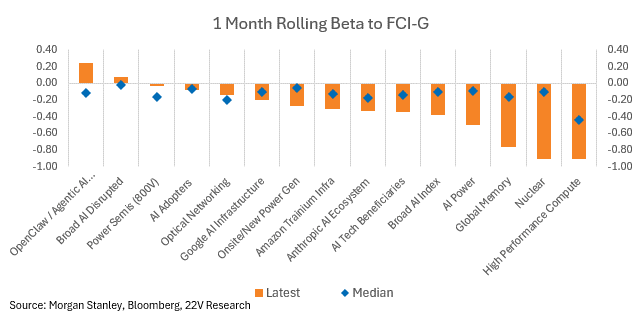
Two-day performance of AI themes around the FOMC, when compared to the recent beta of the baskets to financial conditions, implies that financial conditions were not the main mechanism for AI basket performance.
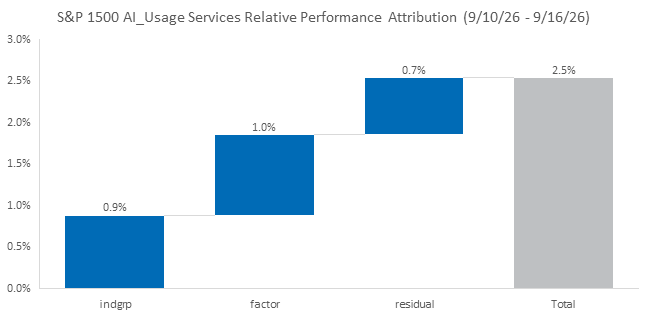
A decomposition of the returns of our own AI Goods and Services baskets shows that idio is a large contributor to returns, helping prove the point made above.
Source: FactSet, 22V Research
Source: FactSet, 22V Research
Our AI Services basket – non-Goods companies that have specified use cases of AI in earnings calls – has a deeply negative correlation with our AI Goods basket – a proxy for the AI buildout theme. The macro backdrop supports a less negative correlation going forward, though idiosyncratic risk is still highly relevant.