Back Economics

Warsh is so far mostly hurting himself

Published on July 31, 2026

∙ Download the PDF Report

By

Gerard MacDonell

Main point: Wednesday was fun to watch, or read about in my case. But I don’t think it captures the primary trend here. Warsh is mostly hurting himself, thankfully.

The spectacle of an impostor being called out in real time by the most efficiently priced asset class on the planet is admittedly hard to look away from. And on the day, most of the repricing there involved increases of inflation premia, rather than real rates, at least as proxied by the TIPS market. Warsh looked and sounded like a simp, and the bond market priced a bit more inflation.

But if we zoom out a bit, I think we can see that the theme of the day on Wednesday is not the primary trend here. And the idea that Warsh is already driving up risk premia seems premature. For example, I have been looking for a steeper yield curve for a couple years now, because of the huge flood of duration supply implied by the surging federal debt and the recent switch of the stock-bond correlation away from an ice regime. (This argument has little to do with inflation or even fiscal worries per se, except to the extent that this influences the stock/bond correlation.) The curve has tended to steepen over this period, although at short horizons the curve is much more dominated by the rates outlook itself. But the reason I mention this is that the yield curve does not seem to have overshot on the basis of some other consideration. And relatedly, I think it is a mistake to claim that Warsh has already caused risk premia to blow out. (There is more likely than not more yield curve steepening in front of us.)

Instead, I think something else is going on. And one aspect of this other thing that is interesting (to me) is that it is something that a lot of folks expected. Recall that when Warsh was appointed, there was a group of Fed watchers who thought the appointment was a mistake but who were not particularly worried about it undermining the inflation outlook. Either Warsh would tack to the center on his inflation views or he would lose credibility and the power on the FOMC would shift out to the broader committee. If Elvis loses his singing voice, he does not get to call the tune, as my pal mentioned.

In the event, both elements of the non-panic take seem to have played out. For example, Warsh has made a great show of talking tough on inflation, for whatever that is worth. He has also quietly dropped – or delegated to task force — some of his dumber arguments for dovish monetary policy, like the AI boom or the Trimmed Mean inflation rate. And even on Wednesday, he did suggest that he saw the case for restraint from higher interest rates. It is just that he made a fool of himself rationalizing how that would work, although in a way that ultimately concedes the case for rate hikes. He is not acting in the worst-case dovish way. This is probably in part because he is disciplined to some extent by the fear of losing his credibility on the committee.

And yet, the second aspect of the non-panic take is also playing out. That is, Warsh does seem be frittering away the authority that comes with the role, and a bit more quickly than even his harshest critics expected. I am reminded of this point, and prompted to write this note, by Paul Krugman’s most recent Substack post, whose title is inappropriate to family macro. I know Krugman wears his politics on his sleeve and is not to everybody’s taste. But think this snippet apt:
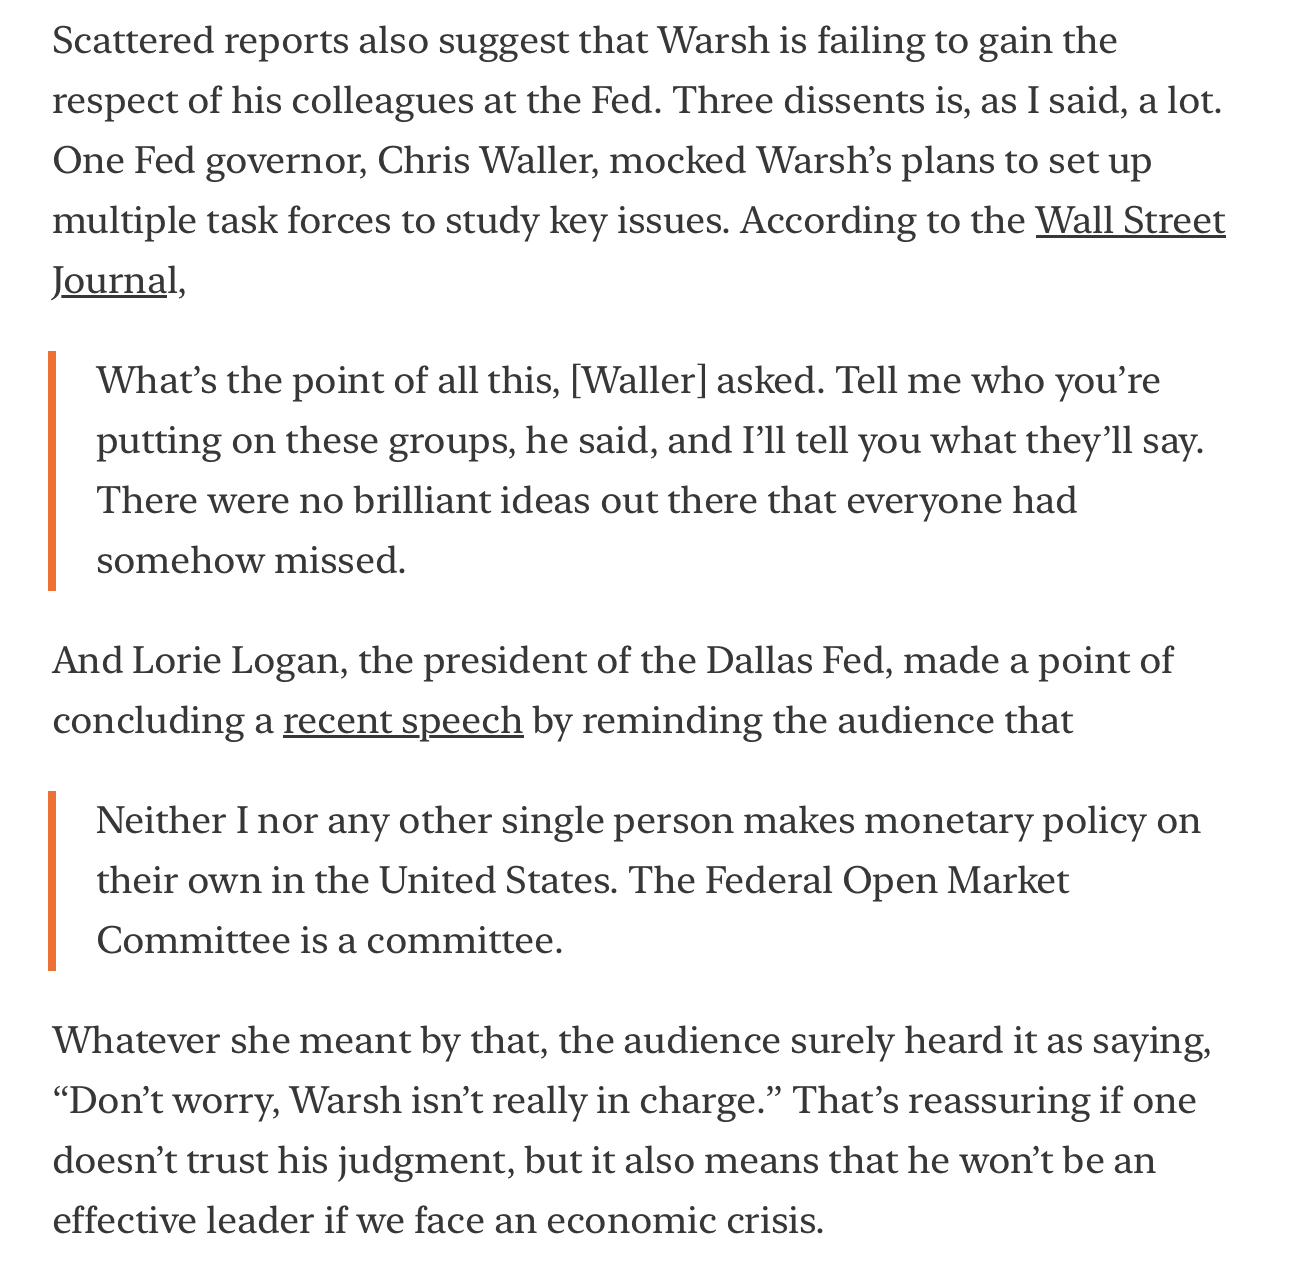
Source: Krugman, linked above

I particularly like the concluding point about the risk of not having sturdy leadership in the event of a crisis. And I concede that even with this check on the guy from the broader committee, and from the fact that he presumably has some dignity and does not want to be judged a fool, the risks around inflation over the longer haul are probably skewed to the right. But for the most part, the damage Warsh has been doing has been mostly to himself. And I would avoid mistaking my view on what markets should be doing with what they have done, the striking example of Wednesday aside.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.