Results: Huntington Bancshares reported GAAP EPS of $0.33 and adjusted EPS of $0.39 (excluding $152 million pre-tax / $116 million after-tax of acquisition-related notable items tied to the Cadence systems conversion). GAAP ROTCE reached 15.1% and adjusted ROTCE reached 17.5% on an annualized basis, with LTM adjusted ROTCE of 16.7% — continuing a trajectory toward management’s 2027 target of 18-19%. Adjusted PPNR of $1,198 million grew 12% QoQ and 46% YoY. Tangible book value per share rose to $9.65, up 6% year-over-year and represented a 10% CAGR since 2Q 2023. While on a PPNR basis HBAN was largely in line w/consensus, NII came in ~1.8% below expectations with strong fee income making up the difference.
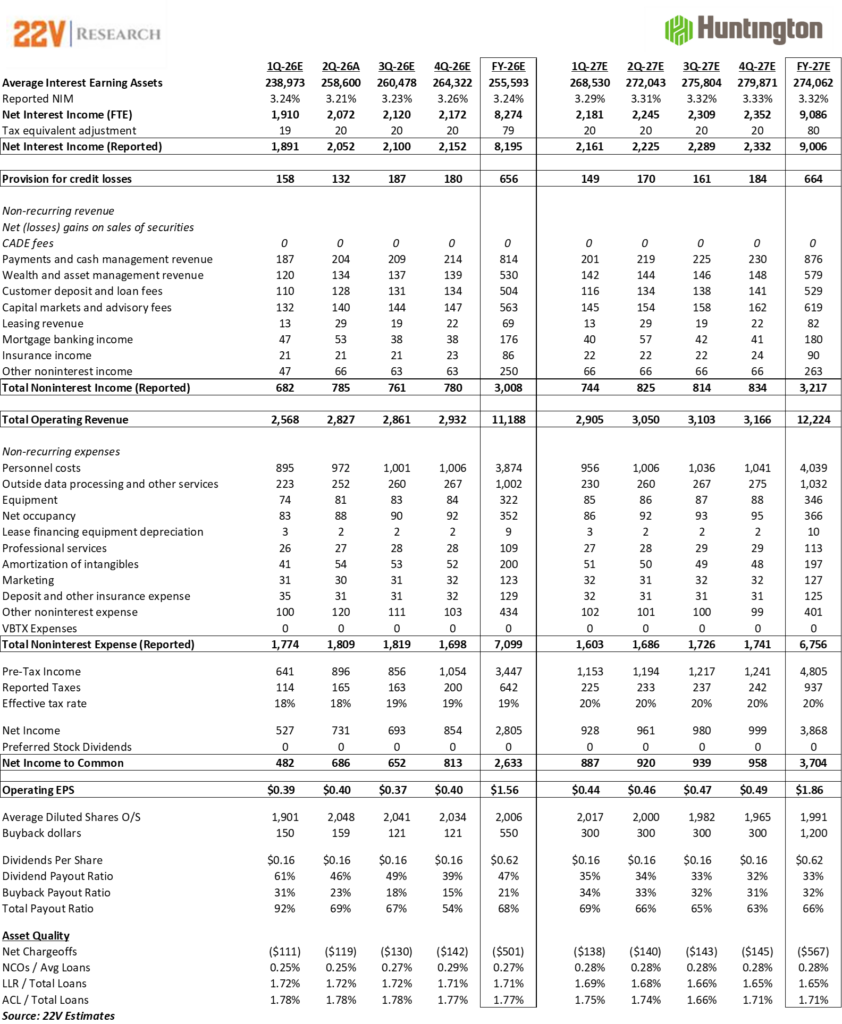
Balance Sheet Highlights: Average loans and leases grew 8.6% sequentially to $189.3 billion (+42.1% YoY), with organic growth of 1.2% QoQ after normalizing for the full-quarter Cadence day-count effect — led by C&I categories including Corporate and Specialty Banking, Asset Finance, and Middle Market. Average deposits grew 9.2% sequentially to $223.4 billion (+36.7% YoY), with organic growth of 1.8% QoQ outpacing loan growth, supported by primary banking relationship across consumer and commercial. Net interest income (FTE) grew to $2,072 million (+8.5% QoQ, +39.7% YoY), while NIM of 3.21% declined 3 basis points sequentially due to the full-quarter Cadence impact and higher funding costs; management views 2Q as the NIM trough and expects expansion into the low-to-mid 3.20s in the second half of 2026.
Integration: The Cadence Bank integration was completed in the quarter, with systems conversion finalized in mid-June 2026 — the final major integration milestone. Cadence cost synergies reached a $70 million annualized run-rate in 2Q, with $365 million expected by 4Q 2026 and $435 million in total by 2027. Revenue synergies are on track for $50-75 million in 2026 and management continues to target $500 million cumulatively by 2028, with early momentum in Capital Markets (10+ completed transactions generating ~$12 million in fees), digital deposit acquisition (up 60% since January), and deposit deepening in the Cadence footprint (liquid deposits now 80% of Cadence volume vs. 40% at acquisition).
Fee Income: Fee revenues grew sharply, with total noninterest income of $785 million up 67% year-over-year; on an organic basis (excluding acquisitions and the prior-year Corporate Trust sale), fee growth was approximately 30% YoY, led by Capital Markets +46%, Wealth Management +12%, Payments +10%, and Customer Deposit & Loan Fees +19%. The adjusted efficiency ratio improved to 56.1% in 2Q from 57.0% in 1Q, with management continuing to express confidence in a path toward the low-to-mid 54% target in 4Q 2026.
Credit & Capital: Net charge-offs of 0.25% of average loans were near the low end of the guided 25-35 basis point range and management tightened the NCO guidance to the lower half of that range for the full year. The ACL coverage ratio held steady at 1.78% and the criticized asset ratio declined to 4.18% from 4.33% in 1Q. That said, the NPA ratio increased 13 basis points to 0.85% across most major categories. While the resi mortgage piece is government guaranteed, C&I non-performers were up ~20% and CRE non-performers were up 29%. On capital, CET1 of 10.0% and adjusted CET1 of 9.0% remained within the 9-10% target range; the company repurchased $160 million of shares in 2Q ($310 million year-to-date) and expects at least $550 million in total FY 2026 repurchases, rising to $1.1-$1.2 billion in 2027.
Our take: With HBAN’s stock finishing the day down 4.76%, we think it’s best to look at where we shake out relative to management’s guidance:
NII/NIM: The major culprit in today’s underperformance, the smaller average balance sheet from releasing the excess liquidity combined with the lower NIM leaves HBAN in a tough starting point relative to the 39-43% NII growth guide for the year. With the loan growth HBAN is trying to generate, they also need to raise the deposits to fund the growth. We saw 6bps of deposit cost increase QoQ (1bp from CADE, 5bps from legacy HBAN) which helped drive the 3bps of NIM compression. Management has called out a continued “modest” increase in deposit costs from here which we have built into our forward estimates. To be clear, we have also built in some lift in loan yields given the strong loan growth projections as well as some lift in securities yields as we expect HBAN to be adding there as well. The net effect is to have NII up 36.6% this year vs. the 39-43% growth guide where management pointed to the low end or even below the low end of the guide. We have our 4Q NIM finishing at 3.26% in 4Q relative to the guide of mid-high 3.20’s%.
Fees: The bright spot in the Q, fees were ~6.9% ahead of VA consensus. Management is guiding to the high end or above the 31%-33% most recent guide. Given the strength this Q and the fact that 1H’26 is up ~40% vs. 1H’25, we see HBAN handily exceeding the guide. Our estimate is +35.5% for FY’26 which would assume a slowdown in 2H’26 to ~30% YoY growth.
Expenses: Given the fee overage this Q, expenses were ~0.9% higher than consensus which we think is a fair trade-off. Even though management is guiding to the middle of the 32.5%-33.5% expense range for the Q, we’re at 34.6% given what we expect to be better fees in 2H’26. We do not reach the mid-low 54% efficiency ratio in 4Q. We finish Q4 at 55.75%.
Credit: As mentioned earlier, C&I non-performers were up ~20% and CRE non-performers were up 29% linked-Q. While we have HBAN at the low half of the net charge-off guide, continued credit migration as we saw this Q could alter that path.
In sum, we are lowering our FY’26/FY’27 operating eps estimates from $1.60/$1.91 to $1.56/$1.86 and below the FY’27 guide of $1.90-$1.93. We believe the range of outcomes at HBAN has widened given the slower NII start (need for more growth/potentially more deposit price pressure). While credit costs and tax rate can always be swing factors to help get to an eps outcome, our PTPP/share estimates come down 3.1% and 1.8% respectively for FY’26/FY’27. We believe any multiple expansion will likely be limited in the near term until we have better line of sight on FY’27 estimates.
Company Statistics
Stock Rating:
Sector Perform
Price:
$17.40
Price Target:
$19.50
52-Week High:
$19.46
52-Week Low:
$14.89
Market Cap:
$37.036B
Dividend Yield:
3.4%
Financials
2025
2026
2027
Revenue (MM)
$8,166
$11,203
$12,224
EPS Estimates
Q1
0.34
0.25
0.44
Q2
0.34
0.33
0.46
Q3
0.41
0.32
0.47
Q4
0.30
0.40
0.49
$1.39
$1.31
$1.86
Consensus EPS Estimates
Q1
0.34
0.25
0.44
Q2
0.34
0.33
0.46
Q3
0.41
0.40
0.49
Q4
0.30
0.44
0.51
$1.39
$1.56
$1.88
P/E FY
$12.5
$13.3
$9.4
One Year Performance Chart
*Source: EOD Historical Data
HBAN 3 Year Price History
*Source: EOD Historical Data
Current Rating Distribution
Coverage Universe
Percent
Sector Outperform
31.25
Sector Perform
50
Sector Underperform
18.75
DISCLOSURES AND DISCLAIMERS
Analyst Certification
The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.
Analyst Certifications and Independence of Research.
Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.
22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.
22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.
Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.
SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).
SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).
SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).
Limitation Of Research And Information.
This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.
Reproduction And Distribution Strictly Prohibited.
No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.
Copyrights, Trademarks, Intellectual Property.
22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.