- Guidance Upgraded; Amazon Partnership Adds Near-Term Momentum. Management upgraded full-year 2026 total net revenue growth guidance to +7%-9% YoY (inclusive of BTIG). Ex-BTIG, USB raised their organic revenue guide from the prior +4%-6% range to +5%-7%. Positive operating leverage guidance was maintained at approximately 200 basis points including BTIG and 300+ basis points excluding BTIG. For 3Q 2026, management guided NII growth of +4%-6% vs. 3Q 2025 and fee revenue growth of +12%-14%, with total noninterest expense growth of approximately 8% (core ex-BTIG: ~3.5%). The anticipated mid-August close of the Amazon small business co-brand card portfolio (~$1.6 billion of loans transitioning from Amex/Mastercard) represents an incremental $75-85 million per quarter in total revenue (approximately 2/3 NII, 1/3 fees) once fully ramped in 4Q 2026, with a $160 million reserve build expected at closing. NIM expanded 2 basis points sequentially to 2.79%, and management reiterated the path toward 3% NIM in 2027, with fixed asset repricing ($10-11 billion per quarter at ~100-125 basis points of pickup), improving earning asset mix, and the Amazon portfolio all cited as tailwinds.
- Credit Quality Improving; Capital Position Solid. Credit quality continued to improve across the board in 2Q 2026, reflecting a stable macroeconomic backdrop and broad-based client health that management characterized as not overly concentrated in any single sector or theme, including AI/data centers. The NPA ratio fell to 0.33% (-5 basis points linked quarter, -11 basis points YoY), net charge-offs declined to 0.53% (-3 basis points LQ), and the credit card NCO ratio improved to 3.83% (-13 basis points LQ, -47 basis points YoY), with delinquencies across 30-89 and 90+ day buckets also declining sequentially. The allowance for credit losses stood at $8.0 billion (1.94% of period-end loans) with only a nominal $2 million net reserve build. Capital remained stable at a CET1 ratio of 10.8% (9.4% including AOCI) despite absorbing the BTIG acquisition (~12 basis points of CET1 impact) and strong loan growth, with $200 million in buybacks completed in the quarter. Management confirmed it is on the “last lap” of capital build, intending to glide total capital return higher toward the 70%-75% long-term payout target as CET1 approaches approximately 10% on an adjusted basis, and announced a planned ~4% increase to the quarterly common stock dividend beginning in 3Q 2026 (subject to Board approval).
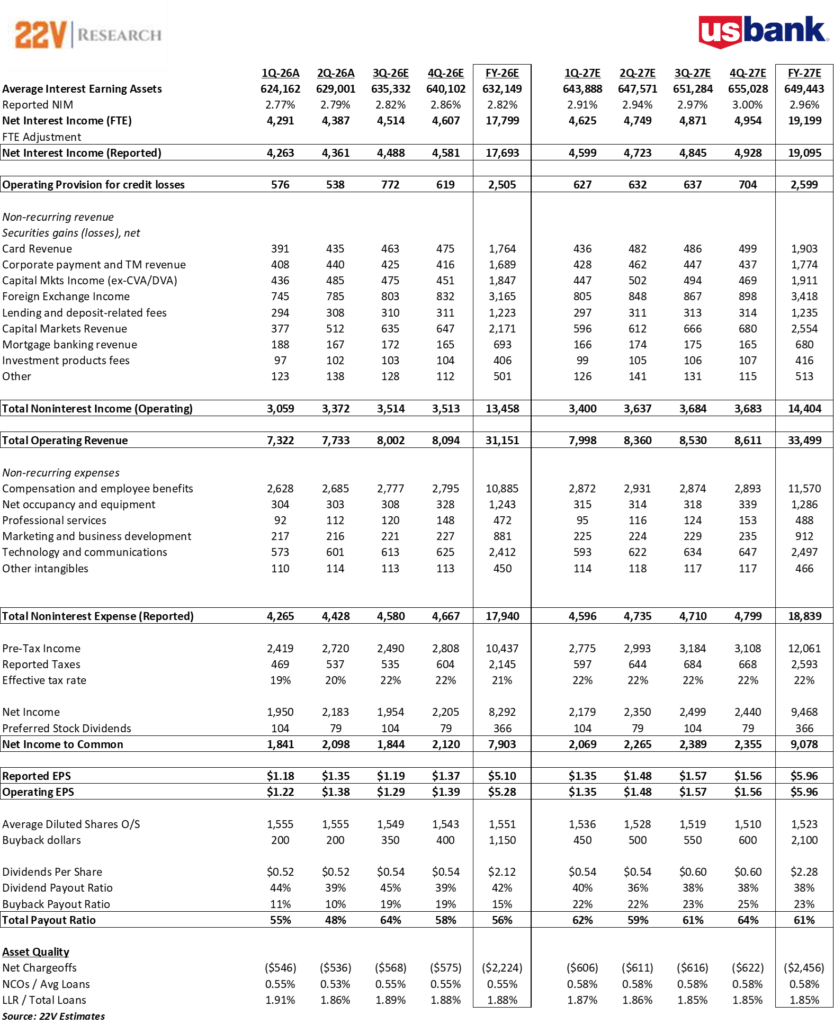
Our take: We believe this quarter, while a bit noisy with the inclusion of a partial quarter of BTIG, is yet another step in the USB re-rate story. The only drawback we saw in the Q was the step back in the merchant processing business due to the weakness in Europe and the loss of some non-strategic distribution partners. That said, USB did a good job offsetting with the BTIG addition and the strength in the underlying capital markets business which along with the addition of the Amazon portfolio next Q will offset the tougher merchant processing compares in the next few quarters. In terms of the key drivers going forward, we see continued fixed asset reprice as a bigger tailwind for USB given the absolute level of their current margin (easier to move the needle higher when your margin is 2.79% vs. RF or MTB ~3.7%) and the ~$10-$11bil rolling each Q. We’re at the high end of next Q’s 4-6% NII guide (we’re at 6.2%) as well as the fee guide of +12-14% (we’re at 14.3%), and have full year NII at 6.3% growth vs. USB’s “north of 5%” estimate. For FY’26 total revenue, we’re at +8.5% relative to the +7-9% guide which contemplates ~235bps of positive operating leverage. As we’ve mentioned in past notes, USB is also in a unique position in that their capital return is accelerating while peers are begin to decelerate. We’re estimating that their buyback will double by Q4 vs. the $200mm this Q and ramp further in ’27. We raise our estimates for FY’26/FY’27 to $5.28/$5.96 from $5.18/$5.83. We raise our target to $70 which is ~12x our new ’27 estimate. As we look at our forward PTPP/share estimates relative to consensus, we’re now 0.6% ahead for ’26 & 2.0% ahead for FY’27 which is even better than the 1.5% ahead pre-Q for FY’27. In sum, we believe the USB re-rate continues to accelerate with the better NII glidepath meeting better fees and more capital return. With our Q4’27 NIM at 3% and better fees/more capital return, we see USB consistently hitting their medium term ROA/ROTCE and efficiency targets. As such, we reiterate our Sector Outperform rating.