Back Shoot Around

22V Afternoon Shoot Around: Hyperscaler Capex, US-China Risks, and a Europe Update

Published on July 17, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: UST Yield Points

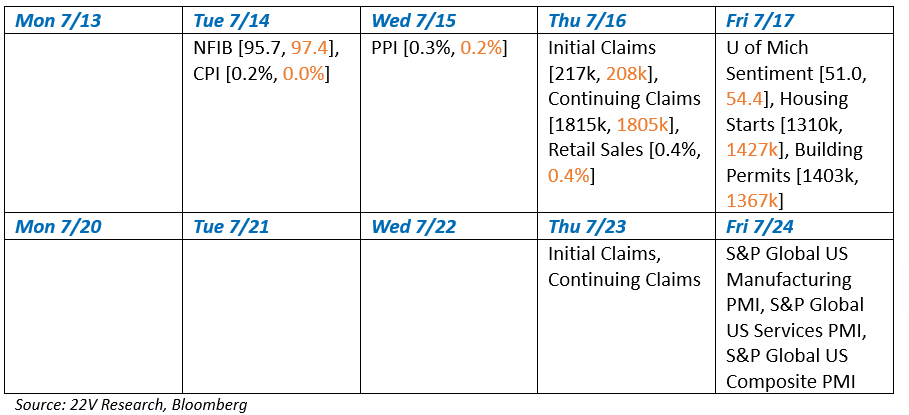
Near term inflation risk, that would have led to tighter financial conditions has been lowered post CPI/PPI, but it is not gone. The Retail sales report indicated real personal consumption expenditures are running at +2%. As Gerard noted, there is a positive launch effect for Q3. The launch indicates real consumption will stay at +2% for 3Q. In short, the combination of +2% Real consumption and strong capital spending (~1% contributor to GDP growth) suggests economic growth is strong enough that inflation RISK will remain elevated. The above is why a September hike is still a coin flip and expect 10yr yields to hover around the 4.5% level for now. A slowdown in economic growth or labor market is necessary for 10yr yields to move much below 4.5%.

Relevant News: Rest of World Influence on UST Bonds

As John Roque pointed out yesterday, French 10-year yields are at their highest level in 17 years. John notes that G-7 bond yields trend homogeneously over time. The move in G7 bond yields reflects a broader shift to a higher-rate regime, driven by persistent inflation risks, large fiscal deficits, elevated government bond issuance, and stronger-than-expected economic growth rather than a temporary country-specific story. In short, don’t expect a sharp move lower in UST yields when the rest of G7 yields are moving in the opposite direction.

Things to Watch [Consensus, Results]:
Strategy:

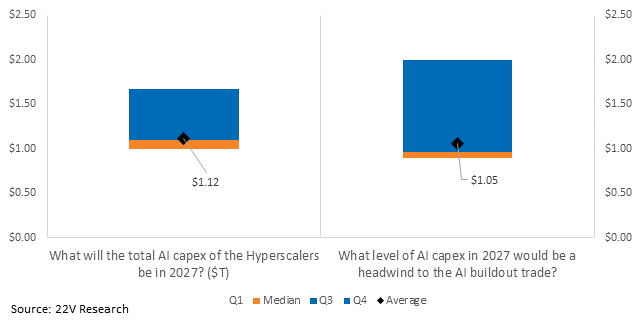
Investor Focus on AI Capex Signals – (HERE)

Most investors expect the level of Hyperscaler capex in 2027 (median $1.1T) will support the AI buildout trade. Investor estimates for 2027 Hyperscaler capex range from $1T to $1.7T, with a median estimate of $1.1T. Investors have a wide range of estimates for what level of capex would be a headwind to the AI buildout trade, ranging from $900B to $2T. The median estimate is just under $1.1T.
A comparison of a graph

AI-generated content may be incorrect.

China:

US-China Risks Are Rising: Trump Speech | AI Competition– (HERE)

Thursday’s developments highlight rising strain in US-China relations across both politics and technology: Trump’s election-interference accusations risk complicating Xi’s planned US visit, while China’s rapid AI progress—underscored by Moonshot’s Kimi K3 and Xi’s support for open-weight models—intensifies competition and will lead to increased calls to slow China’s advance through tech restrictions. Together, these dynamics show the pressures building on the tech and supply chain truce that has been in place since last fall. Risks are rising that, post-US midterm elections, the US imposes new tech restrictions and China responds through tightening rare earths exports. The key near-term watchpoints are planning for Xi’s visit and how both sides manage the escalating AI rivalry.

Europe:

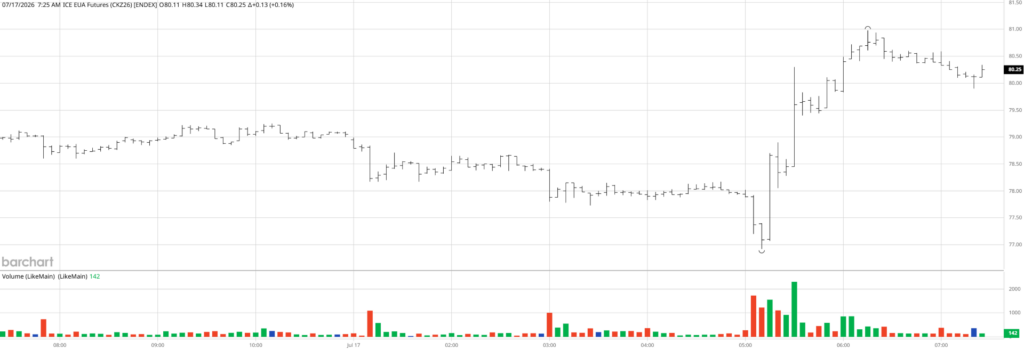
Iran Standoff Continues To Go Around In Circles And The EU Stays The Course of Carbon Pricing – (HERE)

First, the base case remains a prolonged but contained U.S.-Iran conflict: while rhetoric and limited military escalation have intensified, muted oil prices reduce pressure for a diplomatic breakthrough while also making a return to full-scale war less likely. The key variable remains oil—if prices stay contained, a “no war, no peace” equilibrium of low-intensity conflict could persist, whereas a sustained move above $100/barrel would likely push the Trump administration back toward negotiations. Second, the European Commission reaffirmed its long-term commitment to decarbonization by strengthening the EU Emissions Trading Scheme and expanding electrification initiatives, signaling continued reliance on carbon pricing despite competitiveness concerns and the likelihood of prolonged negotiations before implementation.
Source: ICE

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.