

I The Trump Administration appears intent on continuing its resumed military campaign against Iran, and Donald Trump has revived his threats to possibly strike Iranian power plants and other critical infrastructure next week, as well as renewed targeting of Iran’s nuclear program. Iran for its part has again warned that such strikes would see infrastructure across the Gulf region attacked, and Houthi leaders in Yemen has threatened to strike oil infrastructure in Saudi Arabia if Riyadh continues strikes on Yemen, and may try to close the Bab-al-Mandep Strait to the Red Sea, should the U.S. escalate to infrastructure strikes inside Iran.
This mirrors a lot of the rhetoric between the two sides earlier in the conflict, where Donald Trump also threatened the “annihilation of Iran”, and Tehran crushing retaliation. We have been here before, and the threatened escalation didn’t in the end materialize in May-June, and it remains the base case that full-blown war will also not return now. Subdued oil market price effects to date, however, adds uncertainty to this outlook.
CENTCOM yesterday launched its sixth day of heavy air strikes on military and some bridge infrastructure targets inside Iran and especially around Bandar Abbas, while Iran has repeatedly fired on ships in the Strait of Hormuz, at U.S. bases in the Gulf region and now also at infrastructure in Kuwait.
Traffic through the Strait of Hormuz has dropped back significantly in recent days to not far off pre-ceasefire levels, though Brent oil prices (August Contract) has hovered around just $80/barrel this week, despite the U.S. embargo on Iran coming into effect again and the sanctions waiver being annulled.
As long as this situation persists, Donald Trump will not face dramatic push-back to his current and once again more militarized strategy to confront Iran. This makes it less likely that diplomatic efforts will succeed in the very short-term.
At the same time, even as oil price effects remain muted, the fundamentals of the conflict have not shifted. The United States (Israel no longer participates directly in strikes on Iran) retains essentially complete air superiority over Iran and can strike targets more or less at will and facing limited risks to U.S. aircrafts. Yet, U.S. forces do not have the military capacity to stop Iranian strikes on transiting ships or regional American bases, and do not have the forces available to launch any ground assault on Iranian territory and certainly not “take control of the Strait”. This remains an “air only campaign” in other words from the United States.
Iran on its part continues to show its capabilities and strike ships in and around the Strait of Hormuz, and at U.S. regional bases, but have to date refrained from again striking directly and repeatedly at GCC urban centers and critical energy infrastructure.
Escalation looks plausible, if the U.S. continues to strike ever more Iranian domestic infrastructure – currently seemingly Iranian bridges around Bandar Abbas are an increasingly regular U.S. target – and the IRGC at some point decides to retaliate against the broader Gulf region, as strikes against U.S. forces are unlikely to deter new strikes against it.
Such escalated Iranian retaliation against the region, however, will come at significant political costs to Tehran, as it would set back to start all attempts at regional political reconciliation and hence undermine Iran’s seemingly preferred option to exercise future control over the Strait of Hormuz, namely through a regional institutional arrangement.
The reasons Tehran would want such an arrangement is that it likely recognizes that its own sole control of the Strait would be unacceptable to not just the GCC, but the rest of the world including its biggest trading partner in China. A regional solution hence is likely the only actually available long-term option for Iran on managing the Strait, as simply keeping it closed is not really a viable option, given the relatively limited oil price effects and since the U.S. Navy has the capacity to reciprocate in a blockade against Iran itself (including against empty Iranian linked tankers entering the Gulf, denying Iran floating oil storage).
Iranian leaders will also be aware that a credible regional solution is possibly the only option at has at its disposal to blunt the clear intent and incentives of the rest of the GCC countries to invest it “Hormuz bypass pipeline options” that will over time materially reduce the importance of the Strait to global oil markets, and hence the strategic leverage geography and drones give Iran.
It is likely that the GCC countries will make these investments no matter what, but a credible joint governance structure over the Strait might reduce or postpone the resource allocation to such bypass projects. Lastly, a joint governance structure would provide the outcome that the Strait of Hormuz do not “return to the pre-war status”, an often-heard Iranian demand.
The onus here remains on regional mediators to provide new and detailed diplomatic solutions for the future of the Strait.
At the same time, sequence matters greatly, given that Iranian leaders fearful of new U.S. attacks will surely want to hold on to its physical control of the Strait until such a time that a longer-lasting agreement can be signed, providing it with a degree of political assurances against renewed U.S. strikes. Deep-rooted mistrust lingers and complicates negotiations, even as the threshold for Iranian unrestrained retaliation against the Gulf region remains high, providing a window of opportunity for Donald Trump to continue even scaled up strikes against now Iranian bridges, too.
Despite this at least temporary opportunity, Donald Trump’s newfound freedom of action remains wholly dependent on a continued relatively benign oil market reactions. Were prices to suddenly rise back well above $100/barrel, as seen earlier in the conflict, Trump’s reaction function would – again – likely dictate a renewed diplomatic focus.
Such an outcome could materialize for several reasons, depending on the reasons for the – at least to me – surprisingly low oil price seen today. If prices remain low mostly due to the market conviction that “a longer-term deal remains imminent”, a continued escalation in tit-for-tat attacks between the U.S. and Iran could shatter this consensus. Already depleted and very low global oil inventories might also lead to a faster price reaction this time than when the war began in late February. Or perhaps China’s response function will this time be different.
As pointed out in a note by Michael Hirson and Houze Song yesterday (China: Q2 Slowdown Not Bad Enough to Trigger Major Stimulus), China’s reduced oil imports are likely (unlike in other parts of the world) due mostly to temporary measures other than permanent demand destruction. Beijing certainly retains considerable leeway to impact national oil import levels in the short term, but is unlikely to utilize them and reduce import levels unless global oil prices again rise materially from current levels.
Donald Trump may therefore in the near term suddenly once again face higher oil prices, only this time much closer to the mid-terms and at a time when the new Federal Reserve Chairman has signaled his intent to “get back to two percent U.S. inflation“, providing him with a clear economic and political incentive to avoid feeling the effects of another material rise in oil prices. This, combined with the desire for regional mediators themselves in the line of fire to avoid further escalation and hence double down on diplomacy, continues to make restarted negotiations the base case, rather than renewed all-out war.
The base case absence of total war once more, however, is no guarantee for a more formalized longer-term diplomatic solution, covering the main items included in the MoU with the Strait of Hormuz, Lebanon and Iran’s nuclear program (Iran’s ballistic missile programs, drones and support for regional proxy forces were not included in the MoU and hence are extremely unlikely to be included in any more permanent political agreement).
A “post-MoU situation” in which there is no formal U.S.-Iran agreement, but instead a highly unstable unresolved situation with frequent low-intensity tit-for-tat strikes may persist for a quite a while in the coming months.
The key parameter here will be the oil market reaction to such an outcome – if risk premia rise materially pressure will build on Donald Trump to eventually strike a deal, while still subdued prices will likely allow a “no total war, no peace agreement” situation to persist.
Another important parameter is the Iranian economy, which – despite the regime’s well-known ability to impose huge economic costs on its own citizens – may deteriorate to such an extent that Iran is eventually compelled to seek a deal. Such a “economic strangulation” scenario would, however, even in the most accelerated scenario take months to materialize.
In short, the U.S. – Iran standoff does not presently look likely to be solved diplomatically but will not descent into all-out war again. This situation is likely to persist until the broader economic spillover through global commodity markets once again forces Donald Trump to address the issue. If global oil market price effects on the other hand remain subdued, the current situation may persist and the U.S. – Iran conflict become just another simmering “Middle Eastern armed Conflict” with limited spillover effect on the rest of the world.
II The European Commission today Friday finally after lengthy delays released its proposed update of the European Emissions Trading Scheme (ETS) and presented its plan to boost overall electrification levels in the European economy.
As discussed in earlier notes, the overall thrust of the Commission’s proposals is to maintain the EU’s carbon price as the most important policy tool with which to decarbonize the European economy, while trying to mitigate the most negative effects on European firms’ competitiveness.
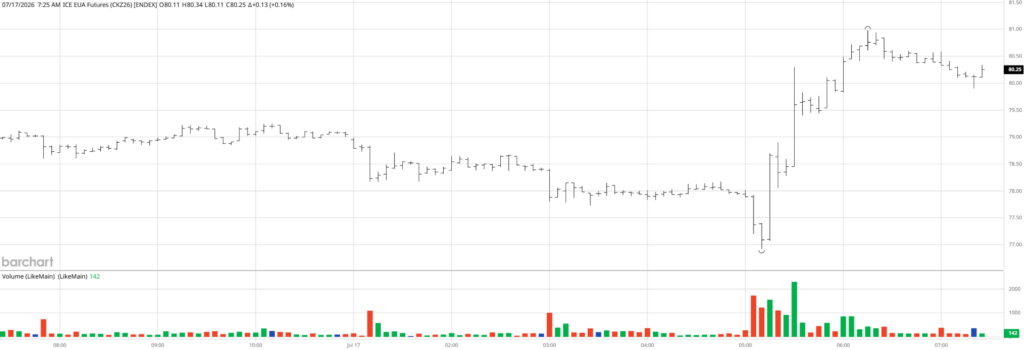
The successful intent of the Commission’s proposal is verified by the initial ETS emission pricing reaction to the proposals, released at 11am CET on July 17th. Benchmark ICE EUA prices rose between one and two percent to just over €80/MW (Figure 1).
Figure 1 ICE EUA Future Price July 17th 2026
Source: ICE
The proposed ETS and broader electricity market reforms are multifaceted and will now go into a prolonged negotiation phase with EU member states and the European Parliament with a final policy outcome – likely not materially different from the Commission’s proposals though – expected in the first half of 2027.
The main focus is on the medium-term, as the speed of annual carbon emission credit reductions (currently 4.3-4.4 precent/year) will be reduced after 2031, and some credits remain available into the 2040s. There is renewed focus on providing investment support for decarbonization in the EU, as new rules tying ETS revenue to emissions reducing investments are proposed, and a new €100bn Industrial Decarbonization Bank (IDB) will be set up.
ETS maritime coverage will be expanded to also smaller ships between 40-5,000 gross tonnage, while ETS aviation coverage is to be expanded from intra-EU flights to all flights departing from an airport situated in the European Economic Area (EEA) and landing in third countries up to 5,000km from the relevant EU airport. Waste incineration emissions in the EU will also be included fully by 2034.
CBAM covered sectors will see their free emissions phase-out proceed, though some additional free credit will be available reflecting sectors’ continued exposure to international competition and the fact that commercially viable decarbonization technologies are not yet available to them. Lastly, the EU have set a target to double the total electrification share of EU energy use to 46 percent by 2040.
Overall, today’s European Commission proposals signal renewed EU commitment to in the long-term relying on aggressive carbon pricing in bringing down EU emissions, even as it is likely to cause trade frictions with other economies (not least the United States), and subject the EU’s energy intensive industries to continued strong policy disadvantages with other production locations. It now passes to member states and the European Parliament to decide whether this political choice is viable in the EU today.
Jacob

