

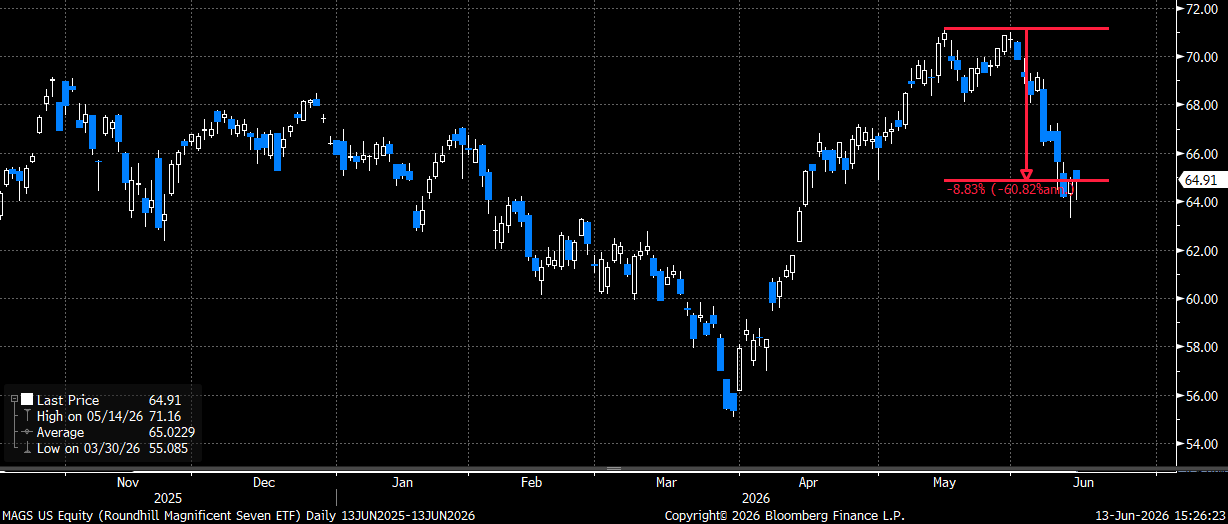
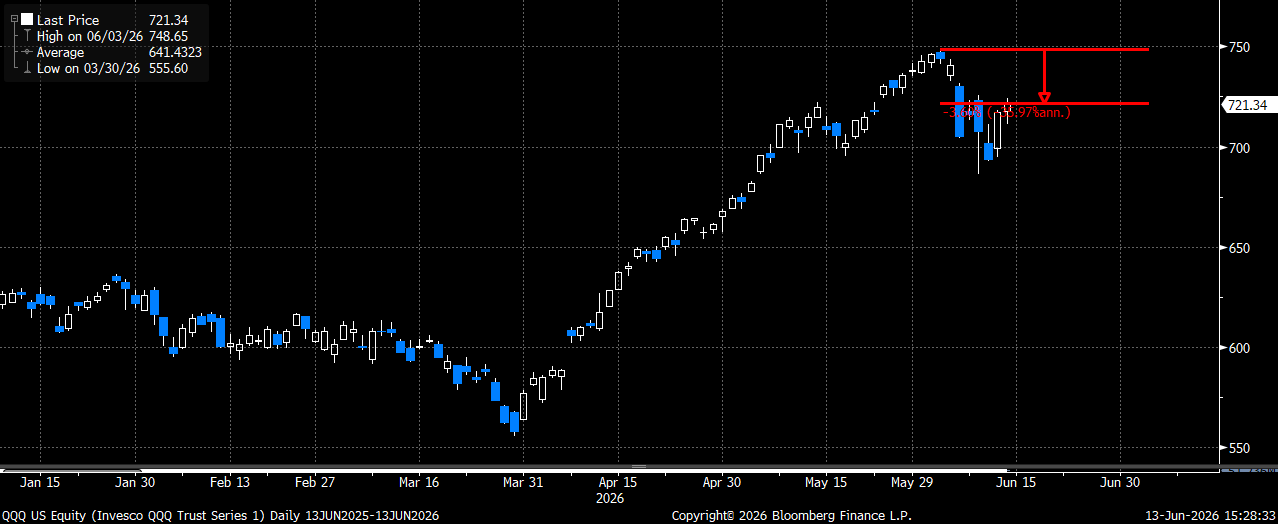
While most of the tech/AI trade continues to have a lot of positive momentum, the “Mag7” names (AAPL, AMZN, GOOGL, META, MSFT, NVDA and TSLA) have all been laggards of late. The tech-heavy QQQ is only down ~ 3.6% from its recent highs, while the Mag7 ETF (MAGS) is down ~ 9%. Each of the Mag7 names is down at least 8% from their recent highs, with AMZN, MSFT and META are down 14%, 16% and 18% respectively. The fact that the Nasdaq (QQQ) is only down 3% from the highs, with the Mag7 having a nearly 40% weighting, likely speaks to just how strong the AI memory and semiconductor trade has been.
The Mag7 ETF (MAGS) is down ~ 9% from the May highs
The tech-heavy QQQ is only down ~ 3.6% from the highs
We saw a very similar setup to start the year, where the Mag7 names, specifically the hyperscalers, all were under pressure, and that helped fuel the broadening-out trade. The broadening-out trade came under pressure after the attack on Iran as both oil prices and yields spiked higher. Perhaps now that it appears there could be a resolution in the Middle East, and the fact that the hyperscalers remain under pressure because of their massive capex, we could see the broadening-out trade reignite once again?
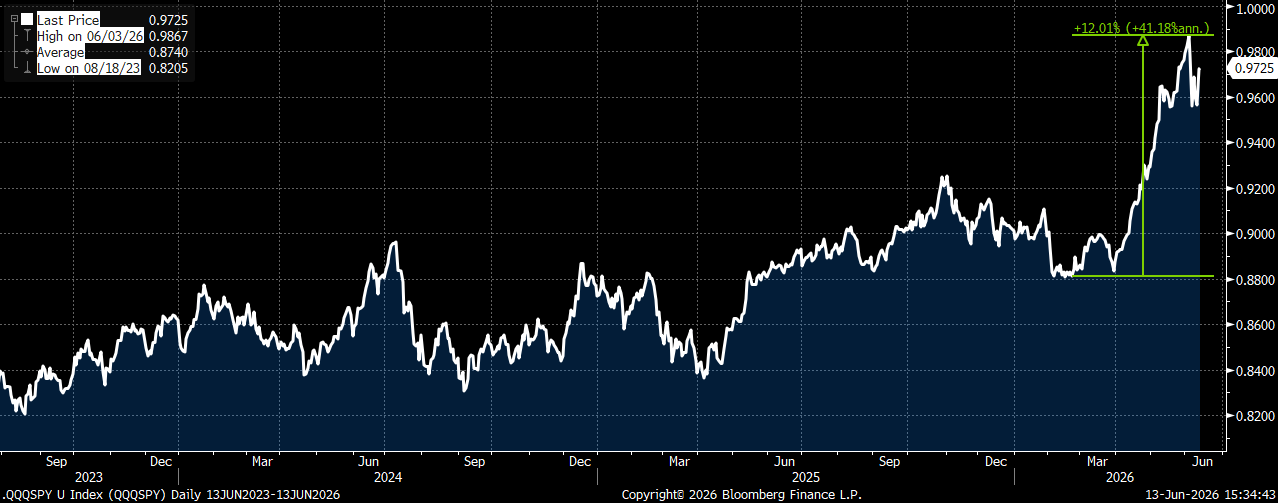
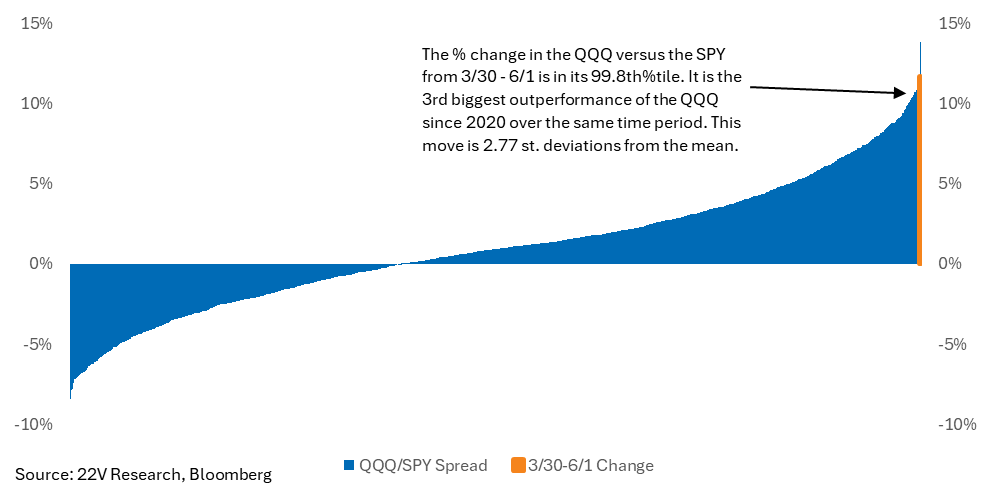
On the volatility front, what currently stands out most to me is how “expensive” upside QQQ calls trade relative to both the S&P (SPY) as well as the small cap (IWM) upside calls. If we look at where 3-month (Aug) 40-delta QQQ call vol trades versus where similar duration/delta SPY calls trade, we can see the call skew now trades at 7-year highs. QQQ calls trade at a 60%+ premium to SPY, and that is after we just saw QQQ outperform SPY by nearly 12% off the March lows. I had the 22V quant team look at that outperformance to put it into perspective and they said it was the 3rd largest outperformance since 2020, was a 3 standard deviation move and ranks in the 98th percentile since 2020. So even after we just witnessed one of the largest outperformances this decade, the options market is betting on a continued upside beta move.
QQQ 3-month (Aug) 40-delta calls are trading at their richest skew to same duration/delta SPY calls over the last 7 years

This “rich” call skew comes AFTER QQQ just outperformed SPY by 12% from the Feb lows to the June highs
The 22V quant team highlighted the recent outperformance by QQQ to SPY
In other words, QQQ would have to continue to outperform the market (SPY) by over 60% over the next 2-3 months to justify the lofty spread in upside call vols between the two main indexes. Keep in mind too that QQQ has a 1.2x beta to SPY over the past 2 years with a correlation of over 90% (thanks to SPY now having a very heavy weighting in many of the same tech names that QQQ owns), yet options are pricing in an upside beta of closer to 1.6x. Finally, should the Mag7/hyperscalers continue to trade poorly (ORCL just declined by 8.5% this past week when they announced a plan to raise an additional $40 billion to fund their AI buildout plans), it likely makes it that much harder for QQQ to continue to massively outperform to the upside (especially at the current 60% rate that the call skew implies). For example, since the Mag7 peaked on 5/14, QQQ is essentially flat, and SPY is down nearly 1%.
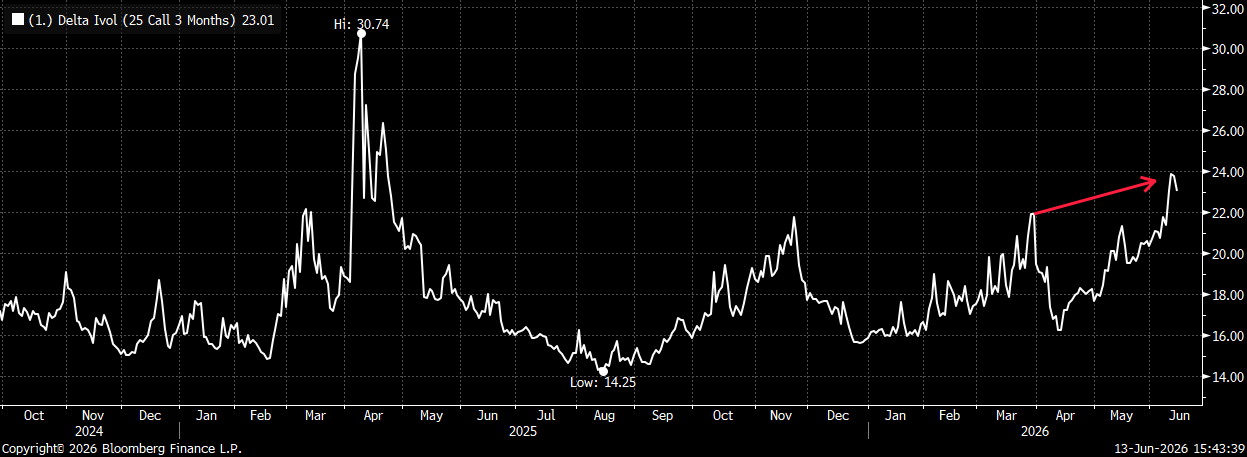
Looking just at QQQ 3-month 25-delta call implied volatility, we see that it has been steadily climbing WITH the market going higher. Since early April, vol has moved up nearly 50% from ~ 16 to just below 24 (its highest level since the 2025 April tariff decline). I believe this speaks to the momentum call buying we continue to see in both the AI names (specifically the semis and memory ones) as well as tech in general. We typically only see volatility rise like this on sharp declines, and not when the index is at/near the highs. To put this into perspective, 3-month upside call vol is now HIGHER than where it traded at the March lows (when QQQ was nearly 30% lower).
QQQ 3-month 25-delta call implied vol is up 50% from the April lows and now HIGHER than it was at the market bottom in March
Given this setup of QQQ upside call vol trading “rich” to both itself, as well as the other two major ETF’s (SPY and IWM), I think there are several ways to play this. First, if long/overweight the tech trade it does makes sense to look at selling upside QQQ calls against a portion of the long exposure. This is especially true If the Mag7/hyperscalers that comprise ~ 40% of QQQ continue to trade poorly like they have been since mid-May. It seems far less likely that the index can continue the upside rate of change we saw off the March lows (when that group was rallying) if they continue to act as a drag on performance (like they have been the past month).
Trade I would consider:
Sell QQQ August 780 calls @ ~ 10.40 (QQQ 721.34 Fri close ref)
Trade Details:
- Selling the August 25-delta QQQ calls against a portfolio that is long/overweight the tech trade
- QQQ 25d call vol is up 50% from the April lows and continues to screen “rich” to both itself as well as the other two main indexes (SPX and RTY)
- Call sale yields 1.4% (7.3% annualized) with an upside breakeven of 790.40 by August 21st expiry (nearly 10% higher)
The other option is to sell upside QQQ calls and “replace” that long notional exposure with either the “cheaper” SPY or IWM calls on a similar delta. If looking at SPY, you can own roughly 50% more upside notional exposure in the market for NO added cost. Again, QQQ has had a beta of ~ 1.2x to SPY over the past 2 years, so owning 60% more upside exposure in the market for no added cost looks rather attractive here in my opinion.
The trade would look something like this:
Sell QQQ Aug 21st 755 calls 1x (37d, 24.35 vol)
Buy SPY Aug 21st 763 calls 1.5x (37d, 14.75 vol)
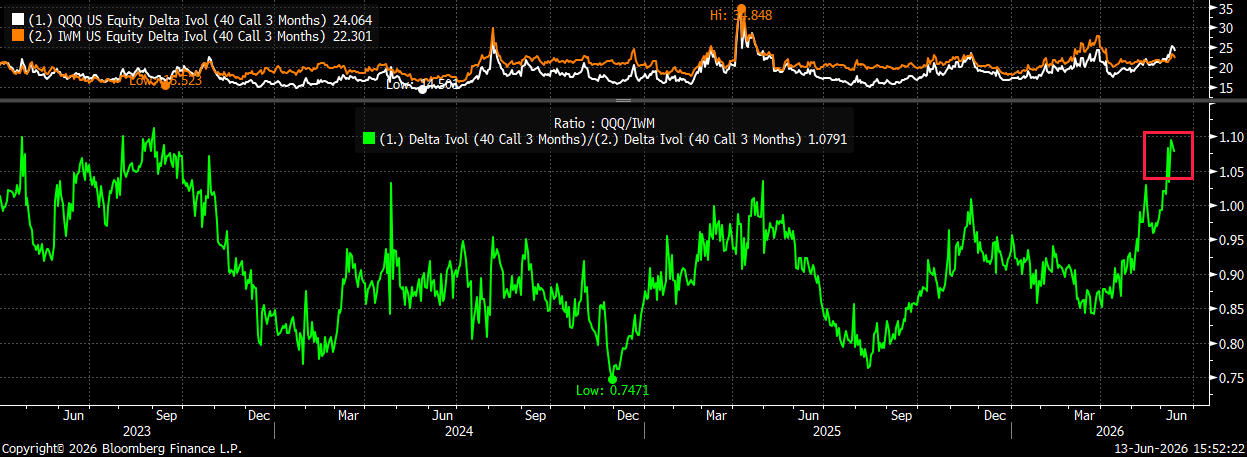
This costless trade captures the attractive call skew, while providing more than 50% additional long notional exposure (all in SPY). The other trade, which I also really like would be to sell QQQ 3-month (Aug) calls and buy same duration/delta IWM calls. Just like the QQQ/SPY call skew, I am seeing QQQ calls also trading at their richest skew to IWM calls in about three years.
QQQ/IWM 3-month 40-delta call skew at three-year highs
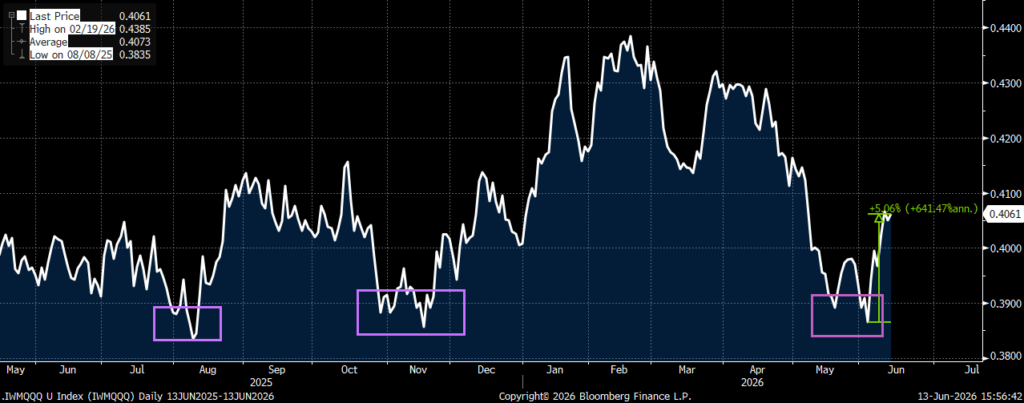
Perhaps making this QQQ/IWM trade even more attractive now is the fact that IWM is already outperforming QQQ of late. Since early June, IWM has outperformed QQQ by ~ 5% and that was after the relative spread hit levels where it previously bounced off of back in August and November. This trade also supports the broadening-out thesis I mentioned earlier. If we see the Mag7/hyperscalers remain under pressure, and we see a bid to the more cyclical areas of the market like banks, housing and retail I believe this spread can continue to work higher (it is still well below the highs reached in Feb). So with QQQ calls now trading at a 10% premium to IWM calls here (they traded at a 10% discount in Jan/Feb), the risk/reward of the trade is even more compelling and a great way to capture attractive call skew while diversifying an existing long tech-heavy portfolio into the more cyclical areas of the market.
IWM/QQQ relative spread has already been moving higher after hitting “support” levels from both August and November
The trade would look like this:
Sell QQQ Aug 755 calls 1x (37d, 24.35 vol)
Buy IWM Aug 305 calls 2.6x (37d, 22.4 vol)
This costless trade captures the attractive call skew, while positioning for additional IWM upside versus QQQ (perhaps as oil and yields move lower on more positive news from the Middle East). Thanks to favorable skew, the overall structure is net long an “extra” 10% of notional exposure (all in IWM).
Please reach out to me to discuss any of these ideas and for updated pricing.

