

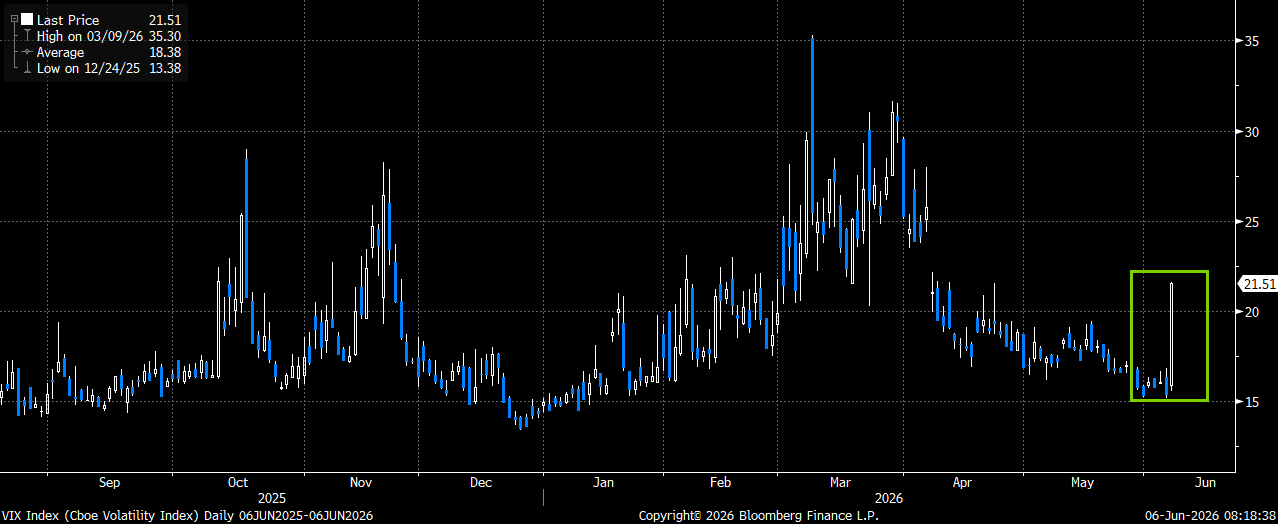
While all of New York, and most of the sports world will be focused on the Knicks this week, I also will be intently watching the action in the VIX. The nearly 40% jump in the VIX on Friday was the largest single-day gain since the tariff meltdown in April of 2025. I have been arguing for some time now that VIX call spreads should be owned as a macro portfolio tail hedge, and the action on Friday only reinforced that belief.
VIX with a nearly 40% spike on Friday after months of moving lower
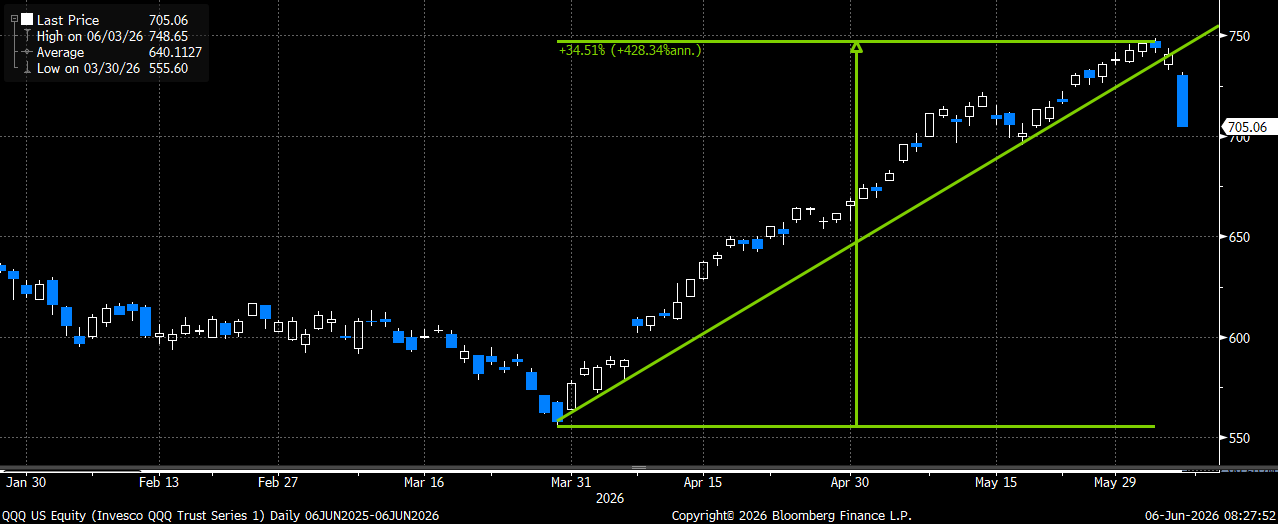
So what was behind this move in the VIX on Friday? Well, clearly the 4.8% decline in the Nasdaq (QQQ) was at the root of the spike in volatility. Tech has been the driving force for much of the gains in the indices off the March lows, and now that those names are under pressure, for really the first time since late March, volatility moved up accordingly. Disappointing reactions on earnings from some of the larger tech names (AVGO, CIEN, CRWD) started the move lower late in the week, and given how much momentum had been in these names, it appears there was somewhat of a rush to the exits all at the same time on Friday. The stronger payroll data also put pressure on bonds, and with each stronger data point the odds of a rate cut before the end of the year continue to dwindle. Even with a clear rotation back to many of the laggard sectors like healthcare, financials, consumer staples and utilities, the indexes have become so top-heavy in the tech trade that the strength in those sectors did little to offset the weakness.
QQQ with a nearly 5% drop on Friday. This comes on the heels of a 35% rally in just two-months for the tech-heavy index
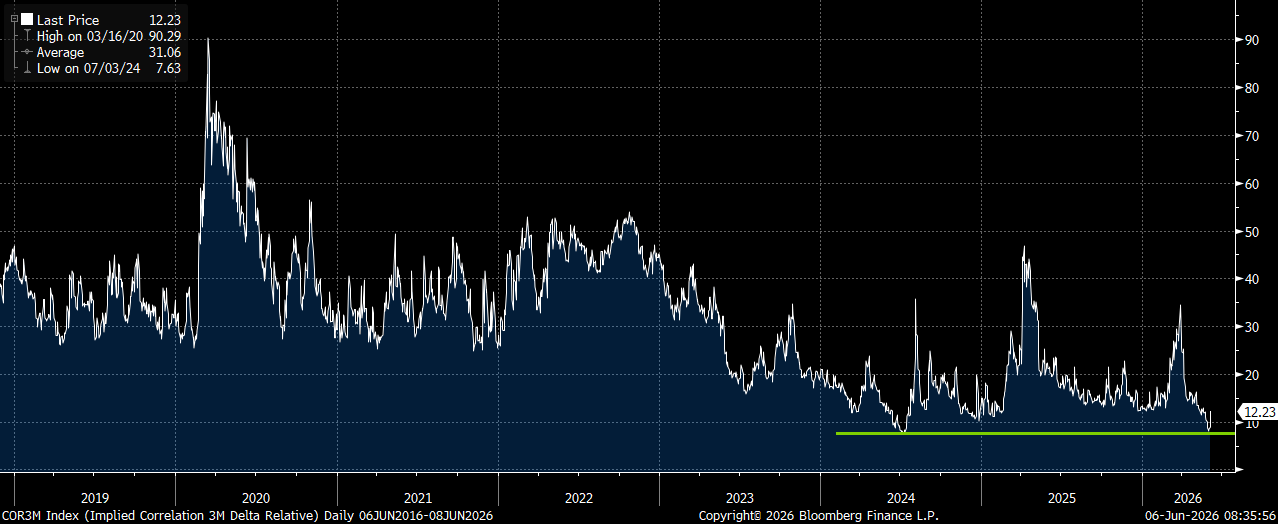
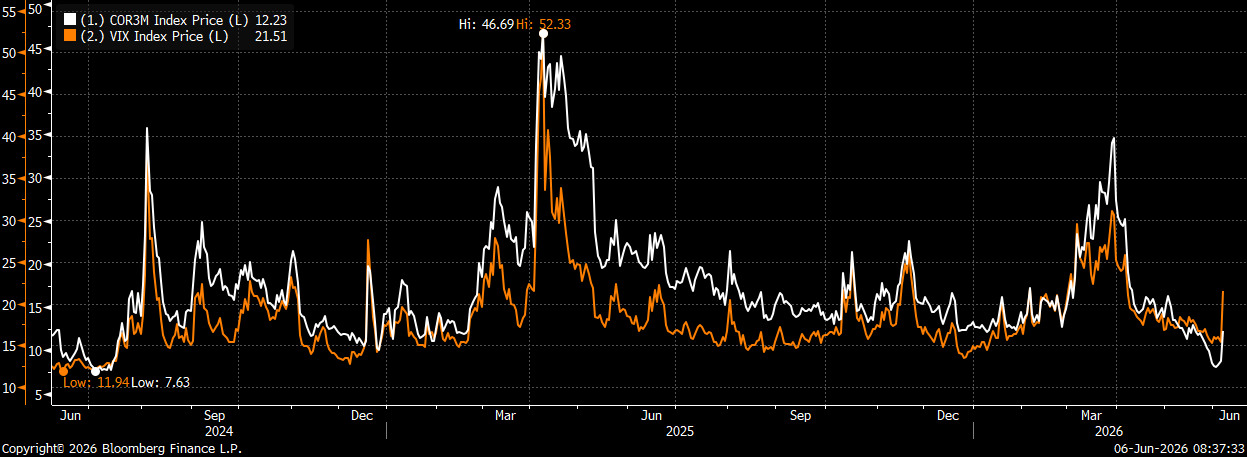
I believe the other thing that contributed significantly to the move higher in VIX on Friday was the fact that implied correlations in S&P names had moved back to the all-time lows. This low level of correlations amongst the largest names was a function of seeing massive moves on single-names, while the overall index had seen relatively muted moves (mostly higher). Perhaps after a prolonged period of this trade working, selling index vol to own single-name vol, it had gotten a bit too crowded? If a lot of market participants are short index vol, then it makes sense that we saw a fair amount of covering on the move Friday. Even though we saw a decent move higher on Friday in the 3-month correlation index, it still remains barely above the historical lows. Should we continue to see a bid for index vol (potentially on further weakness), then my guess is both VIX and correlations will move higher together given their historical relationship,
3-month implied correlations had moved back to the all-time lows. We saw a sharp move higher in both correlations and VIX last time off this level in the summer of 2024
VIX and implied correlations tend to track one another very closely
Perhaps the upcoming SpaceX IPO this week was behind some of the selling? Funds need to raise cash to buy the shares of the new company ahead of the IPO on Friday. In addition, large announced equity sales by both Google and Meta for Capex spending are also adding a fair amount of equity supply to the market, not to mention the Anthropic and OpenAI offerings that will be coming later this year as well. Putting all these facts together, on top of the massive rally we saw (specifically in the tech/AI trade), likely explains some of the weakness we saw late in the week and the corresponding spike in volatility off of very low levels.
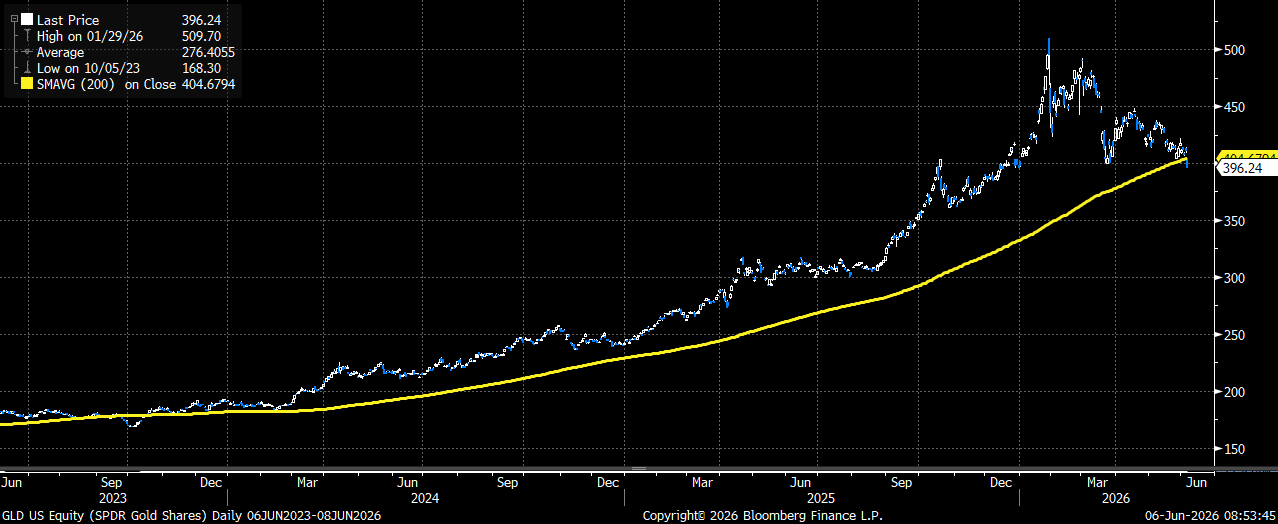
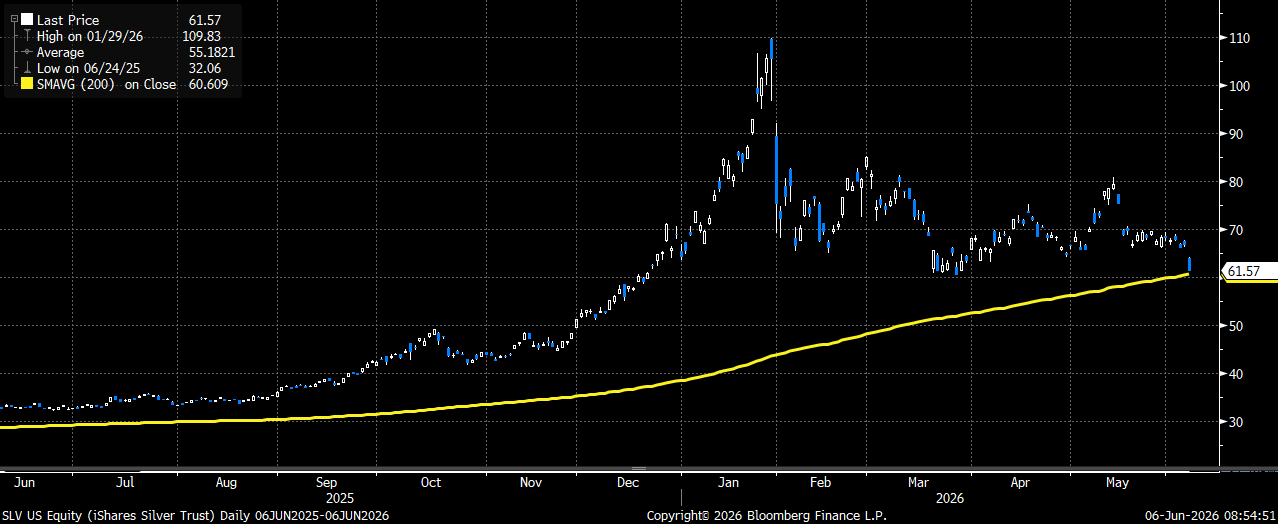
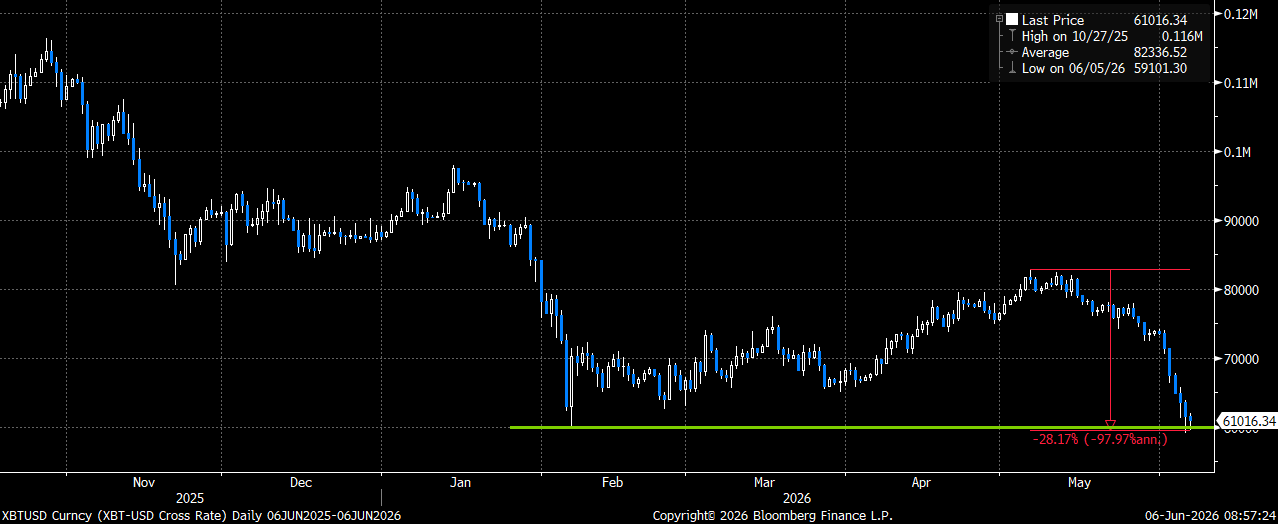
The other thing I was watching on Friday was the very poor action in both gold and silver. The main gold ETF (GLD), closed below its 200-day moving average for the first time since Oct 2023, and silver (SLV) was down over 8%, and is hovering just above its 200-day moving average and the March lows. I believe this is concerning for all risk assets as it likely speaks to deleveraging by some of the largest holders. Yes, the US$ has been rallying of late as yields in the US have been generally moving higher, but the weakness in both gold and silver appears to be much larger than the relative move in the US$. If investors are reducing risk in gold and silver, it stands to reason they may need to continue to sell their biggest winners (specifically the tech/momentum names) if the deleveraging continues. Should that happen, then it’s not hard to see a scenario where indexes move lower (given their very heavy exposure to tech), with VIX continuing to move higher. Let’s not also forget about bitcoin, which has declined by 28% over the past month and is back to the Feb lows too.
Gold (GLD) closed below its 200-day for the first time in nearly THREE years on Friday
Silver (SLV) was down 8% on Friday and is in danger of breaking below it’s 200-day and March lows as well
Bitcoin has dropped by 28% over the past month and is at the Feb lows once again
Given this backdrop, I continue to favor owning VIX call spreads out to July to be long volatility as a macro portfolio tail hedge. I would also now consider adding tactical hedges in either QQQ or SPY, depending on how much tech exposure is in your portfolio. If tech remains under pressure (after the massive gains we have seen since March) then both QQQ and SPY are at risk of further declines given their heavy tech exposure. Yes, implied volatility has moved up a bit after the market decline last week, but protective put spreads now likely make more sense with the upside momentum having been broken for the time being.
Please reach out to me to discuss specific VIX and index hedges out to July as we start the new trading week.

