Back Shoot Around

22V Afternoon Shoot Around: Productivity Gains, QCEW, and Liquid Cooling

Published on June 3, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: Productivity Gains

Recent productivity gains could have nothing to do with AI. While the costs of AI are increasing rapidly and organizations are still struggling to convert AI into ENOUGH value to offset increased token costs. This is something we are being asked about. The best way we can think of tracking this concern, for now, is margin sentiment relative to cost sentiment. I.e. what companies are actually saying about costs and margins, and how that relates to margin changes going forward. For now, the bias is still increasing margins. All things equal, that should support AI capex beneficiaries and the Price Momentum factor.

Relevant News: AI Demand Outstripping Supply

Q Earnings season made it clear that AI demand is outstripping supply. At the same time, S&P 1500 margins increased by 1pp relative to expectations. If margins are increasing, particularly for companies using AI the most, that SUGGESTS company level AI productivity gains can continue and AI demand will continue accelerating. As we have highlighted a few times, rapid margin expansion has been a primary driver of the unusually strong corporate earnings performance in 2026.

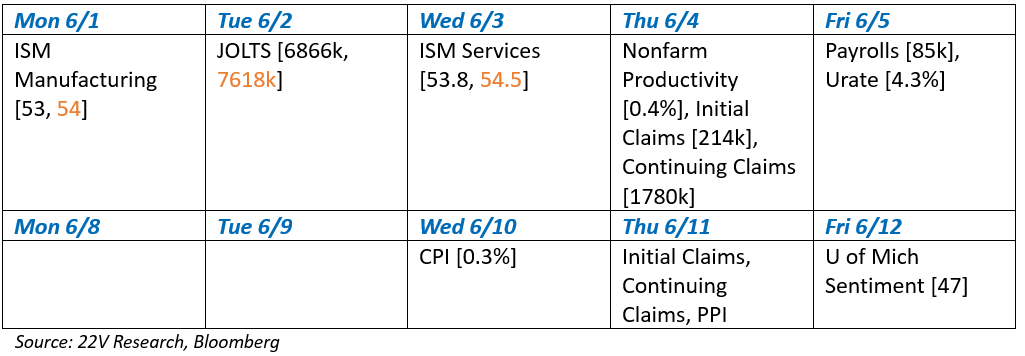
Things to Watch [Consensus, Results]:
A screenshot of a computer

AI-generated content may be incorrect.

Strategy:

Thinking About Downside Risk to AI Demand Beneficiaries – (HERE)

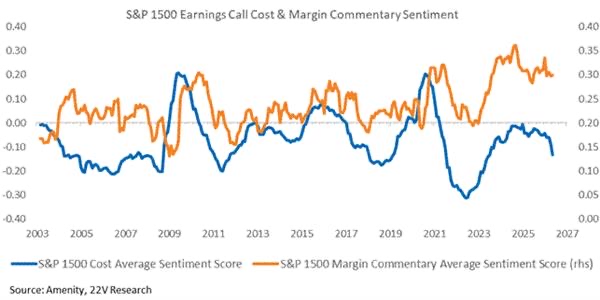
One way of tracking margin relative to costs sentiment discussion is focusing on what companies are saying about costs and margins. Recently, S&P 1500 cost sentiment has deteriorated (higher costs) for S&P 1500 companies, but S&P 1500 margin sentiment remains at unusually high levels. It is probably fair to assume that investors will accept some increase in costs if margin sentiment remains at unusually high levels. The current level of margin sentiment suggests an INCREASE in margins in 2Q26. Unless margin sentiment declines or actual margins decline, it will be difficult to be short Price Momentum.
A graph showing the value of a stock market

AI-generated content may be incorrect.

Economics

‘25Q4 QCEW: Done with NFP Overcounts – (HERE)

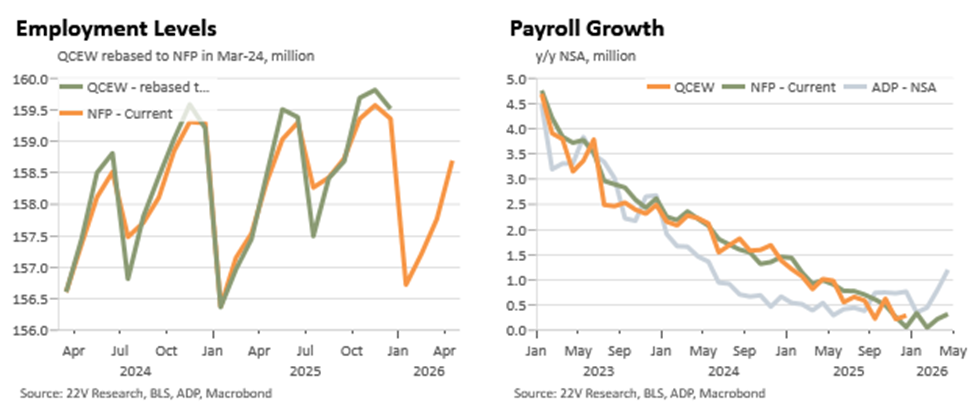
The quarterly census of employment and wages, the comprehensive payroll tax-based source data that ultimately underpins the benchmark revisions to the NFP data and other measures of income and earnings, contained a key positive surprise today. The monthly NFP data seems to no longer be showing any appreciable overcounts after 3+ years and may well see a small upward revision in time with ¾ of the preliminary data in hand now. Given historical patterns of procyclical labor market revisions, this swing towards no more initial overcount is an important data point showing underlying stabilization reassures one lingering doubt about the labor market.
A graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of a graph of

AI-generated content may be incorrect.

Data Infrastructure/ Commodities:

ECL: CoolIT Demonstrates 15kW Coldplate – (HERE)

CoolIT’s validation of a 15kW cold plate marks a significant advance for single-phase direct-to-chip liquid cooling, extending the technology roadmap well beyond what many viewed as practical limits and reinforcing its viability for next-generation AI accelerators. Given that current AI rack architectures such as GB300 NVL72 appear to operate at roughly ~1kW per primary cold plate, the demonstrated 15kW capability provides substantial thermal headroom and supports the case for a longer runway for single-phase cooling adoption. We continue to view ECL favorably as a beneficiary of accelerating liquid-cooling deployments and AI infrastructure buildouts, with the pending CoolIT acquisition representing a potential catalyst that further strengthens its exposure to these trends.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.