Back China Strategy

China: April PMI Suggests Weaker Growth Ahead

Published on April 30, 2026

∙ Download the PDF Report

By

Michael Hirson

Houze Song

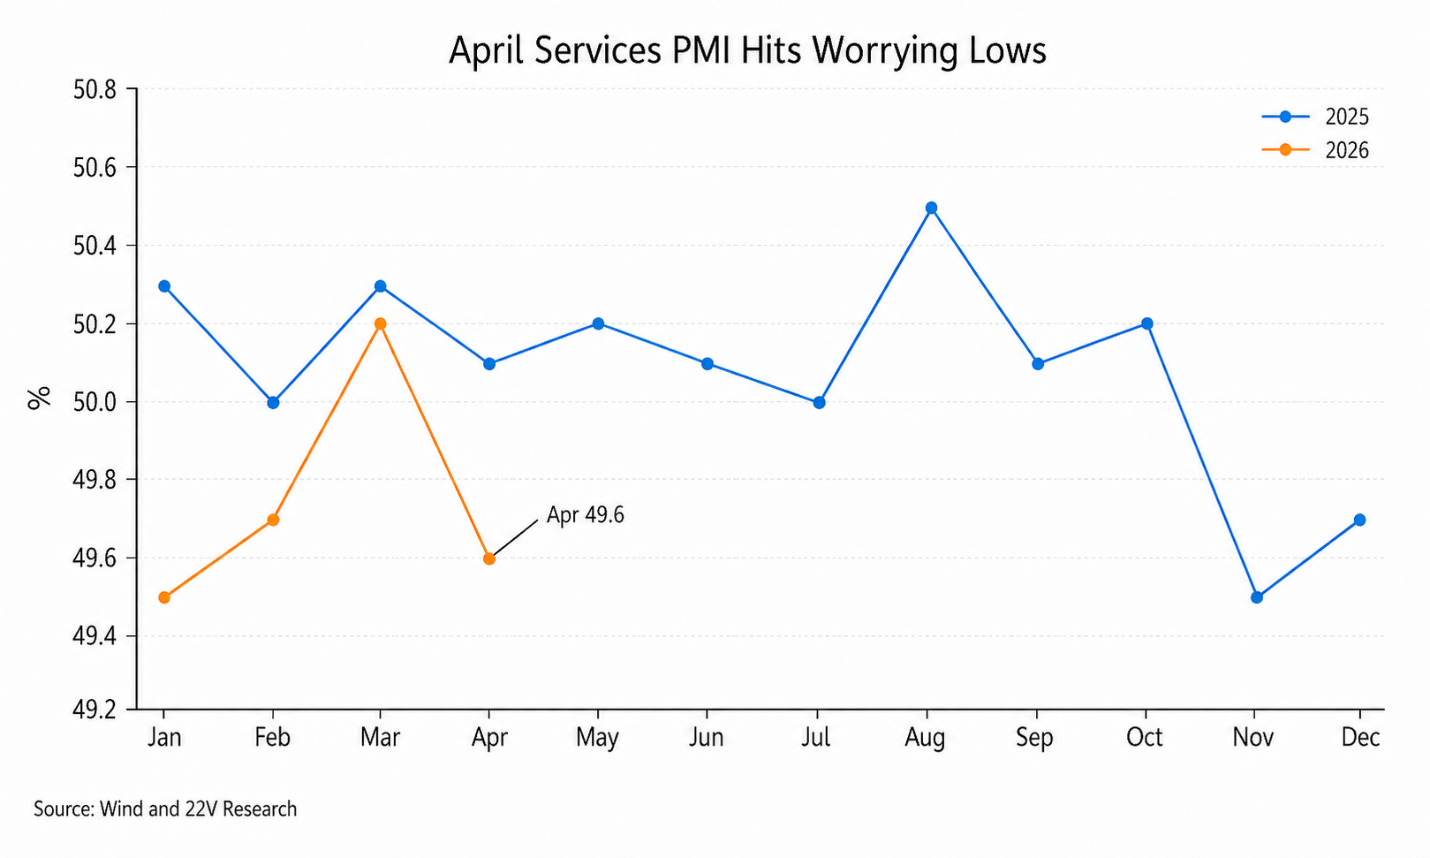
China’s official Manufacturing PMI came in at 50.3 (down slightly from 50.4 in March), only marginally in expansionary territory, while the services and construction PMIs fell to 49.6 (from 50.2) and 48.0 (from 49.3), respectively. The PMI data essentially confirm that fiscal policy is no longer providing meaningful stimulus, as reflected in the weak construction PMI. They also suggest that services firms are struggling to pass through higher input costs, while the oil shock is a slight net positive for manufacturing (for now). Taken together, the April PMIs point to weaker growth ahead.

The headline manufacturing PMI at 50.3 should be taken with a grain of salt. Exports remain resilient for now, with Chinese industry less directly exposed to oil and natural gas price hikes than many other economies, and with some industries (such as electric vehicles) benefiting from the crisis. However, that resilience may not be durable. Both PMI export orders and the export-heavy RatingDog PMI are above 50. But as oil prices are poised to stay high through Q3, the risk of slower global growth and trade is building until traffic through the Strait of Hormuz normalizes. Moreover, the weak construction PMI offers further evidence that fiscal policy is no longer stimulative, and that construction-related manufacturing demand will stay weak in the coming months. In fact, despite the recent PPI rebound, prices of construction materials such as rebar and cement remain soft.

The weak services PMI is worrying. The April services PMI reading of 49.6 is the weakest since November 2025 (not including distortions around the Lunar New Year), and the services new orders index, at 44.8, is the weakest since 2023. Weak demand has forced services firms to absorb cost increases. While services PMI input prices rose significantly in both March and April, to 52.2 and 51.2, respectively, PMI output prices were flat in March and declined in April, to 47.9.

A particular reason for our concern over services is the link back to employment (the sector is labor-intensive) and thus wages and consumption. The employment sub-indexes for services and for construction remained weak, consistent with our view that consumption activity in China will remain subdued (see our report from last week HERE).
A graph of a line with blue and orange lines

AI-generated content may be incorrect.

Policy Implications:

Despite the overall softness in the April PMIs, we continue to expect Beijing to refrain from providing additional demand-side support for the economy for the time being. As laid out in our take on this week’s quarterly Politburo meeting on the economy (link HERE), we do not expect new stimulus before Q3.

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.