

I Iran arguably just had one of its best days of the war. Following the coalition strike on Iran’s Sars natural gas field + adjacent petrochemical plants, Iran carried out its announced retaliation and among other targets hit Qatar’s Ras Hattan LNG plant and, according to QatarEnergy, disabled 17 percent of the production capacity for possibly several years. European LNG prices rose in response by initially another 30 percent, though fell back later in the day, as the extent of the damage to Ras Hattan was seemingly less than initially feared. Brent oil futures similarly briefly went back above $110 before falling back, while cash Dubai crude (physical barrels) reached $170/barrel.
Iran in other words once again proved its still potent military capacity to escalate the war in retaliation to coalition strikes on Iranian energy infrastructure and fire ballistic missiles towards identified reciprocal high-value infrastructure targets in the Gulf region, prompting the desired reaction from global energy markets. Faced with this revealed Iranian retaliatory capacity, CENTCOM “data points” describing say a 90 percent reduction in Iranian missile launches since the start of the conflict is simply the wrong metric to focus on at this point in the conflict. Iran retains the military capability it needs to impose costs on the Gulf region and at least at this point in time reciprocate coalition escalation. Given that the coalition has had essentially full air superiority over Iran for almost three weeks, it moreover is increasingly likely – unless the bombing targeting and air campaign strategy is changed – that Iran will continue to retain its retaliatory capacity, even in the face of continued coalition bombing in the weeks ahead. The coalition has not to date, despite its evident traditional military superiority, been able to solve the military threat posed by Iran for the Strait of Hormuz, or the broader Gulf region. This narrows the forward strategic options for President Trump.
In addition to Iran’s statement concerning its continuing military capacity to retaliate, today has also given Iran an arguably even more valuable political victory in the form of President Trump’s “mixed messages” concerning what the United States knew about the Israeli strike on the Fars gas field. That the President first denied knowing about it, and then stated that he cautioned Israel against it tells Tehran with little ambiguity that Donald Trump is not willing to contemplate the economic and political fallout from Iran’s revealed continued ability to strike back at global oil and gas markets. And that by extension that its “eye for an eye strategy” of retaliating in kind will likely prove adequate in deterring the coalition from seriously pursuing a strategy of materially escalating the air campaign against also Iranian domestic infrastructure. This is from Iran’s perspective a crucial revelation that will strengthen its political resolve to continue to resist the coalition’s current war strategy.
Lastly, in addition to Iran’s military and political statements in the last 24h, Tehran has been given a potentially material economic gift by the Trump Administration. Russia’s seaborne oil has already been given a waiver from U.S. sanctions, allowing Vladimir Putin to replenish his war chest and sell likely over an hundred million barrels of oil at higher unsanctioned prices, and now Iran itself appears scheduled to receive a similar leniency from Treasury Secretary Bessent for up to 140mn barrels of its seaborne crude oil. Assuming a say $20 difference per barrel between sanctioned and unsanctioned crude oil, this could equal an almost $3bn windfall for Iran courtesy of the country bombing it. Not a bad day in the office for a regime that has allegedly already lost the war.
Moreover, it is worth noting that since cheaper sanctioned Iranian (and before that Russian) seaborne crude oil was likely to eventually be sold at knockdown prices, it is far from obvious that waiving these sanctions against seaborne oil really has “brought a lot new physical barrels” to the market and, as such really helps that much in bringing down the price of oil. What lifting these U.S. sanctions, however, has clearly done is to provide both Moscow and now Tehran with a potentially material financial gain, and given both Russia and noticeably now Iran an even stronger incentive to keep bringing new seaborne crude oil up for sale. Loading crude oil from Kharq Island and sailing it out through the Strait of Hormuz to China just became more profitable for the Iranian regime, which will surely have noticed the increasing willingness of the Trump Administration to facilitate that even its “enemy’s oil” can be sold. Again a signal to Tehran to keep doing what it has been doing.
Strategically the events of the last day therefore, as noted above, narrows the available options for President Trump. He now essentially, as discussed in an earlier note, has three options going forward to try to bring this war to a conclusion:
- Option 1: Escalation through the essentially riskless expansion of air campaign bombing targets to also include Iran’s domestic energy infrastructure, and the much more militarily risky and far less likely use of U.S. (Israel would almost certainly not take part) ground troops to try to take physical control of the Strait of Hormuz and/or Kharq Island. Both options, however, would with certainty see Iran retaliate in a manner likely exceeding what we have seen in the last 24h, and the deployment of U.S. ground troops to Iran’s shores would surely be welcomed by the regime by providing it far better opportunities to kill or capture U.S. personnel. In light of the hesitant reaction by the Trump Administration to Iran’s recent retaliation, this option now remains far less likely to be chosen by President Trump, and the use of U.S. ground troops continue to be an absolute tail risk.
- Option 2: Diplomacy through mediators to secure an agreement about international access through the Strait of Hormuz, likely with the direct participation of a number of third countries to guarantee this freedom of navigation and whose presence could provide Iran with a degree of security from future coalition attacks. This would likely include naval assets from the G-7 members, and other European and Asian (including China) nations. Donald Trump would not achieve “the actual annihilation of Iran’s nuclear program”, or regime change, but could point to the destruction of Iran’s navy, and likely severe degradation of Iran’s military-industrial capacity, lengthening the time the surviving regime would need to reconstitute its missile and drone capabilities.
- Option 3: More of the same air campaign, though rather than a shrinking number of military-industrial targets, an increased focus on the killing of regime enforcers and security personnel to gradually seek to undermine the domestic repressive capacity of the regime, and over time perhaps facilitate a popular uprising. This option would, however, demand that the political and economic pressure from rising commodity prices remains probably roughly at current levels, or this “war path of least resistance” also becomes unpalatable. The last day’s events suggests that market forces are building against a continuation of the war, implying that the period in which this option can be sustained is shortening.
Overall, events in the last day suggest that option 1 has become materially less probable and that the likely duration of the current status quo – option 3 – has become shorter, as the political and economic costs of the war rise. A shift from the current option 3 to the diplomatic solution in option 2 is hence now the base case, and the likely duration of the war has been somewhat reduced.
II Shifting gear quickly to today’s ECB meeting, no policy changes were predictably announced, but the economic effects of the war played the central role in both the ECB’s macroeconomic forecast and President Lagarde’s press conference. Overall, the ECB baseline forecast (with an input data cut-off date of March 11) assumes a drop in growth from 1.2 percent to 0.9 percent, a material increase in HICP to 2.6 percent in 2026, while core inflation is relatively unchanged. Both GDP growth and HICP show little difference between the December 2025 and March 2026 forecasts for 2027 and 2028 (figure 1).
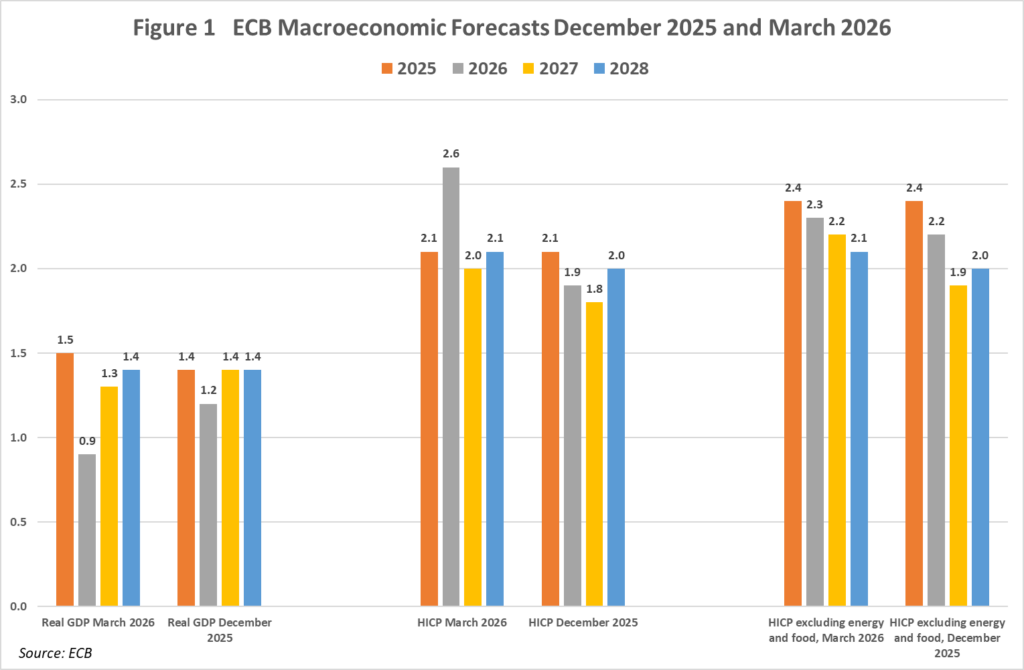
Overall, the ECB forecast – which is complemented by scenarios with a longer lasting conflict and associated larger swings in commodity prices – implies based on March 11 data (including the then market pricing of short-term interest rates revised up by 0.3 percentage points for 2026, by 0.5 percentage points for 2027 and by 0.3 percentage points for 2028) that essentially all of the macroeconomic effects of the conflict plays out in 2026, and that there are no or only very limited secondary effects. The next ECB meeting is on April 30th, six weeks from now at a time in which the war in Iran looks almost certain to be over. The Governing Council can hence at that time carry out a new assessment of the likely effects of the war and commodity prices on the euro area economy.
Overall, the March forecast that includes about one 25bp interest rate hike and the uncertainty about the war between now and April 30th suggests that a hike on that day is a possibility, but that this would if so likely be mostly a precautionary, or signaling hike from the ECB, rather than the start of any new tightening cycle. The war may though change this in the coming weeks, so it remains too early to try to attach probabilities for the April 30th ECB meeting.
Jacob

