Back Derivatives Strategy

Buy Cheap Calls in Areas of the Market that Should Continue to Do Well as Money Rotates Away From Mag7 Names and Dollar Weakens

Published on January 4, 2026

∙ Download the PDF Report

By

Jeff Jacobson

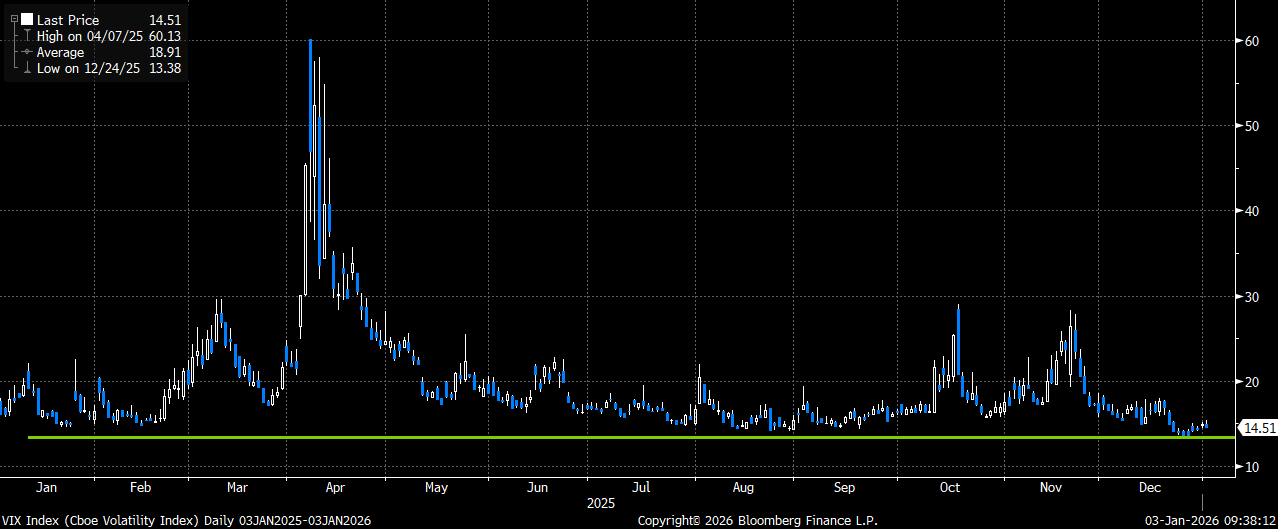
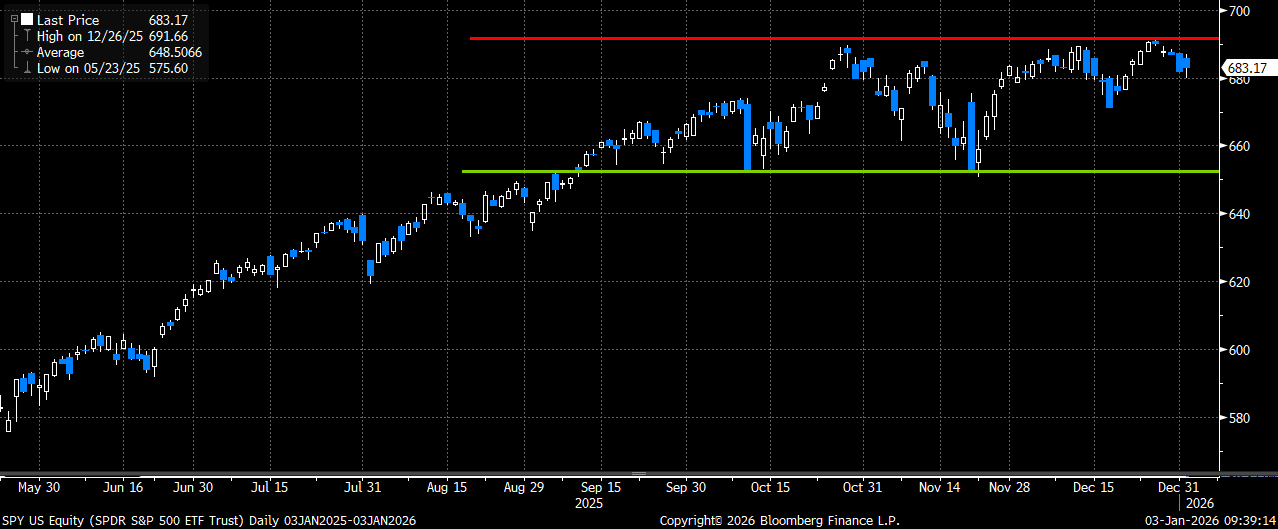
As we start the new year, volatility (VIX) continues to hover just above the one-year lows. When volatility is this cheap it remains an asset class you want to own to express viewpoints, whether as a cheap hedge, or as a limited-risk bullish bet. The news over the weekend on Venezuela should be a reminder that the unexpected can and will continue to happen, and why owning “cheap” vol continues to make sense. With that being said, the S&P (SPY) has effectively traded in a rather narrow range between 650 and 690 for the better part of four months. Therefore, I prefer to own vol in other areas of the equity market that have also seen their implied vols move lower as VIX has dropped that have had more realized volatility.

VIX continues to trade just above the one-year lows
A graph with lines and numbers on it

AI-generated content may be incorrect.

S&P (SPY) has traded in a tight range between 650 and 690 since September
A graph on a black background

AI-generated content may be incorrect.

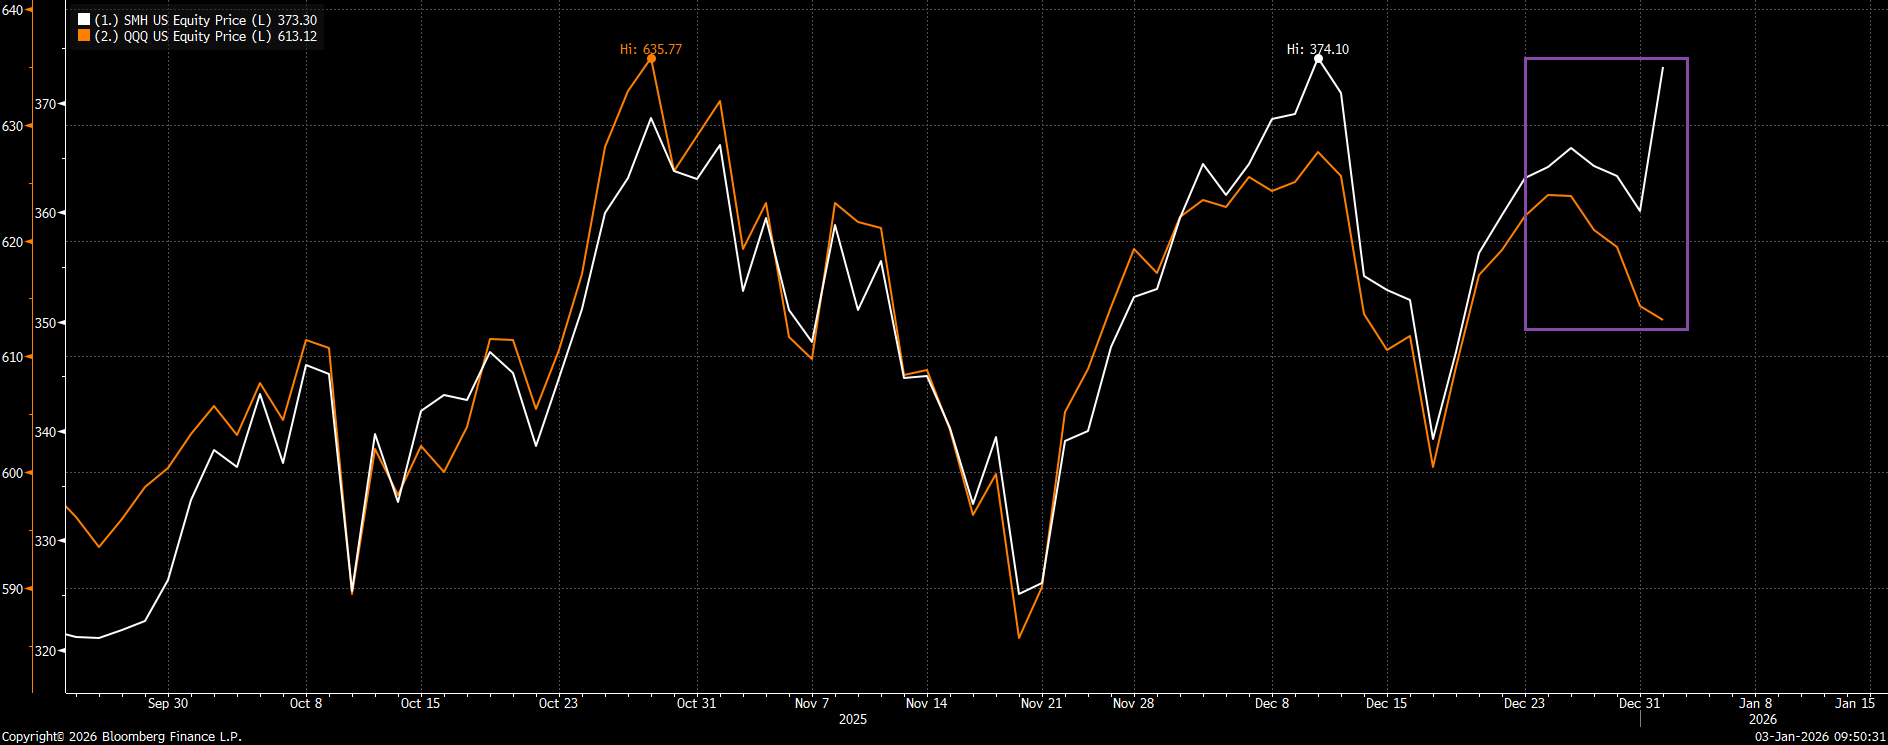
We have been talking about the equity market broadening out trade at 22V for a few months now, and I thought the action on Friday (first day of the trading year) typified this. While the tech-heavy Nasdaq (QQQ) was down 19bps, we saw nice gains in small-caps (+106 bps), energy (+2% in XLE and XOP) and regional banks (+ 66 bps). In fact, I don’t think I can ever recall a day where the semis (SMH) gained nearly FOUR percent AND the Nasdaq was down on the day. This clearly speaks to money continuing to rotate out of most of the Mag7 names, yet being re-deployed to other areas of the market. Should this rotation continue, you want to own cheap calls in areas of the market that should benefit from both a strengthening economy as well as money being allocated away from this “crowded” mega-cap names into new sectors.

Massive divergence between SMH and QQQ speaks to the relative weakness in the Mag7 names
A graph of a stock market

AI-generated content may be incorrect.

With that setup, here are a few upside trades I like to play the broadening out theme further as we start 2026 using cheap upside calls.

Trade #1 – Feb KRE upside calls


Buy KRE Feb 20th 67 calls for ~ $1.60 (KRE 65.24 Fri close ref)

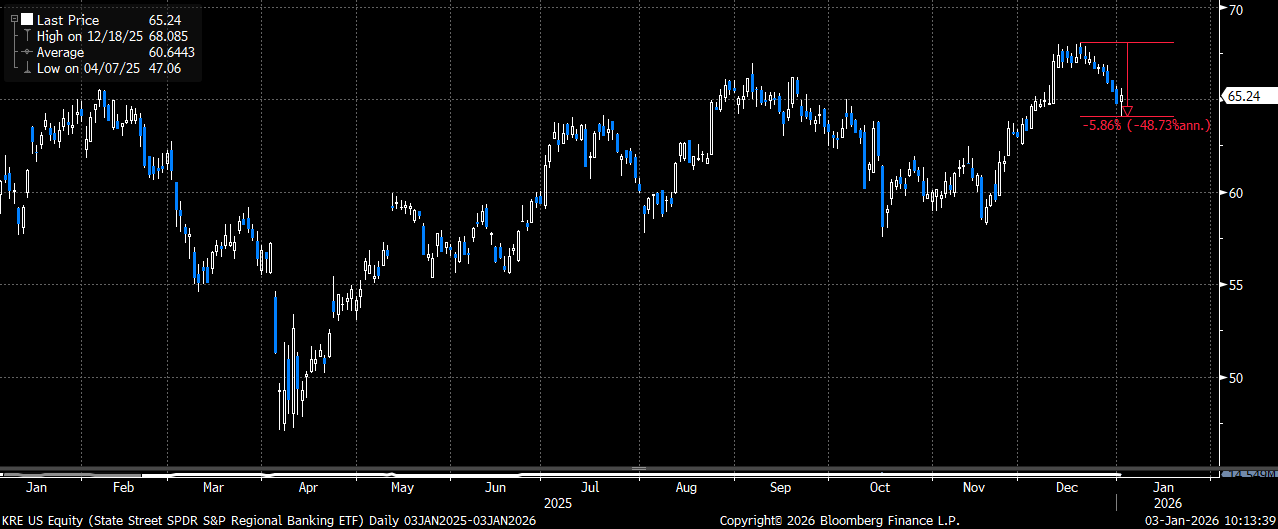
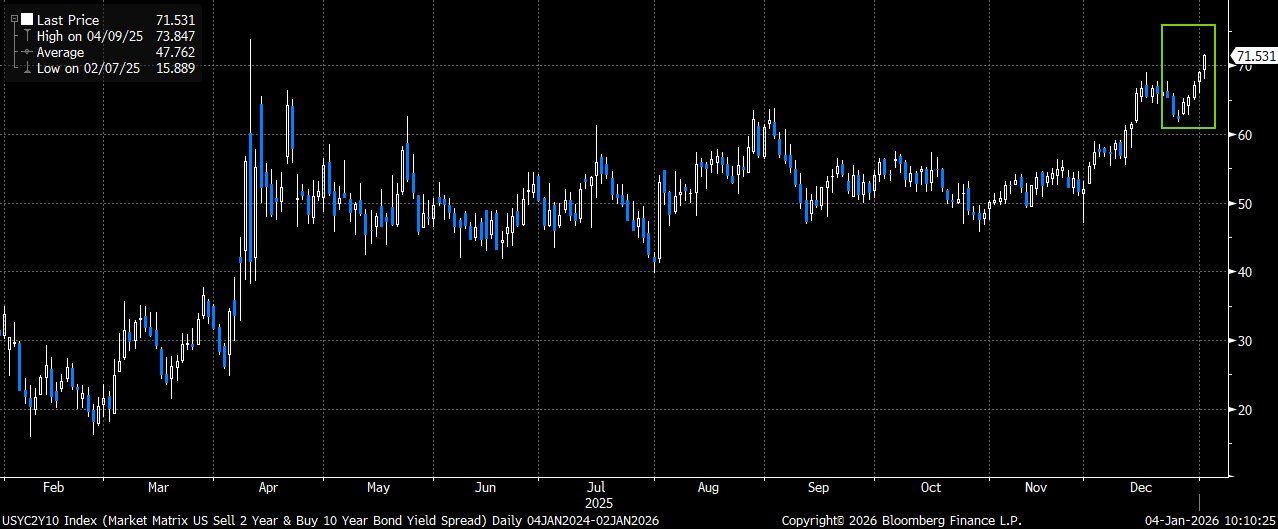
After breaking out to new highs in early December, we saw a bit of a pullback in the main regional bank etf (KRE). I believe this 5%+ pullback has created an attractive entry-point to add the upside Feb calls. In addition, with the Fed cutting short-term rates AND yields on the longer-end continuing to move higher, the 2/10 spread just hit a new relative high. This dynamic should help drive NIM for the group which should continue to give a bid to the sector. What I like about owning Feb calls too is not only does that allow time for trade to work (seven weeks until the calls expire), but that will also capture earnings season for both the regionals as well as the larger money center names. Should we hear positive news on the net interest margin front, as well as on a “strong” consumer, I believe the regionals should continue to perform well and are likely to eclipse the highs from December.

KRE had a nearly 6% pullback after hitting fresh highs in early December. This looks like an attractive entry-point to play for new highs thru earnings season.
A graph on a screen

AI-generated content may be incorrect.

The 2-year/10-year spread continues to make new relative highs as the curve steepens. This should help sentiment/margins for the regionals
A graph on a black background

AI-generated content may be incorrect.

Trade #2 – Emerging Markets (EEM) Feb upside calls

Buy EEM Feb 20th 57 calls for $1.00

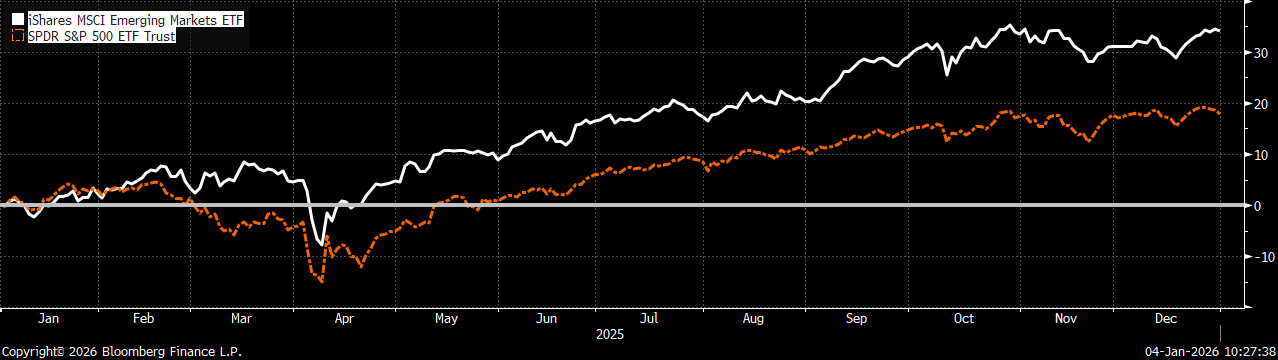
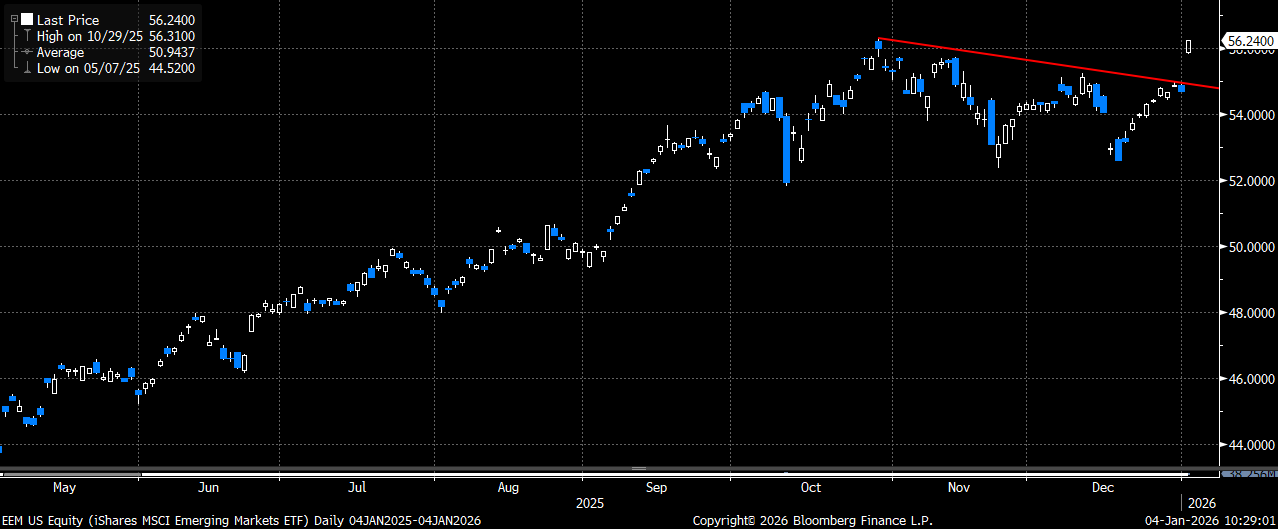
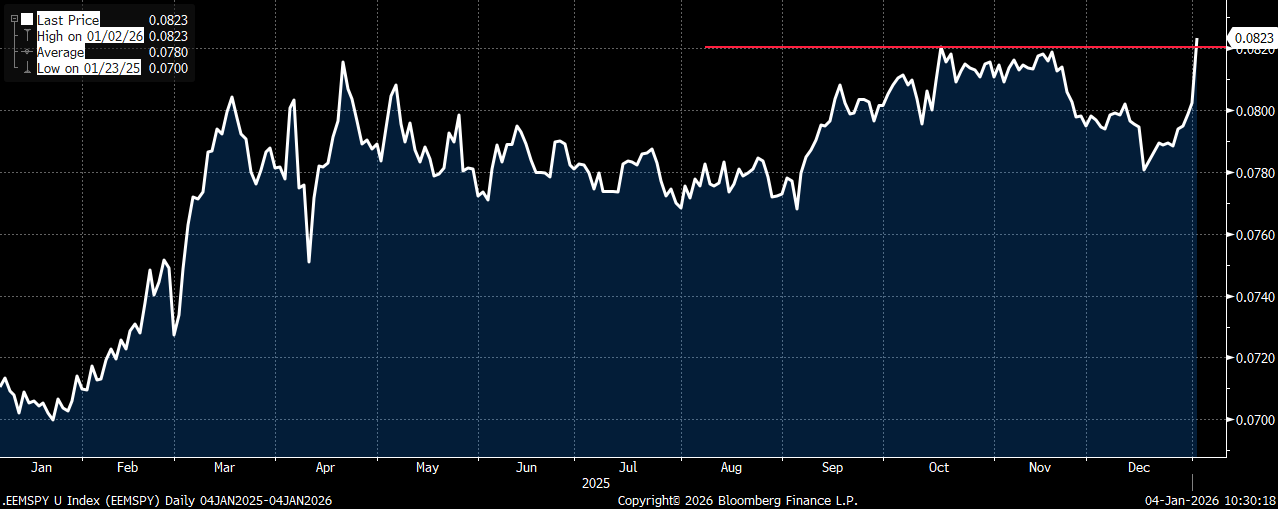
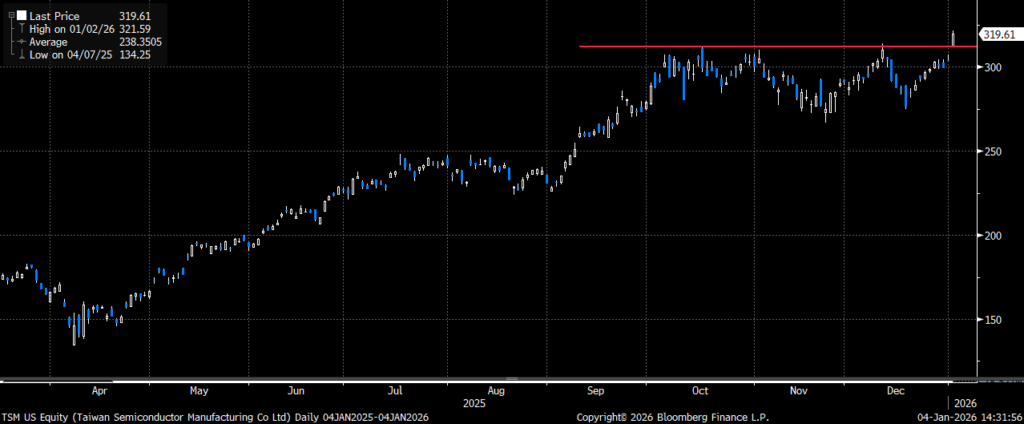
The weaker US$ continues to support owning other (cheaper) markets. In fact, as the US$ index (DXY) declined from ~ 108 to 98 last year, we saw EEM nearly DOUBLE the performance of the S&P (+34% to +17.7%). I continue to expect the US$ to remain under pressure, and the emerging markets to continue to outperform. EEM started the year with a bang (up nearly 3% on Friday), and in doing so it not only broke above the October downtrend resistance, but the EEM/SPY relative spread just made a fresh high (after months of consolidating). Finally, the largest weighting in EEM is Taiwan Semi (TSM) at over 12% and that too broke out to a new all-time high on Friday as the AI semi trade continues to gain momentum.

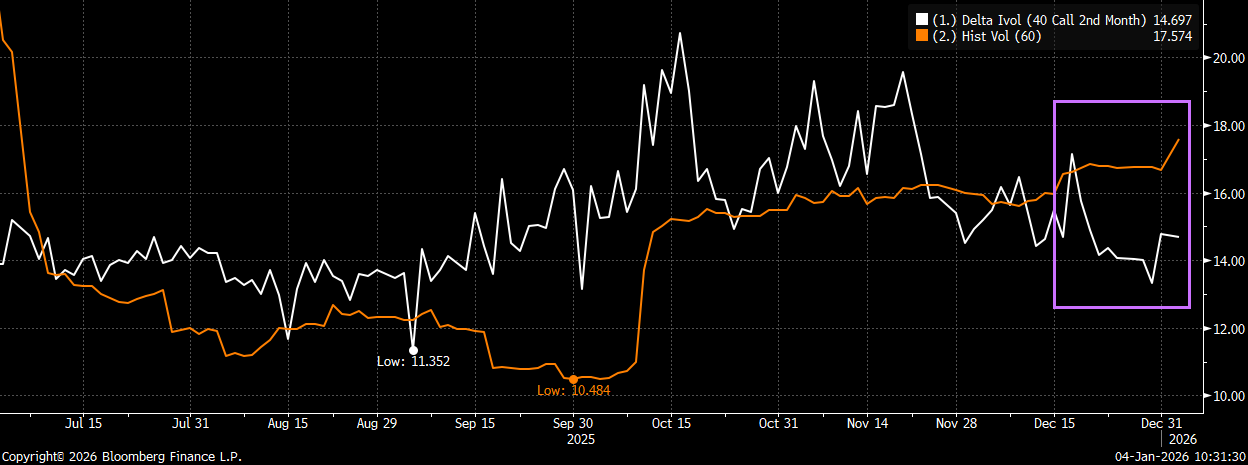
What I also like about owning EEM calls is that 2-month (Feb) implied vol on the 40-delta calls is down sharply from the October highs and now trades at a decent discount to 60-day realized vol. The calls start just over 1% above current levels and have nearly 7 full weeks until expiration.

Please contact me or the 22V sales team for updated pricing and execution capabilities for either idea.

EEM was up 34% in 2025 vs a 17.7% gain for the S&P
A graph of a graph with orange and white lines

AI-generated content may be incorrect.

EEM with a breakout above the October downtrend
A graph on a black background

AI-generated content may be incorrect.

EEM/SPY relative spread with a breakout to new highs after months of consolidation
A graph with lines and numbers

AI-generated content may be incorrect.

EEM 2-month (Feb) 40-delta call implied vol is not only down sharply from the Oct highs, but also trades at a steep discount to 60-day realized vol
A graph with lines and numbers

AI-generated content may be incorrect.

TSM broke out to new all-time highs on Friday
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.